













Covington & Slidell Independent Insurance Agents
A buddy borrows your side-by-side at the deer camp outside Folsom, clips a parked truck, and the owner's knee gets wrenched in the process. Or you come out to the trailer on a Saturday morning in a Slidell motel parking lot and find nothing but cut chain. Those are the calls that make people pull out their homeowners policy for the first time and read the fine print.
Most St. Tammany Parish families own an ATV or UTV for real work and real fun: hauling feeders, checking stands, running mud on the weekend. The coverage question deserves the same attention you'd give the machine itself.
The Reality of Louisiana ATV Insurance Coverage
Louisiana law generally doesn't require insurance on an ATV ridden on private land. Homeowners policies, though, typically exclude liability and physical damage once the machine leaves your property. If you ride at a hunting camp, a mud park, or public trails, a standalone off-road policy is usually the only thing filling that gap.
The trouble is that "not required" gets heard as "not needed." Those are very different statements. The state isn't forcing you to buy coverage, but a lawsuit from an injured rider or a $20,000-plus side-by-side disappearing from camp will cost you the same either way.
Louisiana ATV insurance is built around how people here actually ride. A specialized policy typically offers options that a homeowners policy leaves out, including:
- Liability for injuries or property damage you cause to others
- Collision for damage to your own machine from a crash or rollover
- Comprehensive for theft, fire, vandalism, and storm damage
- Uninsured/underinsured motorist coverage if someone without insurance hits you
That last one surprises people. If another rider with no coverage plows into you on a trail, your own policy may be the only source of recovery.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.
There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.
Why Your Homeowners Policy Rarely Covers Your Side-by-Side
Homeowners policies were written with houses in mind, not motorized recreation. Many of them treat an ATV or UTV as covered only when it's used to maintain the residence premises: mowing, hauling mulch, pulling a small sprayer around the yard. Some include a narrow exception for golf carts or lawn equipment, and a side-by-side may or may not fit that wording depending on the carrier.
Here's where Northshore owners get caught. Your house is in Covington, but your camp is on a lease north of Bush or out toward the Pearl River. The moment the machine leaves your yard, that premises-only language may wipe out liability coverage entirely. Theft protection can shrink too, since many policies limit or exclude motorized vehicles stolen away from the home.
The common mistake we see is assuming a rider or endorsement fixes everything. Some carriers do offer a recreational vehicle endorsement on a homeowners policy, but those often carry low limits, may still restrict where you ride, and might not include collision at all. The only way to know is to read the exclusions section, or have someone walk through it with you. Our view is simple: if you'd be upset losing the machine or defending a lawsuit over it, don't rely on homeowners coverage alone.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Liability Off Your Own Land and at the Hunting Camp
Hunting camps are social places. You've got kids riding double, a cousin who hasn't driven a UTV in three years, trucks parked tight around the skinning shed, and maybe a few cold drinks after dark. That mix is exactly why liability off your own land matters more than most people expect.
Picture a few realistic claims. You back your side-by-side into a camp member's new four-wheeler and crunch the front rack. Your teenage son gives a friend a ride, takes a turn too hot on a gravel lane, and the passenger breaks a wrist. You're crossing a parish road between two tracts and clip a car's fender. In each case, someone may come after you for repairs, medical bills, and lost wages.
A standalone off-road policy typically provides bodily injury and property damage liability that follows the machine wherever you legally ride it. That includes leased hunting land, a friend's property, and many organized riding areas. It may also pay for your legal defense if a claim turns into a lawsuit, which can cost more than the settlement itself.
One thing to keep in mind: who's driving matters. Some policies cover permissive operators, while others restrict coverage for young or unlisted drivers. If the whole camp shares one machine, tell your agent so the policy actually matches how it's used.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Protecting Your Investment from Theft and Trailer Transit
Remote camps are easy targets. A side-by-side sitting under a pole barn for two weeks between weekends, no neighbors for a mile, no cameras: thieves know this pattern. Trailers parked at gas stations, restaurants, and hotels during a trip are another favorite.
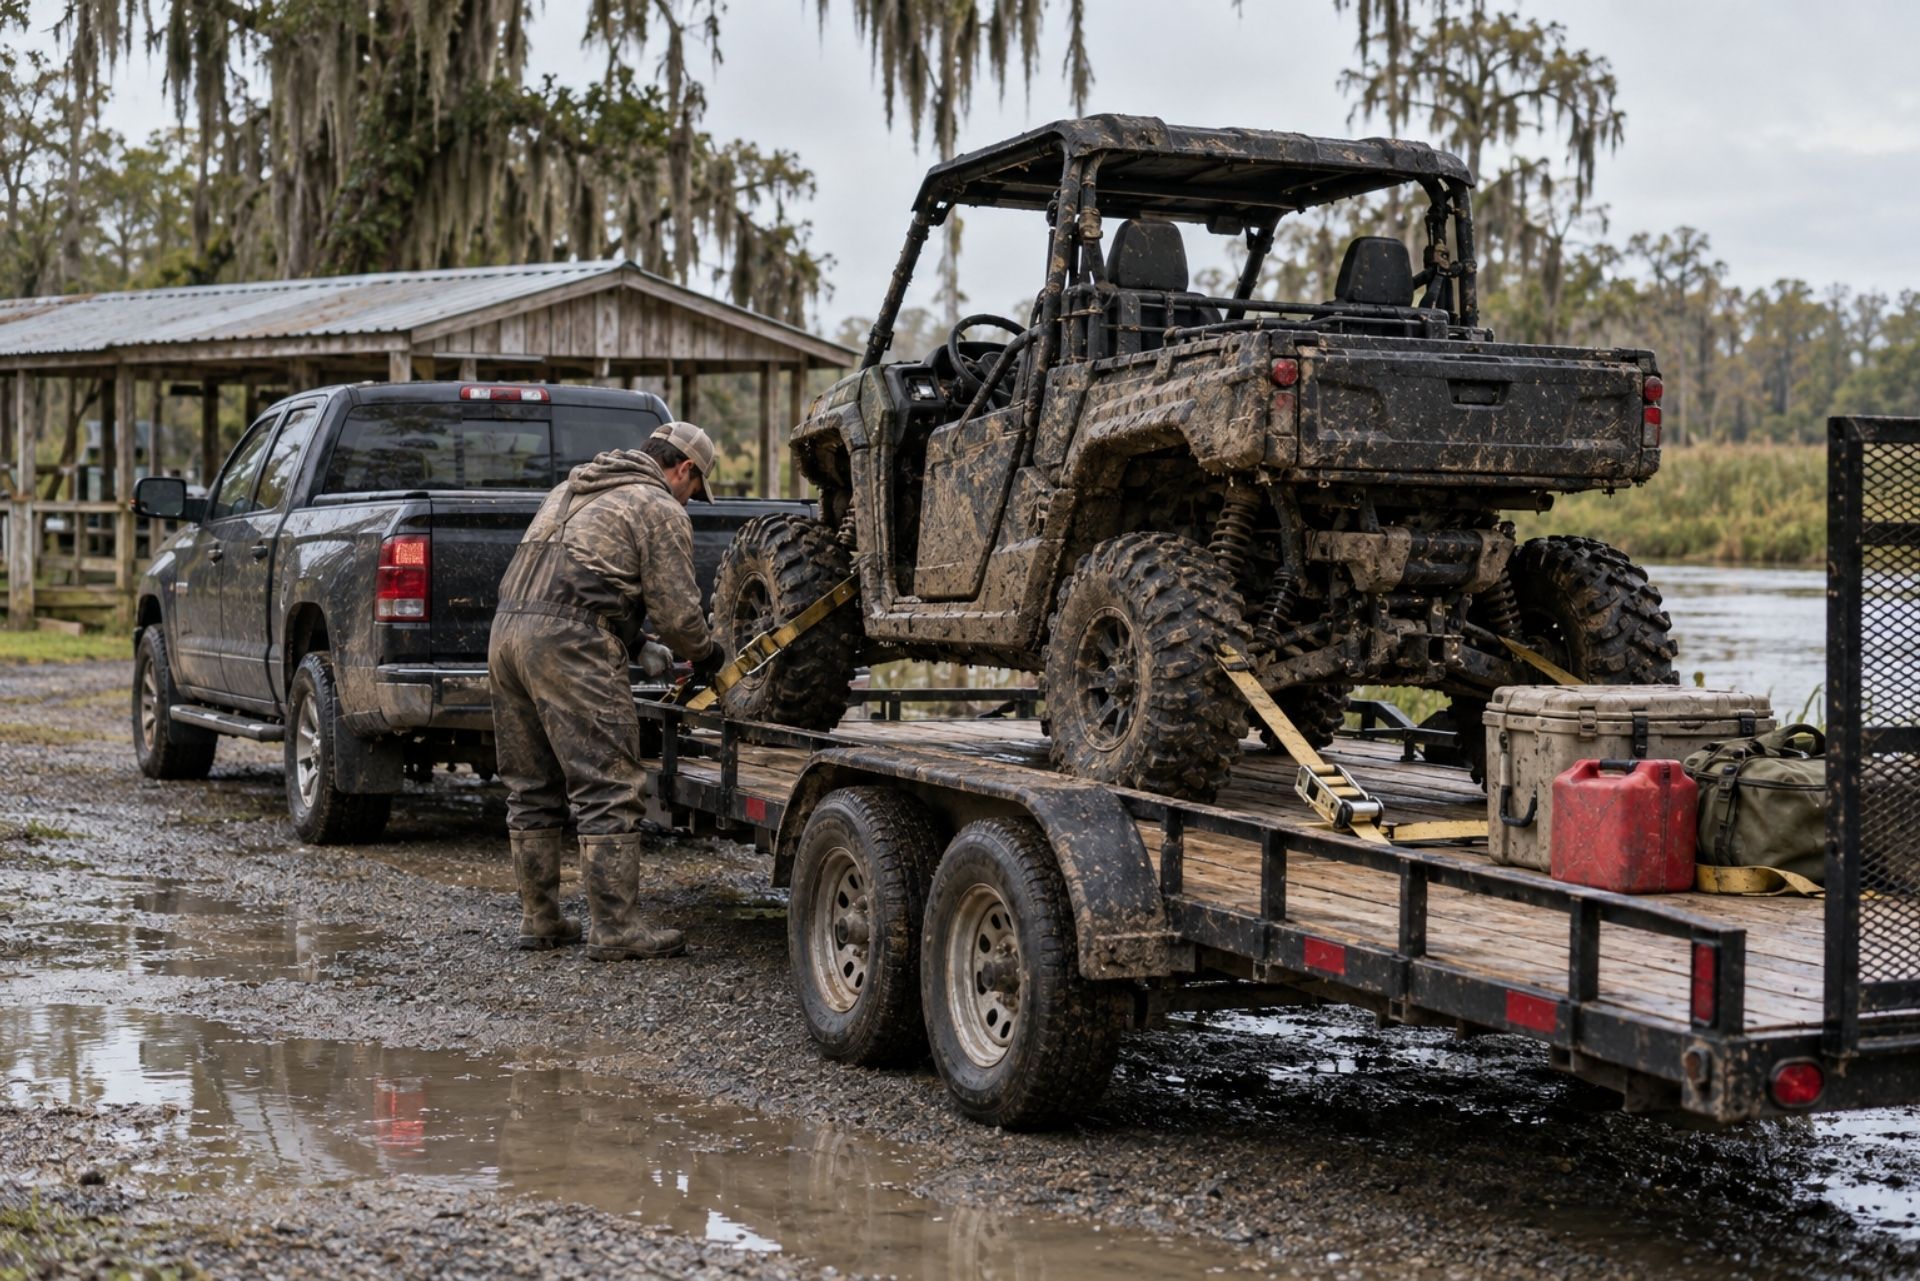
Then there's the drive itself. Interstate 12 and Highway 190 see plenty of trailer traffic, and a sudden stop or a rear-end collision can turn a strapped-down UTV into a crumpled one. Ratchet straps fail, trailers jackknife, and blowouts happen on hot summer pavement.
This is where people misread their auto policy. The towing vehicle's auto insurance typically extends liability coverage to the trailer, so if your trailer swings into another car, that damage may be covered. What it generally doesn't cover is physical damage to the cargo, and your ATV counts as cargo. If the trailer gets hit, or someone drives off with the whole rig, the machine on it usually isn't protected by your truck's policy.
A few practical steps help on both fronts:
- Use a hitch lock and a wheel lock on the trailer, even for a quick stop.
- Chain the machine to the trailer or a fixed post at camp.
- Photograph the VIN, accessories, and upgrades so you can document a claim.
- Ask whether your policy covers aftermarket parts like winches, light bars, and cabs.
Agreed Value and Guaranteed Replacement Cost
These two coverages get confused constantly. Comprehensive typically pays for losses that aren't crashes: theft, fire, vandalism, falling trees, flooding, and hail. Given how often Louisiana camps take a beating from storms, that alone justifies it for many owners.
Collision covers damage when your machine hits something or rolls over, whether that's a stump, another ATV, or the ditch. It also usually applies when the trailer you're hauling it on is in a wreck. If your side-by-side is financed, the lender will likely require both. If it's paid off and older, you might choose comprehensive only, but run the numbers on replacement cost first.
Comparison: Homeowners Extension vs. Specialized ATV Policy
Carrier wording varies, so treat this as a general picture rather than a guarantee for any single policy. It shows where the gaps typically appear.
| Feature | Homeowners Rider/Extension | Dedicated Motorsports Policy |
|---|---|---|
| Liability limits | Often low or capped | Selectable, typically higher |
| Off-premises liability | Usually excluded or very limited | Typically included where legally ridden |
| Theft at camp | May be excluded away from home | Typically covered under comprehensive |
| Theft from trailer | Often excluded | Typically covered under comprehensive |
| Collision damage | Rarely offered | Available as an option |
| Trailer transit damage | Usually not covered | Typically covered with collision |
| Uninsured motorist | Not offered | Often available |
| Accessories/custom parts | Limited or none | Optional coverage available |
| Claim impact | Can affect homeowners premium | Kept separate from your home policy |
That last row deserves attention. Filing an ATV claim against your homeowners policy may put a mark on your home's claim history, which matters in a Louisiana property market where homeowners coverage is already hard to place. Keeping the machine on its own policy protects that record.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Common Questions About Louisiana Off-Road Coverage
Does my insurance cover me at the mud park? Your homeowners policy almost certainly doesn't. A specialized ATV policy typically does cover liability at legal riding areas, though some events or races may be excluded, so check before you go.
What if my side-by-side is stolen from my truck or trailer? Your auto policy generally won't pay for the machine itself. Comprehensive coverage on an ATV policy is what typically handles theft from a trailer, a camp, or your driveway.
Do I need ATV insurance if I only ride on my own land? Louisiana doesn't require it, but injuries to guests and storm or theft losses still happen at home. Many owners find their homeowners policy only covers limited situations even there.
Will my policy cover my kids or friends who drive it? It depends on the carrier and how drivers are listed. Ask specifically about permissive users and young operators before handing over the keys.
Is a UTV insured the same way as a four-wheeler? Usually yes, through the same type of off-road policy. Values differ, though, so a higher-dollar side-by-side may need higher physical damage limits.
Can I suspend coverage during the off-season? Some carriers may offer lay-up options that keep comprehensive active while reducing other coverages. Since theft and storms don't take the summer off, dropping coverage entirely is risky.
Making the Right Choice for Your Louisiana Lifestyle
The pattern is consistent: homeowners coverage tends to stop at your property line, auto coverage stops at the trailer hitch, and the machine you actually ride sits in the gap between them. A dedicated off-road policy is how you close that gap, with liability that follows you to camp, comprehensive for theft and storms, and collision for the trip down I-12.
Aubert Insurance Agency has been insuring what matters most to St. Tammany Parish families since 1910, from offices in Covington and Slidell. As an independent agency, we compare options from multiple carriers in one place and explain what each policy includes and excludes, so you know exactly what you're signing before you ever need to file a claim. The process is straightforward: you start online, we shop for you, and you pick the plan that fits how you ride.
Before deer season opens or your next mud park weekend, take ten minutes and get real answers. Start a Quote with Aubert Insurance Agency and make sure your side-by-side is protected everywhere it goes.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













