













Louisiana Excavation Contractor Insurance

Covington & Slidell Independent Insurance Agents

Louisiana excavation contractors typically need general liability, an inland marine equipment floater, contractors pollution liability, workers compensation, and commercial auto. Together these may cover underground utility strikes, stolen or damaged machinery, fuel spill cleanup, and trench collapse injuries. Coverage depends on carrier forms and exclusions, so the wording of each policy matters as much as the limits.


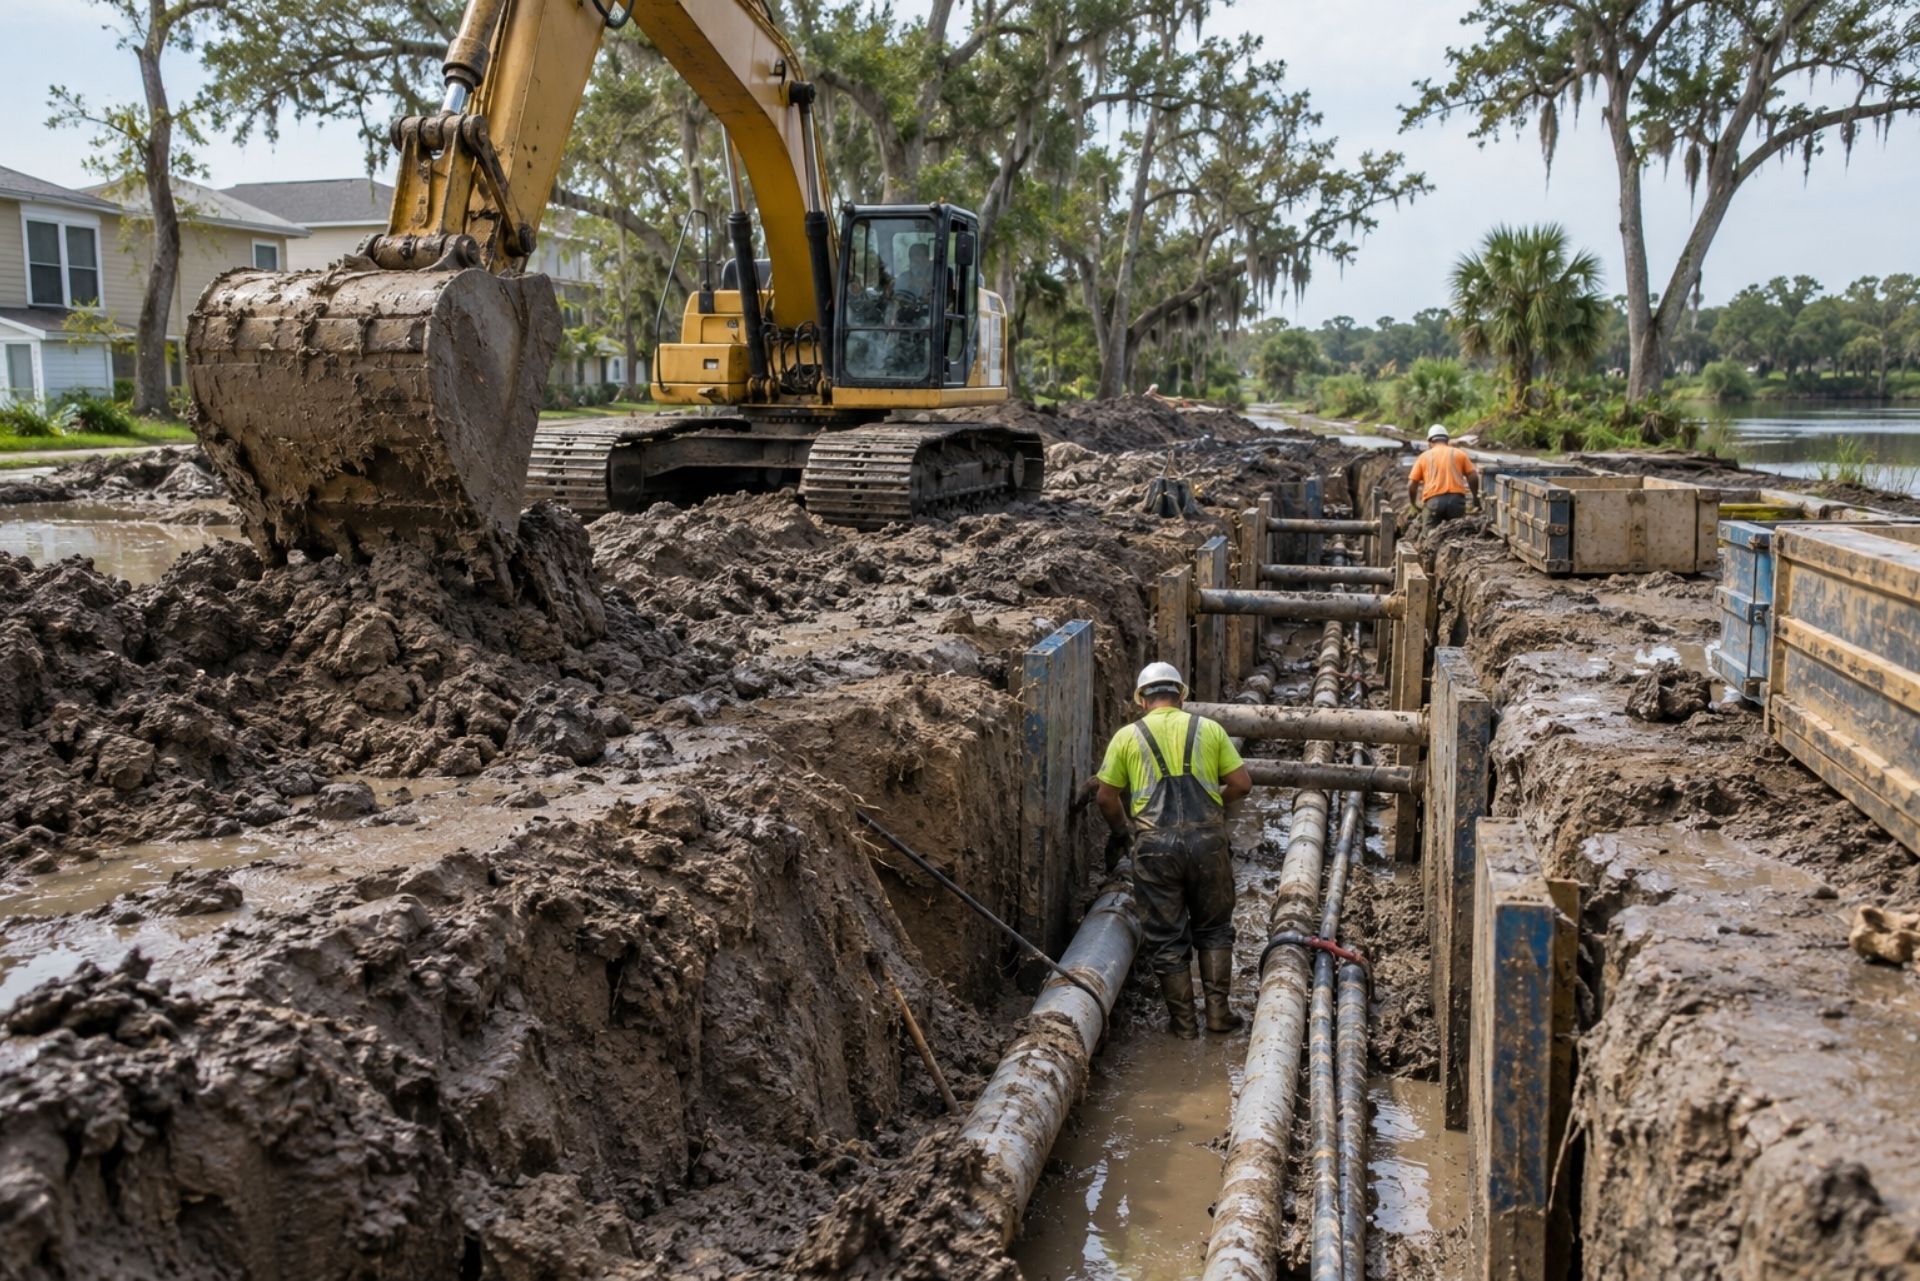
A single bucket swing can turn a routine drainage job in St. Tammany Parish into a five-figure claim. Hit a fiber line, puncture a gas service, or drop a skid steer into a soft trench wall after a week of rain, and the costs arrive fast. That is the reality of digging in south Louisiana soil, where high water tables and dense utility corridors make every project a little less predictable.

Essential Insurance for Louisiana Excavation Contractors

Most excavation firms carry five core policies. Each one handles a different type of loss, and gaps usually show up where one policy stops and the next one has not started.


  • General liability: Third-party bodily injury and property damage, including many utility strikes
  • Inland marine (equipment floater): Your excavators, dozers, trenchers, and attachments, wherever they sit
  • Contractors pollution liability: Fuel, hydraulic fluid, and disturbed contaminated soil
  • Workers compensation: Employee injuries, including trench accidents
  • Commercial auto: Dump trucks, service trucks, and trailers on the road


Licensing rules are tightening too. The Louisiana State Licensing Board for Contractors raised the minimum general liability requirement for residential and home improvement contractors from $100,000 to $500,000 effective August 1, 2026. If you do any residential site work, check that your certificate reflects the new floor. Established firms with vehicle fleets in Louisiana can expect to spend somewhere between $15,000 and $75,000 or more each year on this full package.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

Here's a common scenario: you misjudge a curve and clip a late-model pickup, injuring the driver. A single ambulance ride, ER visit, and follow-up imaging can eat through $15,000 quickly. Anything above your limit can become your personal responsibility, which may put your savings, wages, or home at risk.

Scenario Dwelling limit All-other-perils deductible Named-storm deductible
Newer build, inland St. Tammany $350,000 $1,000 2%
Newer build, higher wind zone $350,000 $1,000 5%
Older home, updated roof $275,000 $2,500 2%
Older home, original roof $275,000 $2,500 5%
Fortified roof designation $400,000 $1,000 2%
Rebuilt after a prior claim $400,000 $2,500 5%
Bundled with auto $350,000 $1,000 2%

Coverage for Damage to Existing Underground Structures

Louisiana sits on one of the densest pipeline networks in the country, and even small residential lots in Covington or Slidell can hide gas services, water mains, and buried fiber. Strikes are the most common large liability claim we see in this trade. The fix starts before any insurance applies: calling 811, waiting for marks, and documenting everything.


State rules shifted in 2026. Contractors on federally funded broadband projects now face a 30-day advance notice and written coordination agreement requirement before standard marking timelines kick in. Skip that step on a BEAD job and a carrier may question whether you followed the law. Louisiana also requires at least one person on every excavation or demolition site to hold proof of completing annual training, which Louisiana 811 provides free of charge.


Keep photos of locate marks, ticket numbers, and the date marks were placed. Those records often decide who pays.

Managing Risks of Underground Utility and Pipeline Strikes

Louisiana sits on one of the densest pipeline networks in the country, and even small residential lots in Covington or Slidell can hide gas services, water mains, and buried fiber. Strikes are the most common large liability claim we see in this trade. The fix starts before any insurance applies: calling 811, waiting for marks, and documenting everything.


State rules shifted in 2026. Contractors on federally funded broadband projects now face a 30-day advance notice and written coordination agreement requirement before standard marking timelines kick in. Skip that step on a BEAD job and a carrier may question whether you followed the law. Louisiana also requires at least one person on every excavation or demolition site to hold proof of completing annual training, which Louisiana 811 provides free of charge.


Keep photos of locate marks, ticket numbers, and the date marks were placed. Those records often decide who pays.

Coverage for Damage to Existing Underground Structures

Here is the policy nuance that trips people up. Many general liability forms include an XCU exclusion, short for explosion, collapse, and underground damage. If your policy carries it, a strike on a gas line may be denied outright. Some carriers write XCU back in by endorsement, and others exclude it for specific classes like directional boring.


Read the exclusions page, not just the declarations. Also look for "your work" and "property in your care" language, since damage to the utility you were hired to install is treated differently than damage to a neighbor's line. A good agent will flag these clauses before you sign.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Coverage Area State Minimum Common Higher Option Stronger Option
Injury, one person $15,000 $50,000 $100,000
Injury, per accident $30,000 $100,000 $300,000
Property damage $25,000 $50,000 $100,000
Who it fits Legal compliance only Riders with modest assets Homeowners, families, higher earners

Here's a common scenario: you misjudge a curve and clip a late-model pickup, injuring the driver. A single ambulance ride, ER visit, and follow-up imaging can eat through $15,000 quickly. Anything above your limit can become your personal responsibility, which may put your savings, wages, or home at risk.

Minimum Coverage vs. Actual Protection Needs

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

Protecting Assets with Heavy Equipment Floaters

Your commercial property policy usually stops at the yard gate. Machinery that moves between job sites needs an inland marine equipment floater, which typically covers theft, fire, vandalism, overturn, and collision while the equipment travels or sits on a site.


Theft is the loss that hurts most. The average heavy equipment theft now runs about $30,000 per incident with only a 21% recovery rate, so most stolen machines never come back. A common client mistake is insuring on actual cash value to lower the premium, then discovering a depreciated mini excavator pays out far below replacement cost.


Things to ask about when comparing floaters:


  • Replacement cost versus actual cash value
  • Coverage for rented or leased equipment, plus rental reimbursement while yours is repaired
  • Flood and named storm terms, which matter a lot in south Louisiana
  • Attachments and tools listed separately or on a blanket limit


Schedule every unit with serial numbers. Unlisted equipment is the easiest claim to deny.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.

Feature Commercial Property Inland Marine (Tool Floater)
Where it applies Your fixed shop location Jobsites, truck, in transit
Typical items Stationary machines, inventory, building Portable saws, nailers, hand tools
Theft from vehicle Usually not covered Often covered, with conditions
Fire or storm at shop Typically covered May be covered if tools are there
Who needs it Carpenters with a shop Nearly every working carpenter

Pollution Liability and Fuel Spill Remediation

General liability policies almost always carry a pollution exclusion. That means a ruptured hydraulic hose leaking into a drainage ditch, a fuel tank tipped during refueling, or contaminated soil you stir up while trenching may not be covered at all. Contractors pollution liability fills that gap and may pay for cleanup, third-party claims, and defense costs.


Louisiana regulators take spills seriously, even if enforcement moves slowly. In the Lake Charles region, LDEQ formal enforcement actions averaged roughly $66,300 in penalties per case through August 2026, and warning letters averaged a 1.7-year delay, with some reaching a ten-year gap. Those figures come from industrial cases, but the lesson for contractors is clear. Advocates have also raised concerns that the agency delayed enforcement and failed to require cleanup in some situations.


Why does that delay matter? A notice can land years after the job ends. Occurrence-based pollution coverage, or a claims-made policy with a long reporting tail, may protect you when that letter finally arrives.

General liability covers physical harm: fires, shocks, and property damage from your work. Professional liability, sometimes called errors and omissions, may cover financial loss from design mistakes or bad advice, such as an undersized service you specified on a load calculation. Electricians who do design-build work, panel sizing for solar, or consulting often need both, because a general liability policy typically will not respond to a pure financial loss.

Safety and Liability Concerns for Trench Collapse

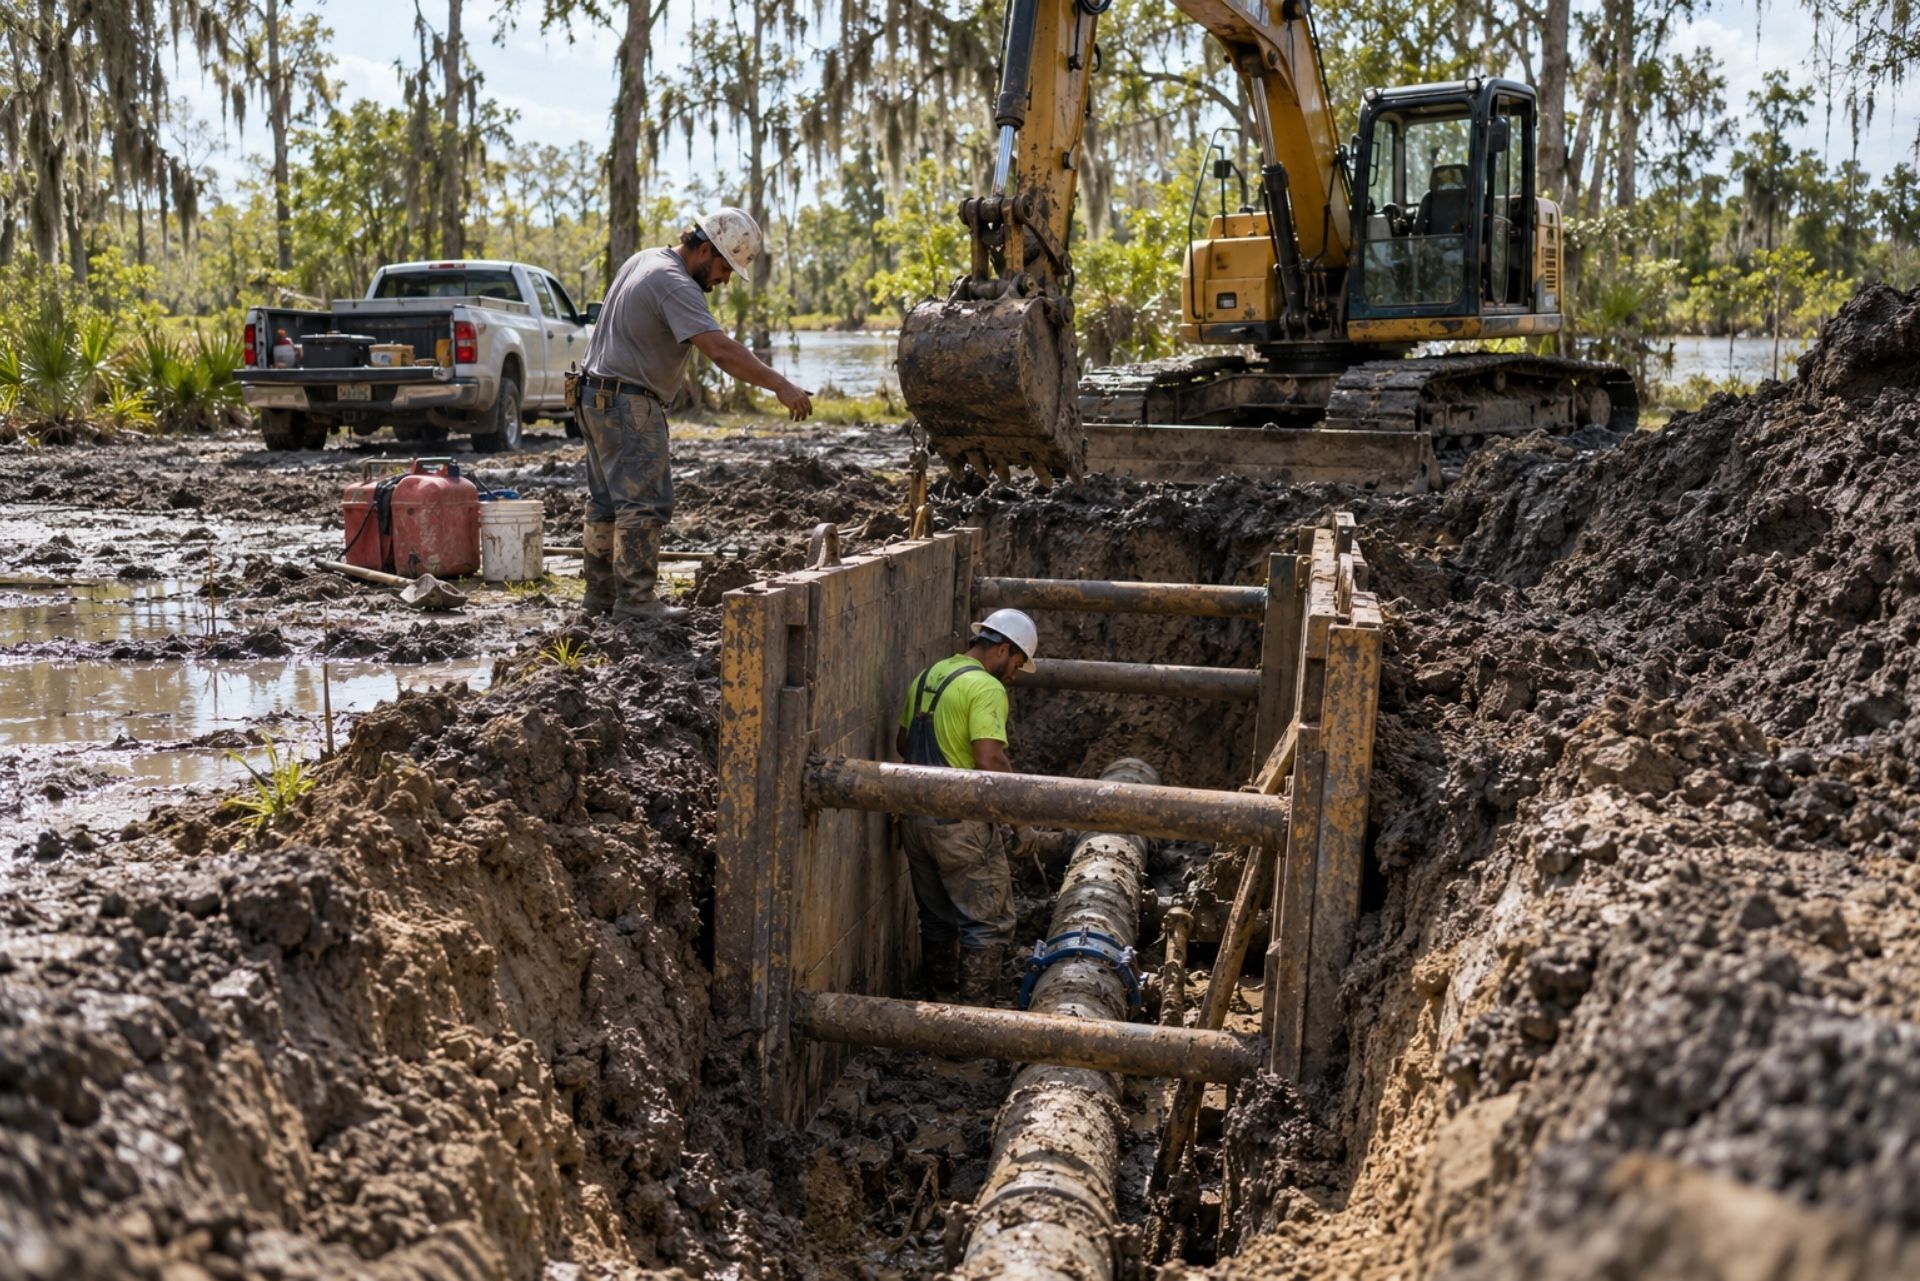
Trench collapse is the risk that keeps owners up at night, and for good reason. A cubic yard of soil weighs about as much as a small car, and wet Louisiana clay and silty sand can shift without warning. Rain, nearby traffic vibration, and spoil piles stacked too close to the edge all raise the odds.


The liability side reaches beyond your own crew. A collapse can undermine a neighbor's driveway, crack a foundation, or swallow a utility line, triggering property damage claims. That is where the XCU exclusion shows up again, since "collapse" is the C in XCU. If your general liability excludes it, a sidewalk caving into your trench might fall on you personally.


Document shoring, sloping, and trench box use daily. A competent person's inspection log is one of the strongest defenses in a lawsuit.

Workers Compensation and Employer Liability

Workers compensation is required in Louisiana for most employers and typically pays medical bills and lost wages after an on-the-job injury. Employer liability, usually bundled as Part Two of the policy, steps in when an injured worker or family sues anyway, often alleging gross negligence.


Watch the employer liability limits. Many policies default to lower limits that may not hold up after a fatal trench collapse, so ask about raising them and pairing them with an umbrella.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.

Feature Commercial Property Inland Marine (Tool Floater)
Where it applies Your fixed shop location Jobsites, truck, in transit
Typical items Stationary machines, inventory, building Portable saws, nailers, hand tools
Theft from vehicle Usually not covered Often covered, with conditions
Fire or storm at shop Typically covered May be covered if tools are there
Who needs it Carpenters with a shop Nearly every working carpenter

Comparing General Liability and Inland Marine Coverage

Contractors often assume one policy handles everything. It does not. This comparison shows how the two most confused policies split the work.

Feature General Liability Inland Marine Floater
What it protects Other people and their property Your own equipment
Utility strike damage Often yes, unless XCU excluded No
Stolen excavator No Typically yes
Equipment rolls into ditch Damage to others only Damage to the machine
Fuel spill cleanup Usually excluded Usually excluded
Where coverage applies Your operations Wherever equipment goes

Notice the pollution row. Neither policy usually handles a spill, which is why a separate pollution policy belongs in the mix.

Common Questions About Excavation Insurance

Do I need insurance if I only dig small residential jobs? Yes. Licensed residential and home improvement contractors now need at least $500,000 in general liability, and a single gas line strike can exceed that quickly.


Does general liability cover hitting a gas line? It may, but only if your policy does not exclude underground damage under an XCU clause. Ask your agent to confirm in writing.


Will my equipment floater cover a machine I rent? Some floaters include rented or leased equipment, and others require an endorsement. Check before the rental company asks for proof.


Is a fuel spill covered under my regular policy? Usually not. Most general liability policies exclude pollution, so you typically need contractors pollution liability.


What does the 811 training rule mean for my crew? At least one person on every Louisiana excavation site must have proof of completing the annual Louisiana 811 training, which is free.


How much does excavation insurance cost? Established Louisiana firms with fleets often spend $15,000 to $75,000 or more per year, depending on payroll, equipment values, and claims history.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.

Feature Commercial Property Inland Marine (Tool Floater)
Where it applies Your fixed shop location Jobsites, truck, in transit
Typical items Stationary machines, inventory, building Portable saws, nailers, hand tools
Theft from vehicle Usually not covered Often covered, with conditions
Fire or storm at shop Typically covered May be covered if tools are there
Who needs it Carpenters with a shop Nearly every working carpenter

Making the Right Choice for Your Louisiana Business

Good excavation coverage comes down to matching each risk to the right policy. Strikes need general liability without a harmful XCU exclusion. Machinery needs a floater at replacement value. Spills need pollution coverage with a reporting window long enough to outlast slow regulators, and trench crews need workers compensation with solid employer liability limits.


Building that package for Louisiana excavation work is easier when someone compares carriers side by side and explains the fine print. Aubert Insurance Agency is an independent agency based in Covington and Slidell that has been insuring Louisiana families and businesses since 1910. We shop multiple carriers for you and walk through exclusions in plain language so nothing surprises you after a claim.


Ready to see your options? Start a Quote with our team today, and get coverage that fits the ground you actually dig in.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
