













Lacombe LA Home Insurance

Covington & Slidell Independent Insurance Agents

Lacombe homeowners usually need more than one policy: a homeowners or dwelling form, separate flood coverage, and sometimes a wind or named storm deductible tied to their location. Raised homes, bayou camps, manufactured homes and seasonal properties each carry different rules. As an independent agency serving the area since 1910, Aubert Insurance Agency helps residents work through these local risks.


Lacombe is a quiet stretch of St. Tammany Parish, but it is a demanding place to insure a house. A home on a pier-and-beam foundation near the bayou, a fishing camp you visit a few weekends a year, and a manufactured home off a gravel road can sit within a few miles of each other. Carriers may treat each one very differently.


Most of the confusion we see comes from people assuming one policy handles everything. It rarely does. Flood is separate. Wind may carry its own deductible. A camp that sits empty for months may not qualify for a standard homeowners form at all.


The sections below cover each of these situations in plain terms, so you know what questions to ask before you sign anything.

Understanding Home Insurance in Lacombe Louisiana

Home insurance in Lacombe is shaped by three things: water, wind and how the home is used. Carriers look closely at distance to Lake Pontchartrain and Bayou Lacombe, the home's elevation, its construction type, and whether someone lives there full time.


The market has also shifted. Between January and April 2026, three new insurers were licensed to write homeowners coverage in Louisiana, adding to the companies that have entered since 2024. More competition can mean more options for North Shore homeowners, though not every new carrier writes every zip code or every property type.


Many Lacombe homes still end up with surplus lines (non-admitted) carriers, especially older homes, camps and properties close to the water. One recent change helps here: as of March 2026, surplus lines insurers must give at least 30 days' notice before non-renewing a policy. That gives you a month to find replacement coverage instead of scrambling.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Many St. Tammany families end up with both: standalone coverage for the land, plus an umbrella over the home and vehicles.

Comparison: Standalone Liability vs. Umbrella Coverage

Understanding the Named Storm Deductible

A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.


There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.

Factor Standalone Liability Umbrella Policy
Underlying policy required No Yes, home and auto typically
When it pays First dollar of a covered claim After underlying limits run out
Typical use Vacant land, hunting tracts, specific risks Broad extra protection across policies
Cost structure Priced by acreage, use, and limit Priced by number of homes, cars, drivers
Scope Narrow, tied to named property or risk Wide, follows underlying coverage
Common limits $300,000 to $1 million $1 million and up

People use the two terms as if they mean the same thing. They do not.


A true umbrella policy may provide broader coverage than the policies below it. In some cases it can "drop down" to cover a claim the primary policy excludes, usually subject to a self-insured retention, often $10,000 or $25,000. An excess policy is typically "follow form," which means it copies the terms and exclusions of the underlying policy and simply adds more limit.


Here is why that matters. If your general liability policy excludes a certain type of claim, a follow-form excess policy will generally exclude it as well. Higher limits do not repair a weak foundation. We go through the endorsements on each layer with clients before binding, because the wording on page 14 of the policy is what decides whether a claim gets paid.

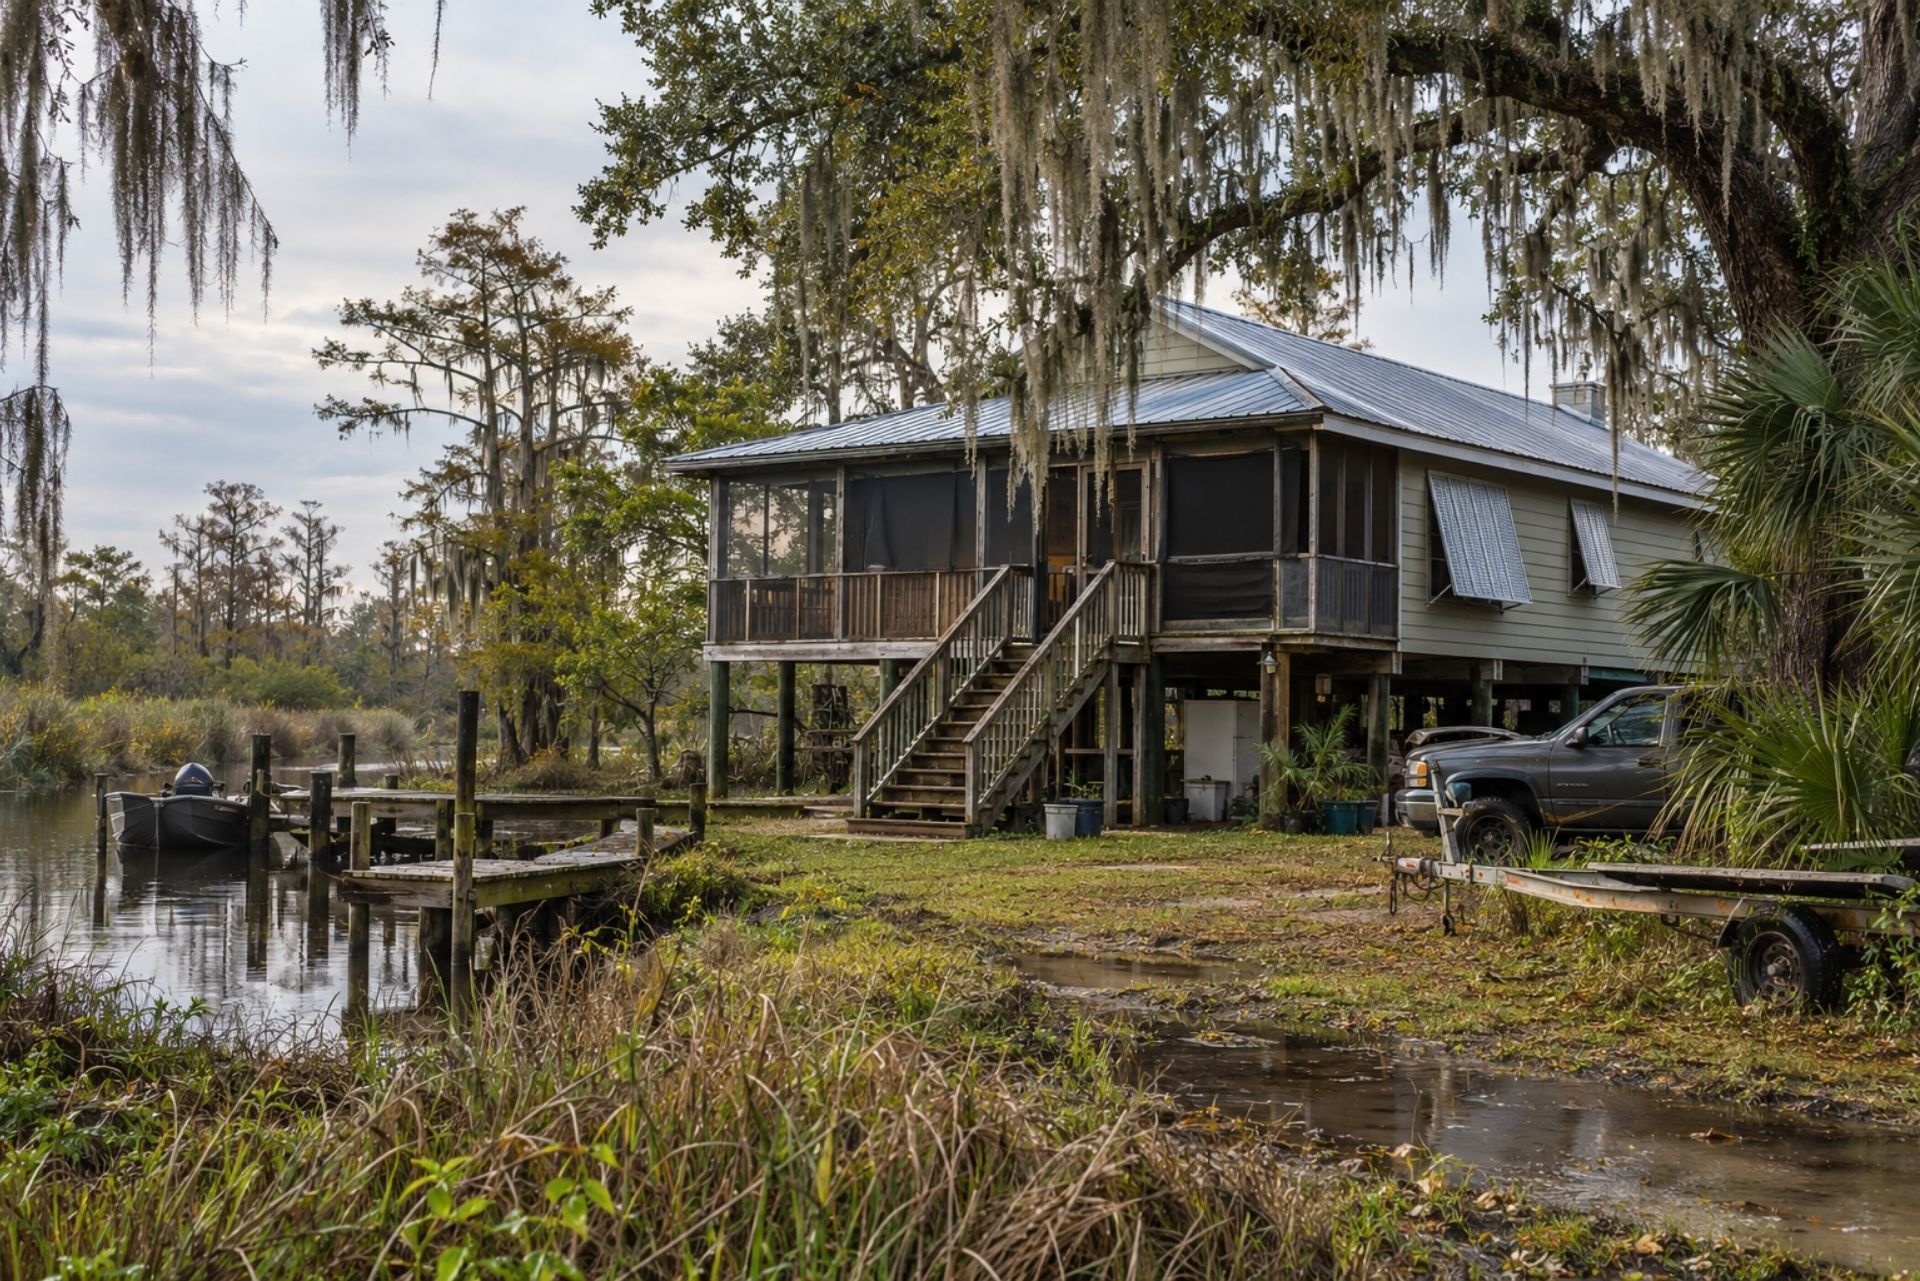
Raised Homes and Camps on Bayou Lacombe

Elevation is one of the biggest factors in what you pay for flood coverage. Homes built at least one foot above the Base Flood Elevation (BFE) may see annual flood insurance savings of roughly $500 to $2,500 compared to slab-on-grade homes. An elevation certificate is the document that proves where your lowest floor sits, and it's worth ordering if you don't have one.


Elevation can affect your homeowners policy too, though in a different way. Some carriers may ask about the enclosure beneath a raised home. A ground-level area finished into a den or bedroom can complicate both flood ratings and claims, because flood policies typically limit coverage for contents and finishes below the lowest elevated floor.


Recreational camps along the bayou come with their own set of questions:


  • Access and construction: Camps reachable only by boat, or built on older pilings, may be ineligible with some carriers.
  • Occupancy: If nobody lives there full time, a homeowners form usually won't fit. A dwelling or seasonal policy is more typical.
  • Docks and boathouses: These may be excluded or need separate scheduling.
  • Contents: Fishing gear, outboard motors and generators often need their own coverage.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

How Sublimits Affect Overtime and Minimum Wage Disputes

Auto Liability vs. General Liability for Mobile Equipment

Peak Season Endorsements

Wind Coverage South of Highway 190

Highway 190 runs east to west through Lacombe, and for many carriers it acts as an informal line on the map. Properties south of 190 sit closer to Lake Pontchartrain and are more exposed to storm surge and hurricane-force wind. As a result, they may face higher wind and hail deductibles, named storm deductibles, or tighter underwriting rules than homes a few miles north.


Here's what that means for you. A home south of the highway might carry a named storm deductible set as a percentage of the dwelling limit, often 2% to 5% depending on the carrier. On a home insured for $300,000, a 5% deductible means you'd pay the first $15,000 of hurricane damage yourself. That number surprises a lot of people at claim time.


Some carriers may exclude wind entirely in certain coastal areas, which pushes the homeowner toward a separate wind policy or the state's insurer of last resort. Before you buy, check whether your quote includes wind, how the deductible is calculated, and whether it applies to named storms only or all wind and hail events. A fortified roof or wind mitigation features may help lower your premium with some carriers.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Scenario Dwelling limit All-other-perils deductible Named-storm deductible
Newer build, inland St. Tammany $350,000 $1,000 2%
Newer build, higher wind zone $350,000 $1,000 5%
Older home, updated roof $275,000 $2,500 2%
Older home, original roof $275,000 $2,500 5%
Fortified roof designation $400,000 $1,000 2%
Rebuilt after a prior claim $400,000 $2,500 5%
Bundled with auto $350,000 $1,000 2%

Exact terms vary by carrier, so treat this as a starting point for comparing quotes.

Insuring Mobile and Manufactured Homes

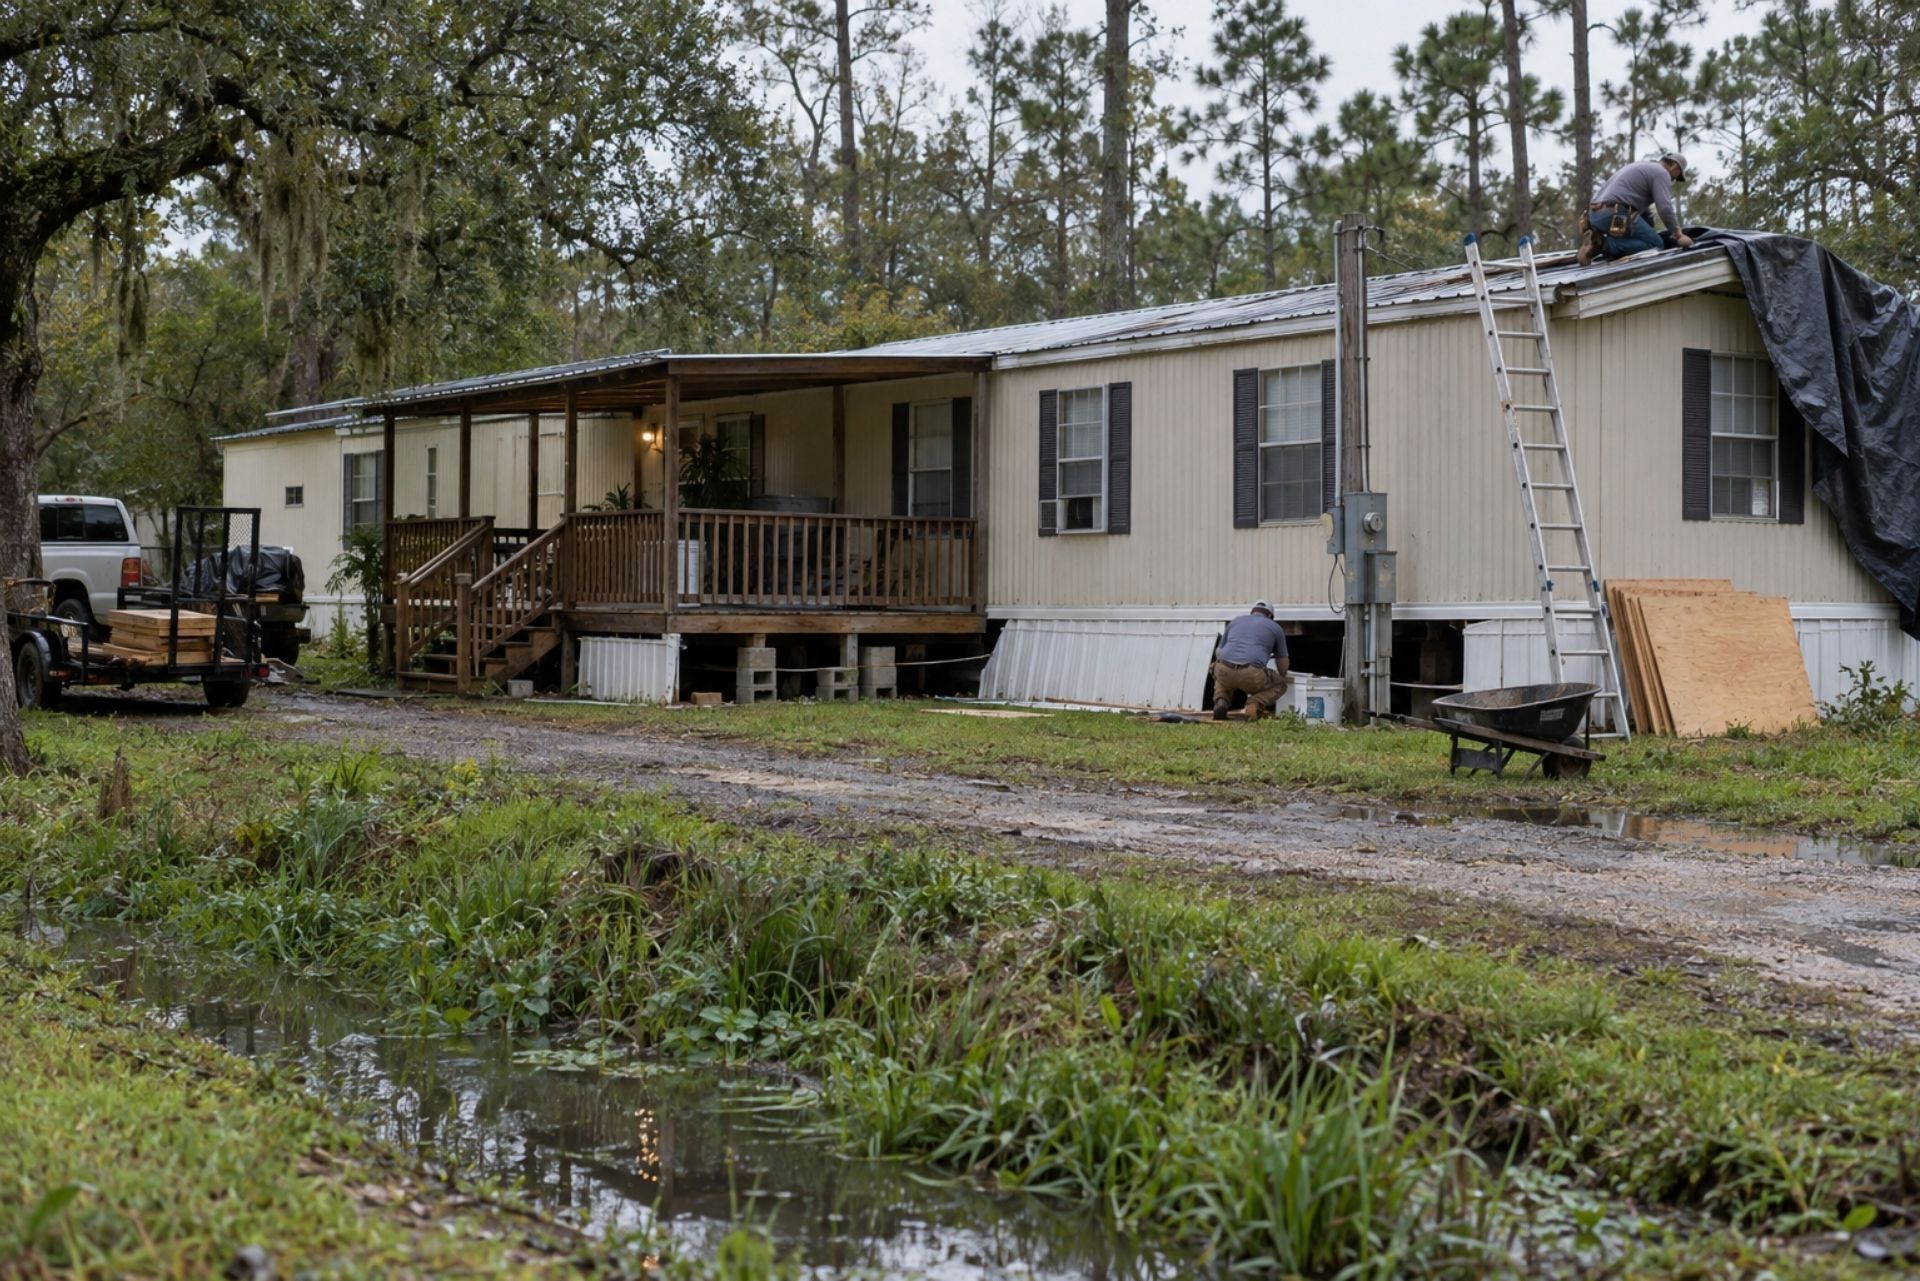
Manufactured homes are common in parts of Lacombe and across St. Tammany Parish, and they need a policy written for them. A standard homeowners form generally won't cover a mobile home. Carriers that do write them look hard at a few details.


Age is the first hurdle. Many carriers set cutoffs for the home's model year, and older units may only qualify for limited coverage, such as actual cash value instead of replacement cost. Homes built to HUD standards after 1976 typically have more options than earlier units.


Anchoring and tie-downs matter just as much in hurricane country. Carriers may ask for proof that the home is properly tied down and set on an approved foundation or piers. Skirting, the condition of the roof, and whether the home sits on owned land or in a park can also affect eligibility. If your home is south of Highway 190, expect wind to be the toughest piece to place.


One common mistake: owners forget that additions, carports and porches built onto a manufactured home may be treated as other structures with separate limits. List them when you get a quote.

Working capital matters more than almost anything else. Underwriters look at current assets minus current liabilities, because cash and receivables are what keep a job moving when a payment runs late. Equity in equipment or real estate helps, but it doesn't pay a subcontractor on Friday.


Expect requests for CPA-prepared financial statements once you seek larger limits. Personal credit counts heavily for smaller firms, since owners typically sign personal indemnity. Clean books, a solid bank line of credit, and low debt can raise your capacity faster than any sales pitch.

Feature General Liability Professional Liability (E&O)
Coverage trigger Typically occurrence-based: injury or damage during the policy period Typically claims-made: claim first made and reported during the policy period
What it addresses Bodily injury and physical property damage from operations Financial loss from errors, omissions or negligent professional services
Example claim A visitor trips over equipment at your site visit Undersized HVAC design forces a costly retrofit
Typical exclusions Professional services, design errors Bodily injury or property damage unrelated to services (varies), contractual liability, fraud, cost estimate guarantees
Defense costs Usually outside limits Often inside limits

Vacant Properties and Seasonal Occupancy

Homes that aren't someone's primary residence are a different risk in a carrier's eyes. Nobody is around to notice a leaking pipe, a tripped breaker, or a broken window after a storm. Small problems turn into large claims, and vacant properties also draw theft and vandalism.


This catches people off guard in a few common situations. You inherit a parent's house in Lacombe and leave it empty while the estate settles. You move to Covington and list your old home for sale. You own a camp you use mainly in fishing season. In each case, the original homeowners policy may restrict or deny coverage once the home has sat vacant beyond a set period, often 30 or 60 days depending on the policy language.


The price difference is real. The average annual premium for a vacant home policy in Louisiana is around $4,202, which runs roughly 50% to 60% higher than a standard occupied policy. That stings, but paying it beats discovering a denied claim after a pipe bursts in an empty house.

Standard vs. Specialized Property Coverage

Matching the policy form to how the home is actually used is the step most people skip.

Situation Typical Policy Key Limitation
Owner lives there full time Homeowners (HO-3) Vacancy clauses may apply if you move out
Rented to tenants Dwelling fire (DP-3) No coverage for tenant belongings
Seasonal camp Seasonal or dwelling policy Theft and freeze limits may be tighter
Empty or for sale Vacant dwelling policy Higher premium, fewer covered perils
Under renovation Builder's risk or vacant policy Must disclose work in progress

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Feature General Liability Business Personal Property
Protects against Claims from others Damage to your own stuff
Slip and fall injuries Yes, typically No
Inventory damaged by fire No Yes, typically
Legal defense costs Usually included Not applicable
Seasonal stock increases Not applicable May need peak season endorsement
Employee theft No Usually excluded
Named storm deductible Not applicable Often applies

Common Questions About Lacombe Property Insurance

Do I need flood insurance if I'm not in a high-risk flood zone? Lacombe sees heavy rain and bayou flooding outside mapped high-risk zones, so flood coverage is worth serious thought. Homeowners policies typically exclude flood.


How long does it take for flood coverage to start? The National Flood Insurance Program usually requires a 30-day waiting period. Private flood insurers in Louisiana may offer waiting periods as short as 10 to 15 days.


Why is my wind deductible so much higher than my regular deductible? Carriers often price hurricane risk separately, especially closer to Lake Pontchartrain. Your named storm deductible may be a percentage of your dwelling coverage rather than a flat dollar amount.


Can I insure an older mobile home? Often yes, though options may be limited. Age, anchoring and roof condition typically decide which carriers will write it and whether it gets replacement cost or actual cash value.


What happens if my surplus lines carrier won't renew me? They must now give you at least 30 days' notice, which applies to non-renewals in the surplus lines market. Call your agent as soon as that letter arrives.


Does my homeowners policy cover my camp? Usually not, unless it's listed on the policy. A separate seasonal or dwelling policy is the typical route.

Working capital matters more than almost anything else. Underwriters look at current assets minus current liabilities, because cash and receivables are what keep a job moving when a payment runs late. Equity in equipment or real estate helps, but it doesn't pay a subcontractor on Friday.


Expect requests for CPA-prepared financial statements once you seek larger limits. Personal credit counts heavily for smaller firms, since owners typically sign personal indemnity. Clean books, a solid bank line of credit, and low debt can raise your capacity faster than any sales pitch.

Feature General Liability Professional Liability (E&O)
Coverage trigger Typically occurrence-based: injury or damage during the policy period Typically claims-made: claim first made and reported during the policy period
What it addresses Bodily injury and physical property damage from operations Financial loss from errors, omissions or negligent professional services
Example claim A visitor trips over equipment at your site visit Undersized HVAC design forces a costly retrofit
Typical exclusions Professional services, design errors Bodily injury or property damage unrelated to services (varies), contractual liability, fraud, cost estimate guarantees
Defense costs Usually outside limits Often inside limits

Making the Right Choice for Your Lacombe Home

The right policy in Lacombe depends on specifics: your elevation, which side of Highway 190 you're on, whether the home is site-built or manufactured, and how often anyone is there. A single online quote rarely accounts for all of that. Getting it wrong usually shows up at the worst time, after a storm or a long vacancy.


Read the declarations page closely. Look at how the wind deductible is written, confirm flood is handled separately, and make sure your occupancy matches what the carrier thinks it is. If something isn't clear, ask before you buy.


That's where an independent agency helps. Aubert Insurance Agency compares coverage from multiple carriers in one place and walks you through what each policy does and doesn't cover, so the exclusions don't come as a surprise. The process is simple: start online, we shop for you, and you pick the plan that fits your home and budget.


Whether you own a raised house on the bayou, a weekend camp, or a manufactured home north of the lake, Start a Quote with Aubert Insurance Agency today and get coverage built around how you actually live in Lacombe.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
