













Covington & Slidell Independent Insurance Agents
One afternoon in late August, a Mandeville contractor called to bind coverage on a slab that had just been poured. A system was spinning off the Yucatán at the time. He got his policy, but only because he called before that storm earned a name. Two days later, the same request would likely have hit a wall.
Louisiana builders and homeowners deal with this timing problem every hurricane season. Builders risk insurance looks simple on paper, but the details matter: when you buy it, what the project is worth, and whether you are building new or opening up an existing house. Each of these shapes what a carrier will offer.
This guide covers how local Louisiana agents place US Assure builders risk, how named storm restrictions usually work, and what information you need ready for a quote. It is written for St. Tammany Parish homeowners planning a remodel, custom home builders in Covington, and small commercial contractors working near Slidell. The goal is simple: lock in coverage before the weather or the paperwork slows you down.
Builders Risk Coverage for Louisiana Construction Projects
Aubert Insurance Agency, serving Covington and Slidell since 1910, places US Assure builders risk coverage for new construction and remodels throughout Louisiana. As an independent agency, they can quote residential and commercial projects online, explain the exclusions in plain language, and help you bind coverage before a named storm restriction takes effect.
US Assure acts as the exclusive program administrator for a builders risk plan insured by Zurich. The program covers residential and commercial projects in all 64 Louisiana parishes. That reach is useful in St. Tammany, where one builder may have a custom home under way in Abita Springs and a spec house going up in Lacombe at the same time.
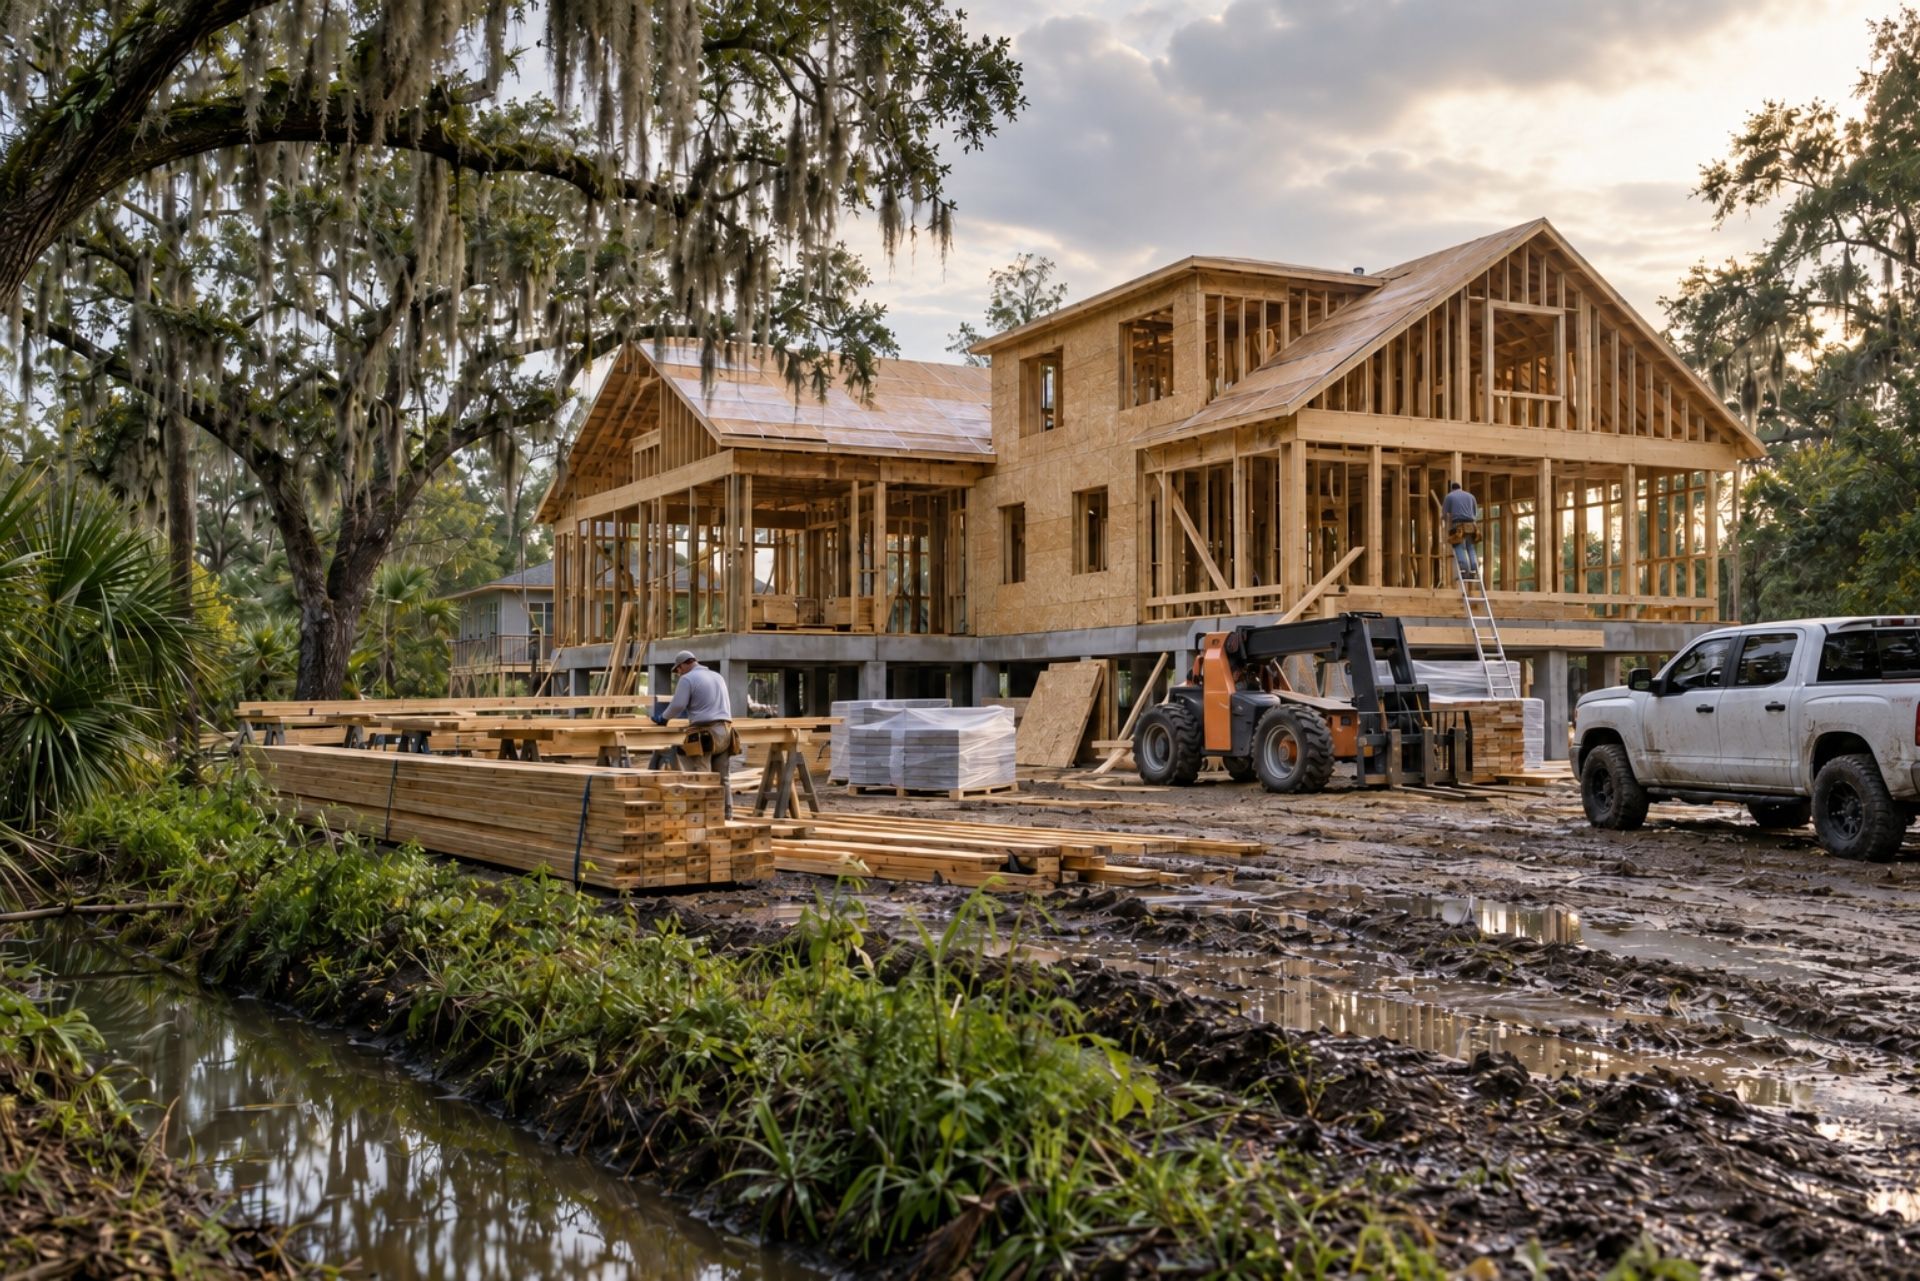
Builders risk covers the structure while it is being built. Lumber, windows, roofing, and framing are all exposed at this stage, often before anyone lives on site or the house can be locked. In Louisiana, the usual threats are wind, theft of materials, and fire. A finished-home policy is not designed to handle any of these during construction.
Pricing for a
Zurich builders risk policy in Louisiana starts at a $375 minimum premium. The final cost depends on the project type and location. A remodel in Slidell and a new build on the north shore may come in at very different numbers.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
How Named Storm Restrictions Typically Apply in Louisiana
Most carriers that write property coverage along the Gulf use what the industry calls a binding moratorium. Once a tropical system is named and enters a defined geographic box in the Gulf of Mexico, the carrier may stop issuing new policies in the threatened area. Some carriers draw that box with latitude and longitude lines. Others trigger the restriction when a watch or warning covers certain parishes.
The restriction often reaches beyond new business. During a moratorium, a carrier may also refuse to:
- Increase limits on an existing policy
- Add a new location or project
- Lower a wind or named storm deductible
- Change the property address on the policy
These moratoriums are routine during hurricane season, which runs from June 1 through November 30. They usually lift once the storm moves out of the box or dissipates. Your agent cannot override them, and they do not consider whether your job is well inland or how much your project budget may have grown.
After a storm passes, state rules can affect how claims are handled. Under the Louisiana Department of Insurance's Emergency Rule 50, effective June 18 through July 22, 2026, insurers were given 60 days to begin loss adjustment on property claims in storm-impacted parishes. The text of the rule is available through the LDI's emergency rule filing, and the industry compliance summary explains how it applies in practice.
Timing Your Policy Before a Storm Approaches
The most common mistake is waiting until the slab is poured or the framing crew shows up before buying coverage. Bind the policy as soon as you have a permit and a start date. If the project value increases partway through, request the endorsement in April or May, before the season starts. Do not wait until a system is already forming in the Gulf.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Accounting firms hold Social Security numbers, bank details, and tax records, which makes them prime targets. One industry observer put it bluntly: for most CPA firms, cyber insurance is no longer optional, and failing to meet MFA and EDR requirements can result in denied claims or total exclusion from the market. Translation: carriers now want multi-factor authentication and endpoint detection software in place before they will write you, and they may check after a claim. A cyber policy may cover breach notification, forensic investigation, ransomware response, and lawsuits from affected clients.
Cyber Liability
US Assure Policy Options for New Construction and Remodels
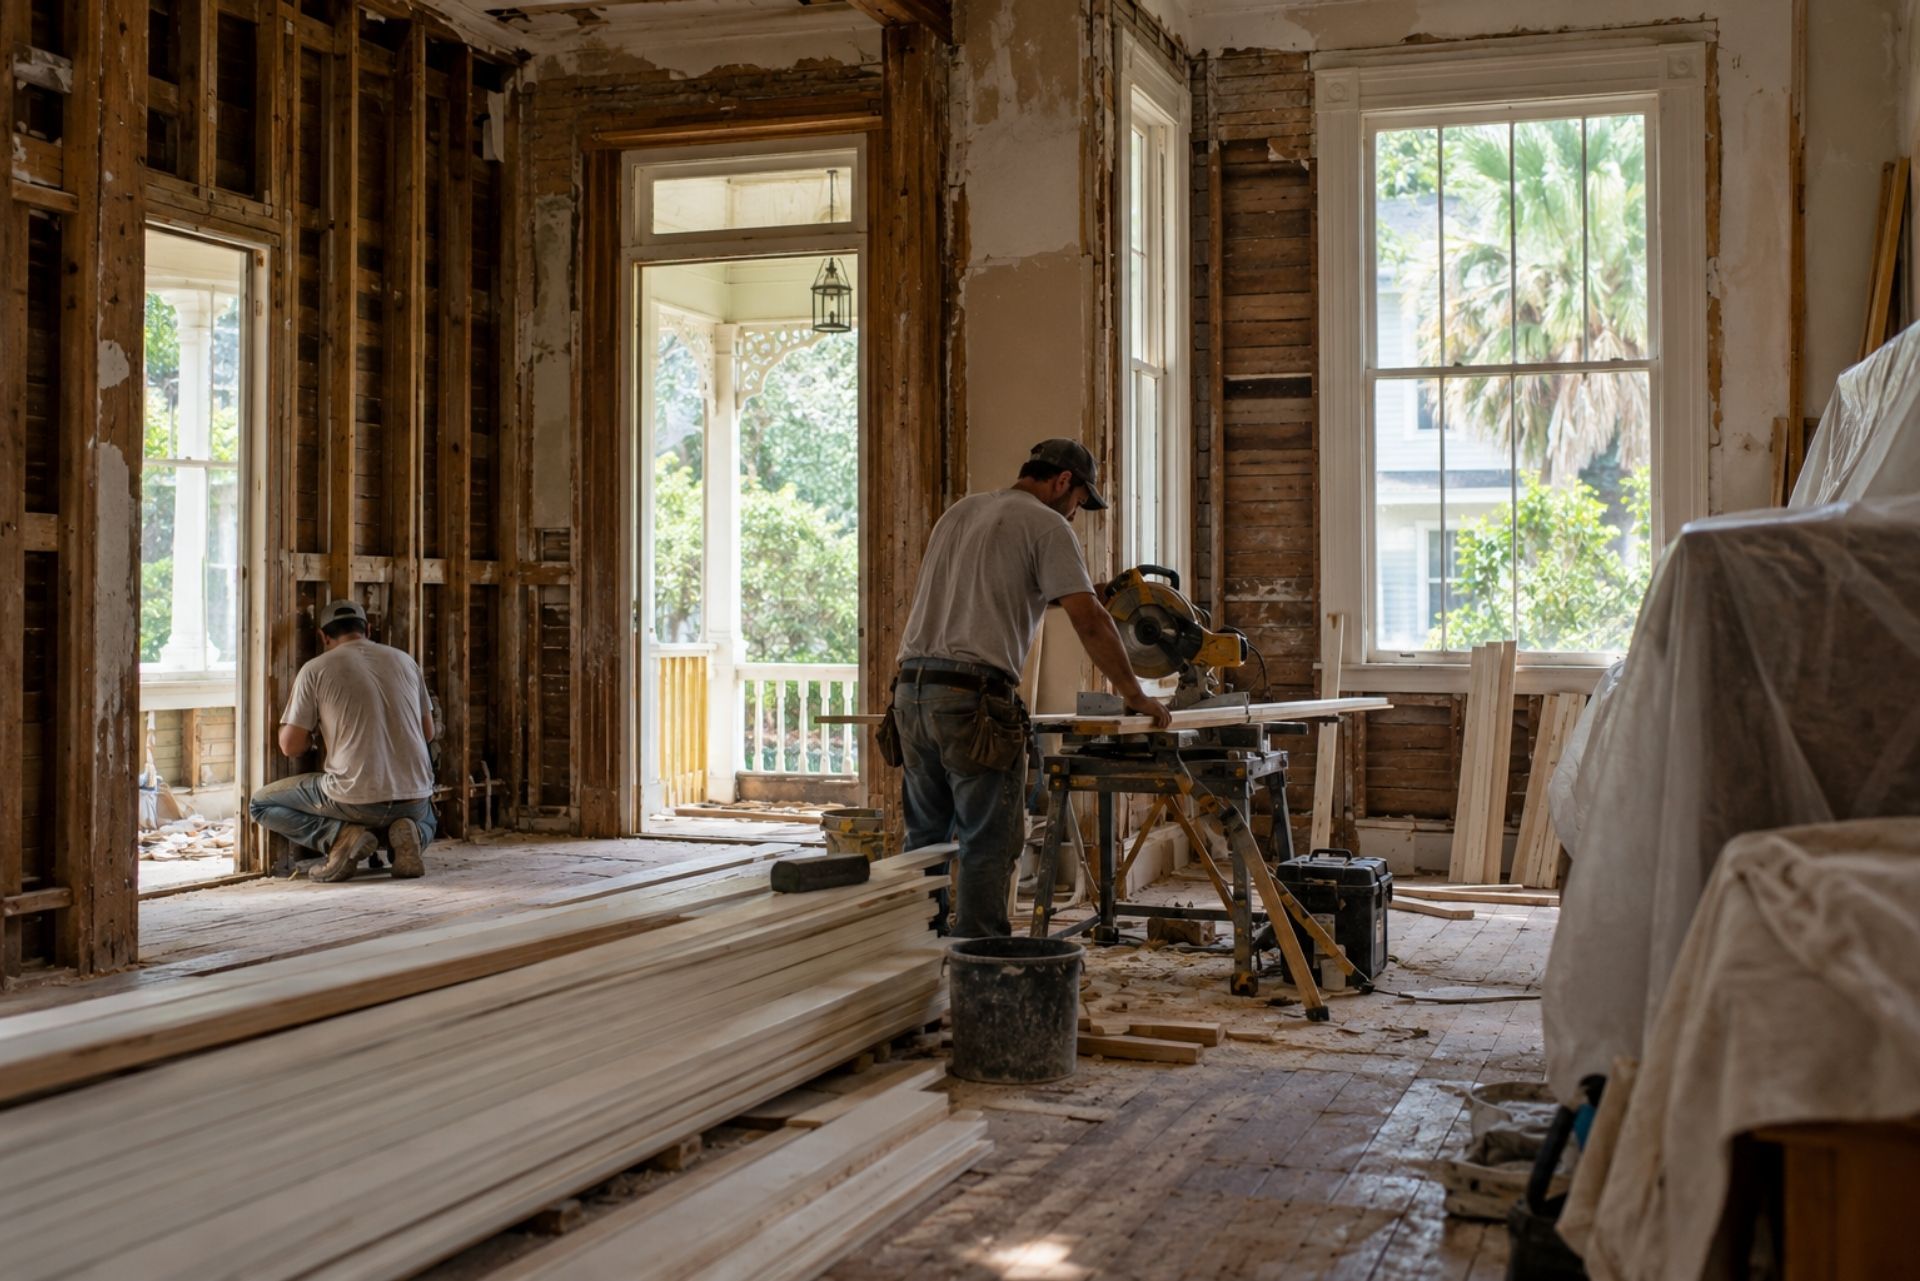
New construction and remodels use different policies because the risks are different. A new build begins with no structure, so everything going up is new value. A remodel starts with a house that already has a value, and many carriers are reluctant to insure that existing structure under a construction policy.
US Assure handles this with a qualification rule. Clients are generally required to invest at least 20% of the existing structure's value into the renovation before the existing building can be insured. For example, on a $300,000 home, that means a renovation budget of at least $60,000.
| Feature | New Construction | Remodel/Renovation |
|---|---|---|
| Existing structure | Not applicable | May be covered if renovation meets the 20% threshold |
| New materials and labor | Typically covered | Typically covered |
| Streamlined application | XPressBIND may apply under $500K | Standard application |
| Engineering plans | Not typically required | Stamped plans required for major structural work |
| Occupancy during work | Usually vacant | Often occupied, which affects terms |
For residential new construction under $500,000, agents can use the XPressBIND system for a faster application. Major structural remodels move more slowly, because they require stamped engineering plans for underwriting review before a quote can be finalized.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
National carriers bring scale: large claims departments, medical networks, data on thousands of similar injuries, and polished safety libraries. What they don't have is a desk in St. Tammany Parish. A local agent knows how a Slidell contractor's subcontractor arrangements typically work and which Covington medical providers injured workers actually use. That agent can also explain Louisiana's own rules in plain language.
The strongest setup combines both. The carrier provides the financial muscle and specialized services. The local agency provides advocacy, so when an adjuster and an employer disagree, someone who knows you is there to push back.
Quoting Requirements for Builders and Property Owners
Collecting this information before you call can cut days off the quoting process. Licensed Louisiana agents can quote and issue policies online for projects valued up to $10 million. That only works if the application data is complete.
- Total Completed Value (project budget): This figure includes labor, overhead, and materials. It excludes the cost of the land. If you underestimate it, you may end up underinsured at claim time.
- Construction type: Frame, joisted masonry, masonry noncombustible, and similar classes each rate differently.
- Protection class: This is based on the distance to the nearest fire station and hydrant. Rural lots in northern St. Tammany may rate differently from sites inside Covington city limits.
- Site security measures: Fencing, lighting, cameras, and locked storage for materials can all affect eligibility and pricing.
- Project address and start date: These are needed for wind exposure and policy term.
- Policy term: Estimate the build schedule realistically. Weather delays in Louisiana are common.
- For remodels: You will need the value of the existing structure, the renovation budget, and engineering plans if the work is structural.
Larger commercial projects follow a different track. Projects valued up to $75 million are eligible but require manual underwriting review, so plan extra lead time for those.
How Jones Act Exposure Differs From State Workers Comp
Standard Auto vs. Hagerty Collector Insurance
Comparing Builders Risk vs. Standard Property Insurance
Many owners assume their homeowners policy will cover a remodel or an addition. Sometimes it covers part of the work, but the gaps tend to show up at the worst time, such as when $18,000 in cabinets disappears from the driveway the night before installation.
| Exposure | Builders Risk (Typical) | Standard Homeowners/Property |
|---|---|---|
| Materials on site, not yet installed | Often covered | Often limited or excluded |
| Materials in transit | May be covered | Usually excluded |
| Materials stored off site | May be covered | Usually excluded |
| Structure under construction | Designed for it | May exclude or restrict |
| Vacancy during build | Built in | Vacancy clauses may restrict |
| Contractor's tools | Usually excluded | Usually excluded |
The vacancy issue is the gap most people miss. Many homeowners policies limit coverage after a home has been unoccupied for a set period, and a gut renovation that forces you to move out can trigger that limit. Builders risk is written for a property that sits empty while work is done. Have your agent compare the actual policy wording, because exclusions differ from carrier to carrier.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| What it covers | Physical injuries and property damage | Mistakes, oversights, bad advice |
| Example claim | Client slips in your lobby | Missed tax deadline costs a client penalties |
| Included in a BOP? | Usually yes | Usually no |
| Who needs it | Nearly every office with visitors | Accountants, consultants, agencies giving advice |
| Policy trigger | Usually occurrence-based | Usually claims-made |
Common Questions About Louisiana Builders Risk Insurance
What happens if a hurricane is named before I buy? If the storm is inside the carrier's restricted zone, new coverage is typically unavailable until the restriction lifts. You will have to wait until the storm passes.
Does builders risk cover my tools? Usually not. Tools and equipment are typically insured under a separate inland marine or contractor's equipment policy.
Can I add a remodel to my current home policy? In some cases a small project can be handled with an endorsement. Large or structural remodels usually need builders risk, particularly if you will be living somewhere else during the work.
Can my insurer cancel my policy in the middle of the project? Under Advisory Letter 2026-01, surplus lines insurers must give at least 30 days' advance written notice before they cancel or non-renew a property policy.
Who should buy the policy: the builder or the owner? Either one can, depending on the contract. Read your construction agreement first so you do not end up with two policies or no policy at all.
How fast can I get coverage? Smaller residential projects with complete information can often be quoted and bound the same day.
How Jones Act Exposure Differs From State Workers Comp
Your Next Steps for Project Protection
Builders risk in Louisiana comes down to three things: the right policy type, accurate project numbers, and good timing. Choose new construction or remodel coverage based on what is actually being built. Calculate your total completed value without the land. Bind the policy well before a named storm moves into the Gulf.
Aubert Insurance Agency has insured families and businesses in St. Tammany Parish since 1910. As an independent agency, the team compares options and explains how the coverage works, including what it excludes. That way you know where you stand before the first truckload of lumber arrives.
Ready to protect your project? Start a Quote with Kyle Beerbohm and the team in Covington or Slidell. Bring your budget, plans, and start date, and the team will handle the rest. Doing this during the off-season can save you from scrambling to find coverage once a storm is already named.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Visit
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













