













Louisiana Tree Service Insurance

Covington & Slidell Independent Insurance Agents

Louisiana tree service insurance typically combines general liability, commercial auto, inland marine for equipment, and workers' compensation. The hardest piece to place is workers' comp, because tree work carries some of the highest injury rates of any trade. Crews in St. Tammany Parish should expect careful underwriting, safety questions, and payroll-driven pricing.


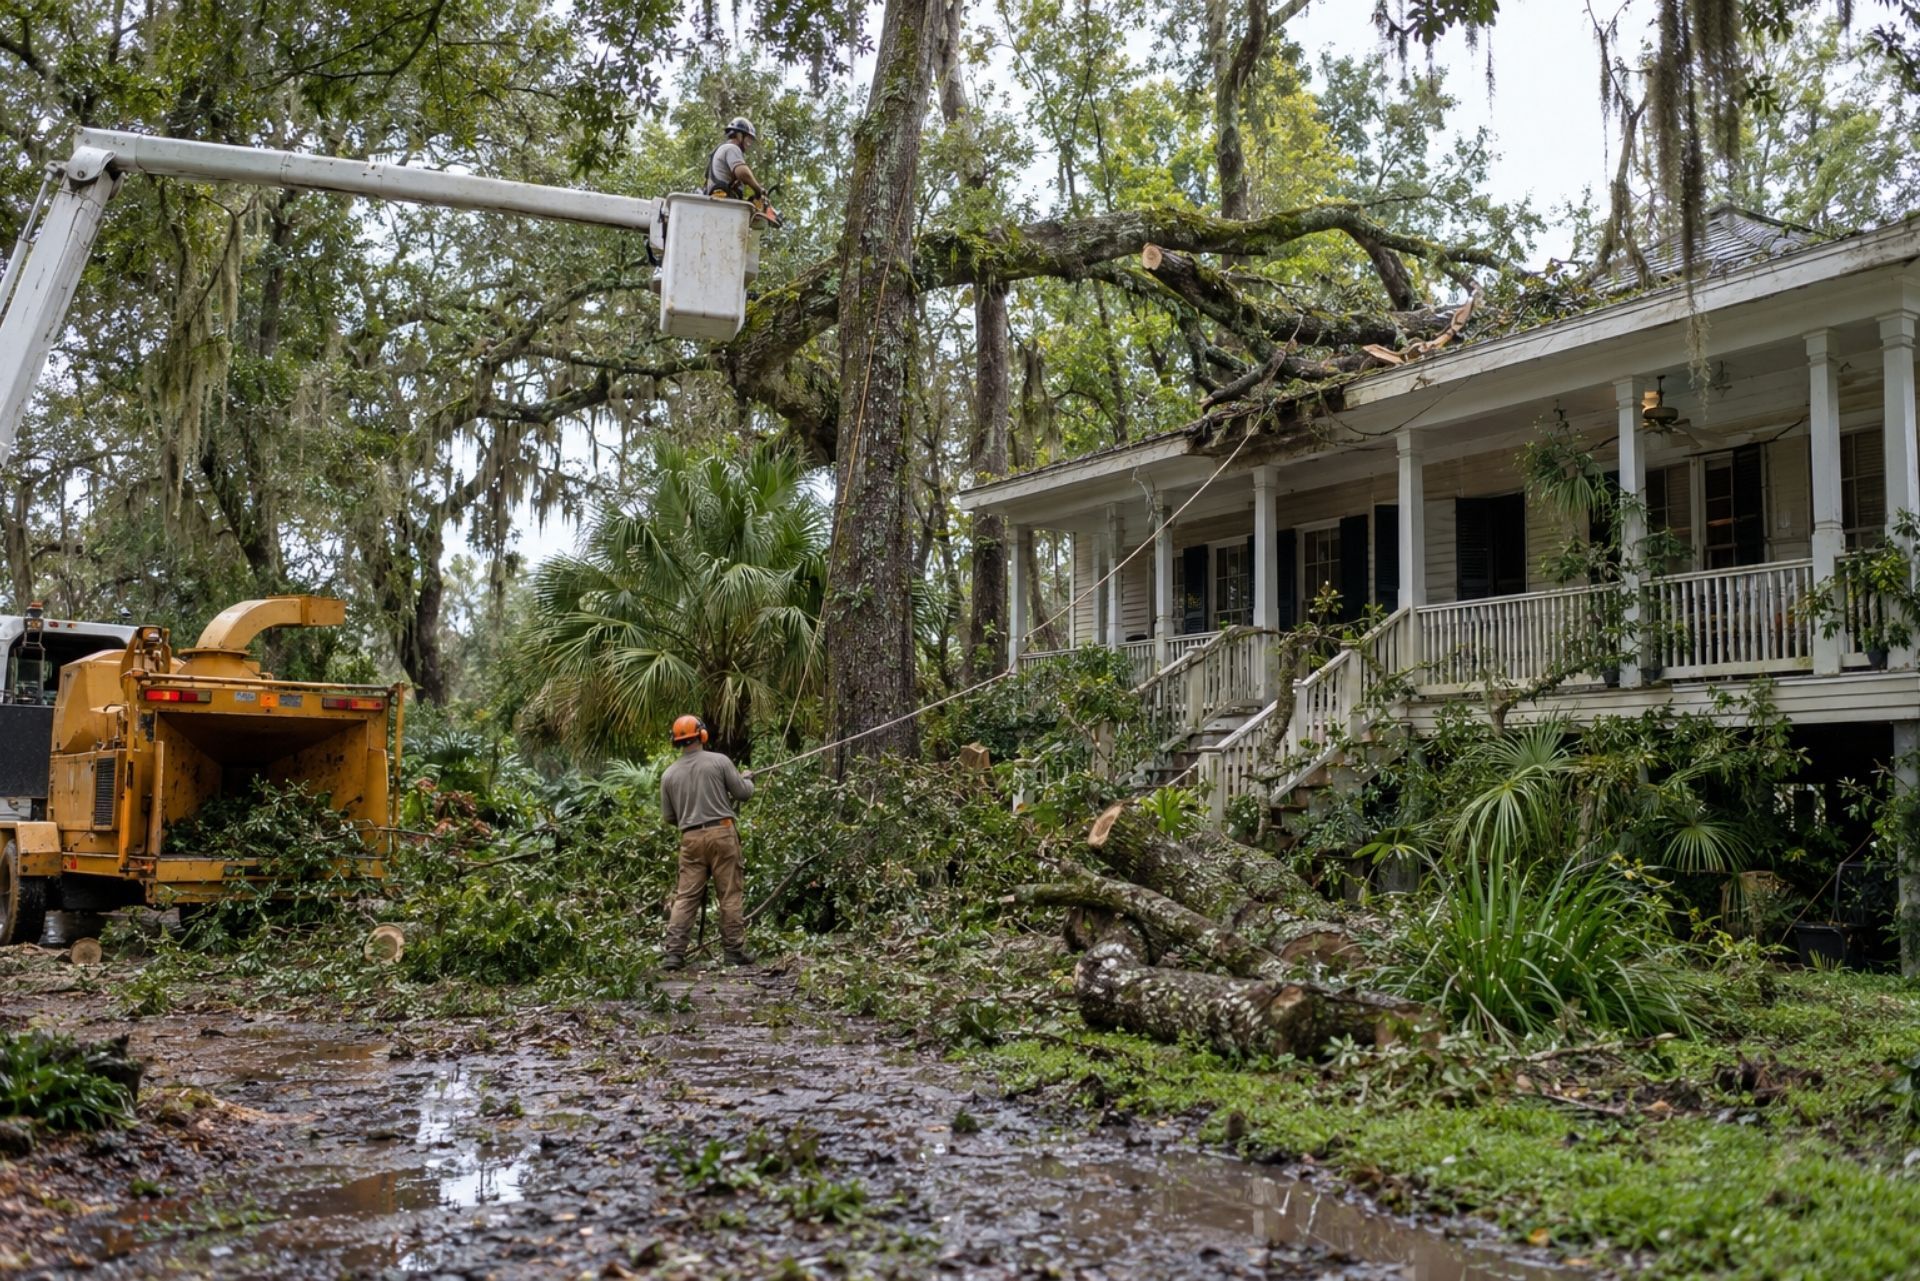
Picture a Slidell crew three days after a hurricane. There's a 60-foot water oak split across a homeowner's roof, a bucket truck parked on soft ground, and a phone that won't stop ringing. That week can make a tree service's year. It can also end the business if one claim lands on the wrong policy. This guide covers the felling and struck-by risks that drive underwriting, the liability that follows a tree on a house after a storm, crane and bucket truck exposure, and why comp is the line carriers resist most.

Risk Management for Felling and Struck-By Injuries

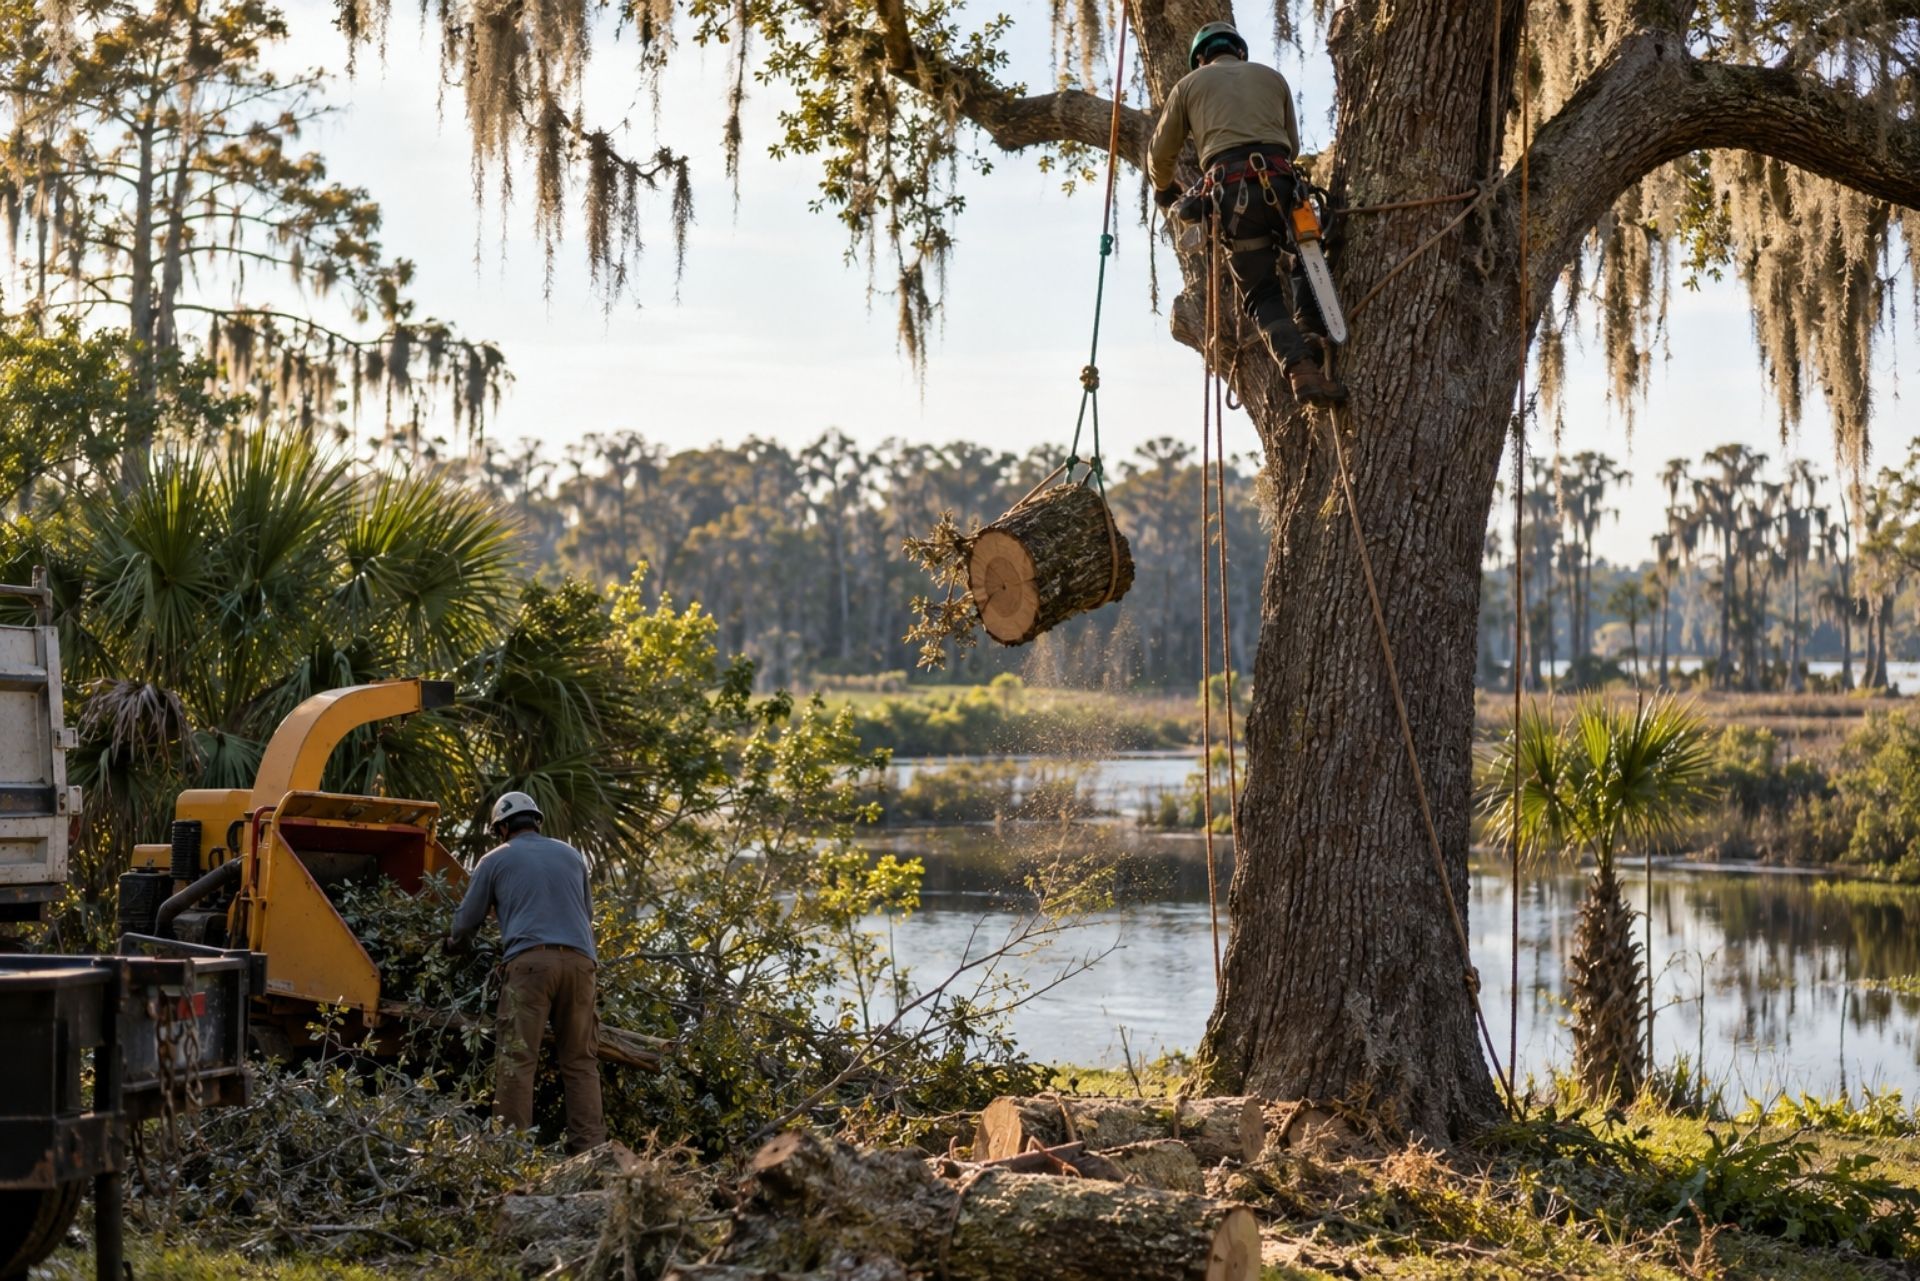
Struck-by incidents are the defining hazard of this trade. Workers are hit by falling limbs, kickback, rolling logs, or a trunk that barber-chairs off the stump. OSHA identifies struck-by hazards as the leading cause of injury and death for tree care workers, with 99 fatalities recorded nationally in a single year. Underwriters know these numbers well, and they price your account against them.


The wider occupation group looks just as rough. Grounds maintenance workers, including trimmers, face a fatality rate of 20.9 per 100,000 full-time workers. That is more than six times the national average. When a carrier reviews your application, it is really asking one question: what makes your crew different from those numbers?


You can answer that question with documented practices like these:


  • Written drop zones and a clear communication system between the climber and the ground crew
  • Chainsaw PPE logs, including chaps, helmets, and eye and ear protection, checked daily
  • Felling plans with escape routes noted before the first cut
  • Tailgate safety meetings recorded with dates and signatures


Paperwork won't stop a falling limb. It does give underwriters a reason to quote your account instead of declining it.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Liability and Trees on Houses After Hurricanes

After a storm, the work changes. You're no longer felling a healthy pine in an open lot. You're lifting a waterlogged, partially failed trunk off a damaged roof, with the homeowner's insurance adjuster watching and power lines sometimes still nearby. If a section drops and punches through the ceiling, that new damage is yours. General liability typically responds to property damage you cause to the customer's home. It may exclude damage to the specific part of the property you were working on, so read the "care, custody, or control" and "your work" wording closely.


A common mistake we see is a contractor who assumes the homeowner's policy will cover everything because the hurricane caused the original problem. That may hold for the first impact. Damage from your rigging, your crane pick, or a dropped section typically becomes a liability claim against you.


Homeowner pressure on tree maintenance is rising too. Residents in New Orleans have faced insurance cancellations over overhanging limbs and maintenance delays. That means more preventive trimming work for you, and more customers who will ask for your certificate of insurance before you start.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Crane and Bucket Truck Exposure in Louisiana Operations

Aerial equipment raises both your productivity and your risk. A bucket truck tipping on saturated Northshore soil, a boom contacting a line, or a crane dropping a pick onto a car can produce six-figure claims. Each of those losses may fall under a different policy, which is why coverage gaps tend to appear here.

Commercial Auto vs. Inland Marine

Your bucket truck is a vehicle on the road and a tool on the job. Commercial auto typically covers it while driving and may cover some operational use. Inland marine covers the equipment itself, such as chippers, stump grinders, and aerial lifts, against theft or physical damage. For a typical arborist setup in 2026, inland marine averages between $50 and $80 per month. That is small next to the cost of replacing a stolen chipper.

Crane Work and Rigging

If you own or rent a crane, tell your agent. Many general liability forms limit or exclude crane operations, and some carriers require a separate rigging or riggers liability endorsement for damage to property you're lifting. Subcontracting the crane? Get the operator's certificate and confirm you're named as an additional insured. Don't assume either one is in place.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Why Workers Comp Is the Hardest Line to Place

This is the policy that keeps tree service owners up at night. Many standard carriers won't write tree trimming classifications at all. Those that do typically require loss runs, safety programs, and detailed breakdowns of climbing versus ground payroll. Pricing reflects that. A Louisiana crew with $200,000 in annual payroll typically pays between $14,000 and $26,000 for workers' comp.


Rates also move. The NCCI filed advisory prospective loss costs for Louisiana with an anticipated effective date of May 1, 2026. Changes like this may shift your renewal even if your crew had a clean year.


Going without coverage is no longer realistic. Louisiana House Bill 81 (2026) lets landowners have a neighbor's encroaching branches trimmed by a licensed arborist after 30 days' written notice. The law requires that arborist to carry both general liability and workers' compensation. Starting July 2026, the Louisiana Department of Agriculture and Forestry requires licensed arborists to show proof of current GL and comp. No comp policy means no license, and no license means no work.

How Jones Act Exposure Differs From State Workers Comp

Comparing Essential Coverages for Tree Care Professionals

Here is how the core policies typically divide up the risk on a tree job:

Coverage What It Typically Covers Common Gap
General Liability Damage to client property, third-party injury May exclude crane work or "your work" area
Workers' Comp Employee injuries, lost wages Misclassified payroll leads to audit bills
Commercial Auto Trucks on the road, liability Equipment mounted on the truck
Inland Marine Chippers, grinders, aerial lifts Wear and tear, mechanical breakdown
Umbrella Extra limits above GL and auto Usually won't extend coverage beyond the underlying policies

Use the table as a starting point. Policy language varies by carrier, and the exclusions decide what actually gets paid.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Frequently Asked Questions About Tree Service Insurance

Do I need workers' comp if it's just me and one helper? If you have an employee and want to hold an arborist license in Louisiana, yes. State licensing now requires proof of comp.


Will my general liability cover a tree I drop on a house? It typically covers damage you cause to the customer's property. Some forms limit coverage for crane work or for the specific area you were working on.


Why did my workers' comp quote come back so high? Tree trimming classifications carry high injury rates. Your rate also depends on payroll, how that payroll is split between climbing and ground work, and your claims history.


Can I use 1099 subcontractors to avoid comp costs? Uninsured subs can end up being treated as your employees at audit. Always collect their certificates of insurance.


Does insurance cover my bucket truck if it tips over on a job? Physical damage may fall under commercial auto or inland marine, depending on how the policies are written. Confirm this with your agent before storm season.


How fast can I get a certificate of insurance after a hurricane? Once your coverage is bound, an agent can typically issue certificates quickly. Have your policies in place before storm season so you're not waiting on them.

Making the Right Choice for Your Louisiana Business

Struck-by injuries drive your comp rates. Post-hurricane jobs test your liability wording. Aerial equipment creates gaps between your auto and inland marine policies. And with HB 81 and the new LDAF requirements, comp has become a condition of doing business. Insurance for a Louisiana tree service only works when these policies fit together, with no space between them for a claim to fall through.


Aubert Insurance Agency has served St. Tammany Parish since 1910. As an independent agency, we compare multiple carriers in one place, which matters for a hard-to-place line like tree care comp. We'll also walk you through your exclusions so you know what you're signing. The process is simple: start online, we shop for you, and you pick the plan that fits.


Hurricane season won't wait for your paperwork. Start a Quote today from Covington or Slidell, and get your crew covered before the next storm.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
