













Louisiana Boat Insurance

Dwelling coverage rebuilds the house itself. Other structures coverage handles the detached garage, the fence, the shed and the pool house, usually at ten percent of the dwelling limit.

Covington & Slidell Independent Insurance Agents

Your house and other structures

Personal property covers furniture, clothing, tools and electronics. Jewellery, firearms and silver carry low internal caps, so we schedule those items separately when they are worth more than the cap.

Your belongings

Picture a Saturday in late August. Your 24-foot bay boat is tied up behind the house on the Tchefuncte, the redfish were biting near the Rigolets that morning, and by Sunday night the National Hurricane Center has a cone pointed straight at St. Tammany Parish. Owners who planned ahead already know where their boat is going and who pays for it. Everyone else is calling marinas that stopped answering hours ago.


Boating here is different from boating almost anywhere else in the country. We run brackish lakes, tidal rivers, marsh passes and open Gulf water, sometimes all in the same weekend. A policy written for a quiet freshwater lake in the Midwest doesn't fit that pattern, and the gaps usually show up at the worst possible moment.


There's some good news for 2026. After a rough stretch of rising premiums, the Louisiana Department of Insurance reported that boat insurance rates dropped between 4% and 11% in the first half of the year following legislative reforms. Lower rates only help if the policy actually covers how and where you boat, so here's how to check that.

Louisiana Boat Insurance: Protecting Your Vessel from the Tchefuncte to the Gulf

Louisiana boat insurance protects bay boats, offshore rigs, pontoons and other watercraft against liability claims, physical damage, theft and regional risks like hurricanes and named storms. Aubert Insurance Agency has helped families in Covington and Slidell protect what matters to them since 1910, and compares several carriers to fit coverage to how you use the water.


Louisiana law doesn't require boat insurance. In practice, though, most owners need it anyway. If you financed the boat, your lender will almost certainly require physical damage coverage, and most marinas around Lake Pontchartrain won't rent you a slip without proof of liability coverage.


The more useful question is what kind of coverage you need. A policy is a legally binding contract, and the exclusions matter as much as the limits. That's why it's worth reading the declarations page with someone who can explain each line before you sign, instead of finding the fine print after a claim.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Coverage for Bay Boats, Offshore Rigs, and Lake Pontchartrain Pontoons

Each type of boat carries its own risk, and a good policy reflects that.


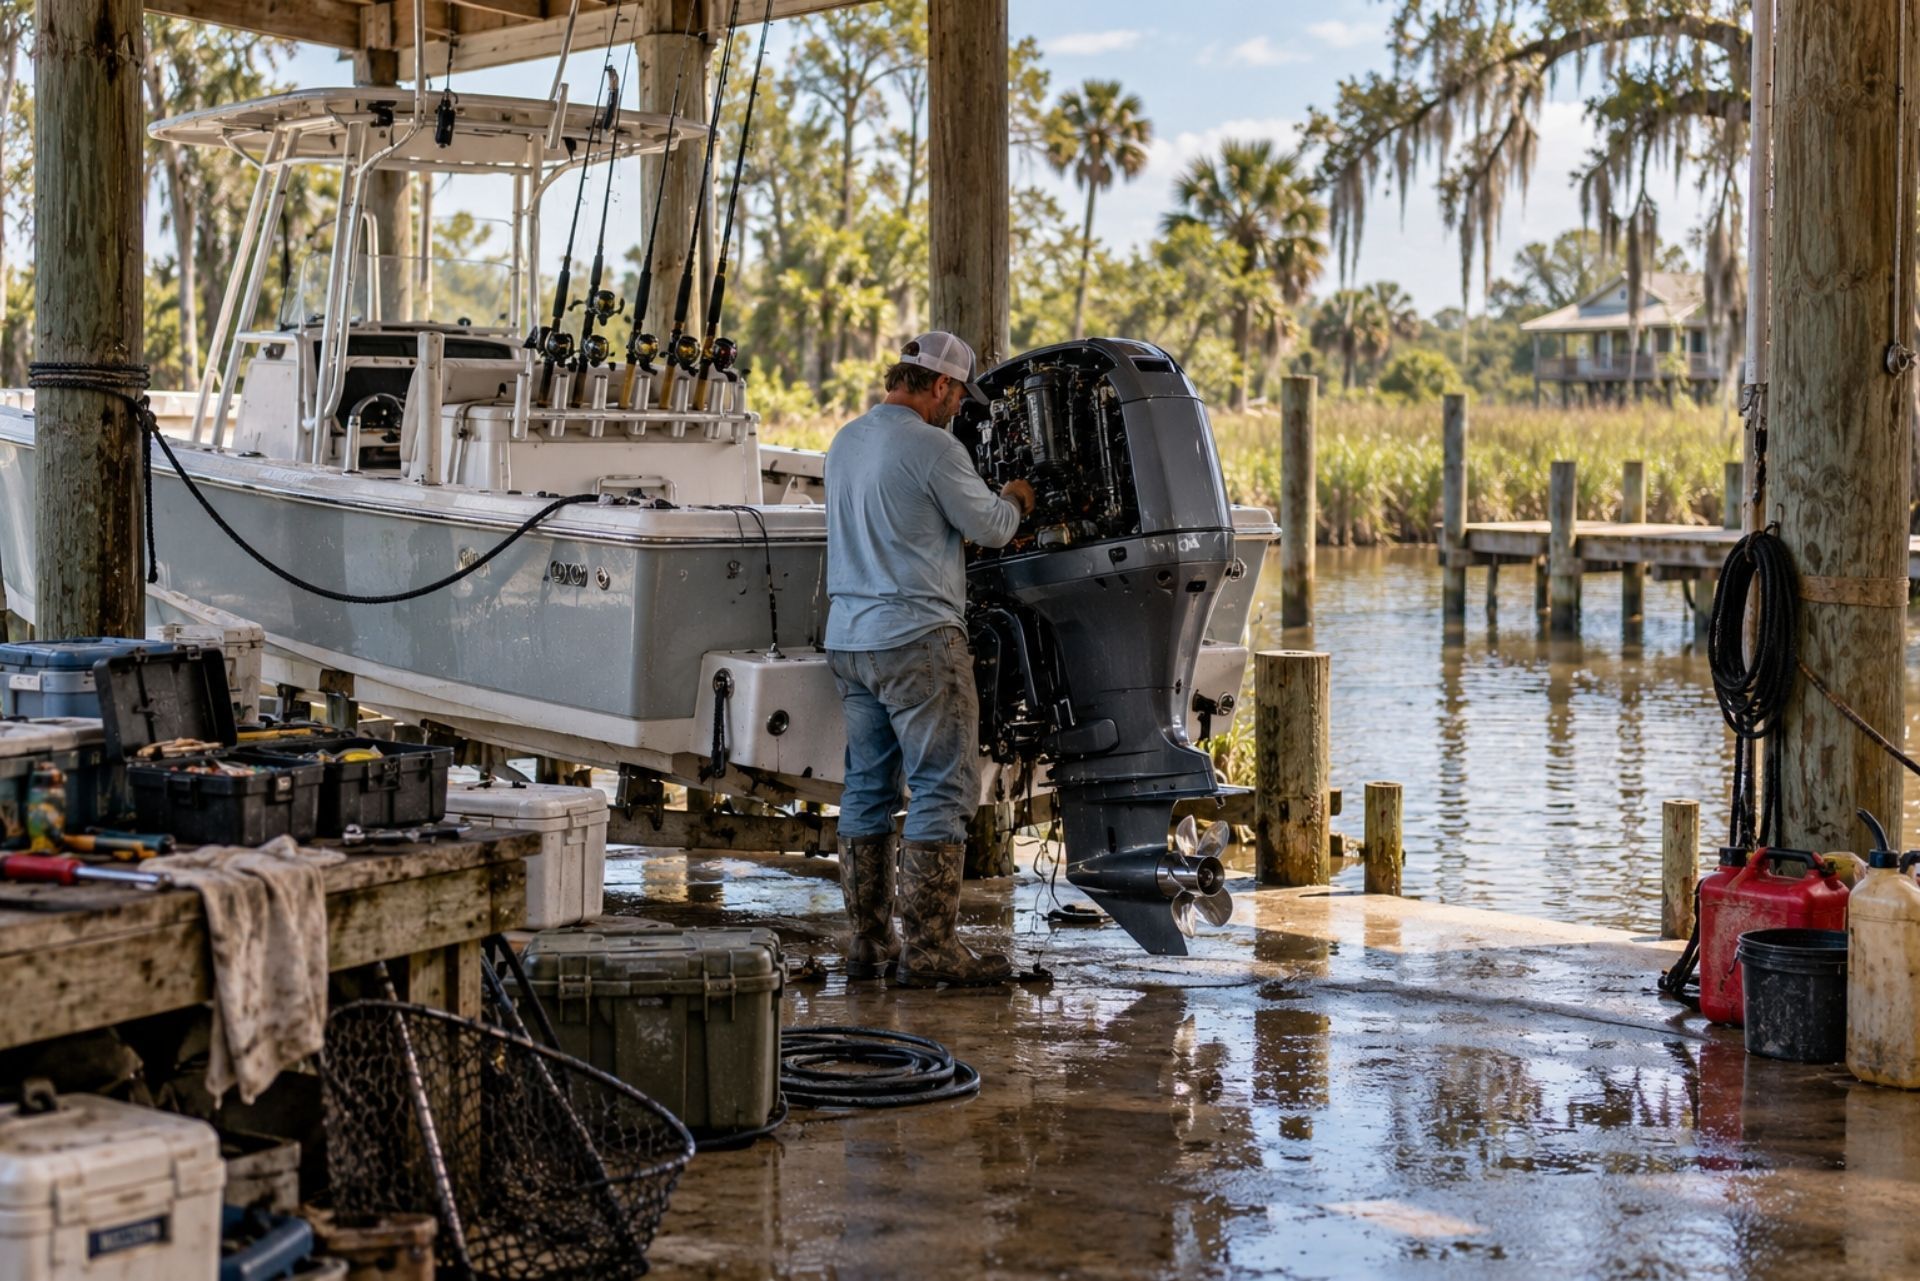
Bay boats are the workhorses of St. Tammany. They run shallow flats, oyster reefs and marsh cuts where submerged pilings and stumps damage lower units every season. Ask whether your policy treats grounding and lower unit damage as a covered accident or excludes it as wear and tear. That single distinction can decide whether a $6,000 repair is your problem or the carrier's.


Offshore rigs, the center consoles with twin or triple outboards that run past the barrier islands, raise different questions. Many policies set navigational limits, and some may restrict how far offshore you can go or require a minimum crew. If you chase tuna at the rigs, confirm your territory in writing.


Pontoons on Lake Pontchartrain tend to carry lower risk, and cost data shows pontoons on inland waters typically run $250 to $650 a year to insure. The lake can still get rough fast, though, and pontoons often carry the most passengers. That makes liability limits more important than many owners assume.

Understanding Agreed Value vs. Actual Cash Value

This is the most common mistake we see. An Actual Cash Value policy pays what the boat was worth at the time of loss, after depreciation. A 5-year-old pontoon that cost $30,000 new might settle for around $18,000 under ACV, which leaves a big gap if you want to replace it.


Agreed Value locks in a payout amount when the policy starts. It typically costs 10% to 20% more in premium, but for a newer boat or one with a loan balance, that extra cost usually makes sense.

Who Needs Home Insurance in Louisiana

Comparing Boat Insurance Coverage Options

Many boaters buy the bare minimum to satisfy a marina, then find out after a claim what the policy left out. This side-by-side comparison shows how a liability-only policy typically differs from a comprehensive package. Specific features vary by carrier, so treat it as a starting point.

Feature Basic Liability Comprehensive Coverage
Bodily injury to others Yes Yes
Damage to other boats/docks Yes Yes
Damage to your own boat No Yes (ACV or Agreed Value)
Theft of boat, motor, trailer No Typically included
Medical payments for passengers Usually not Typically included
Wreckage removal Rarely Often included or available
Fuel spill liability Sometimes Typically included
Personal effects and fishing gear No Often available as an add-on
On-water towing and assistance No Often available
Named storm haul-out cost sharing No May be available

The bottom rows deserve a close look. Gear on a serious bay boat, including rods, reels, electronics and a trolling motor, can easily add up to five figures. A basic policy won't cover any of it.


Wreckage removal and medical payments rarely get attention until something goes wrong. After that, they're usually the two coverages people wish they had bought.

Gaps Worth Knowing About

Managing Named Storm Haul-Out Plans in Louisiana

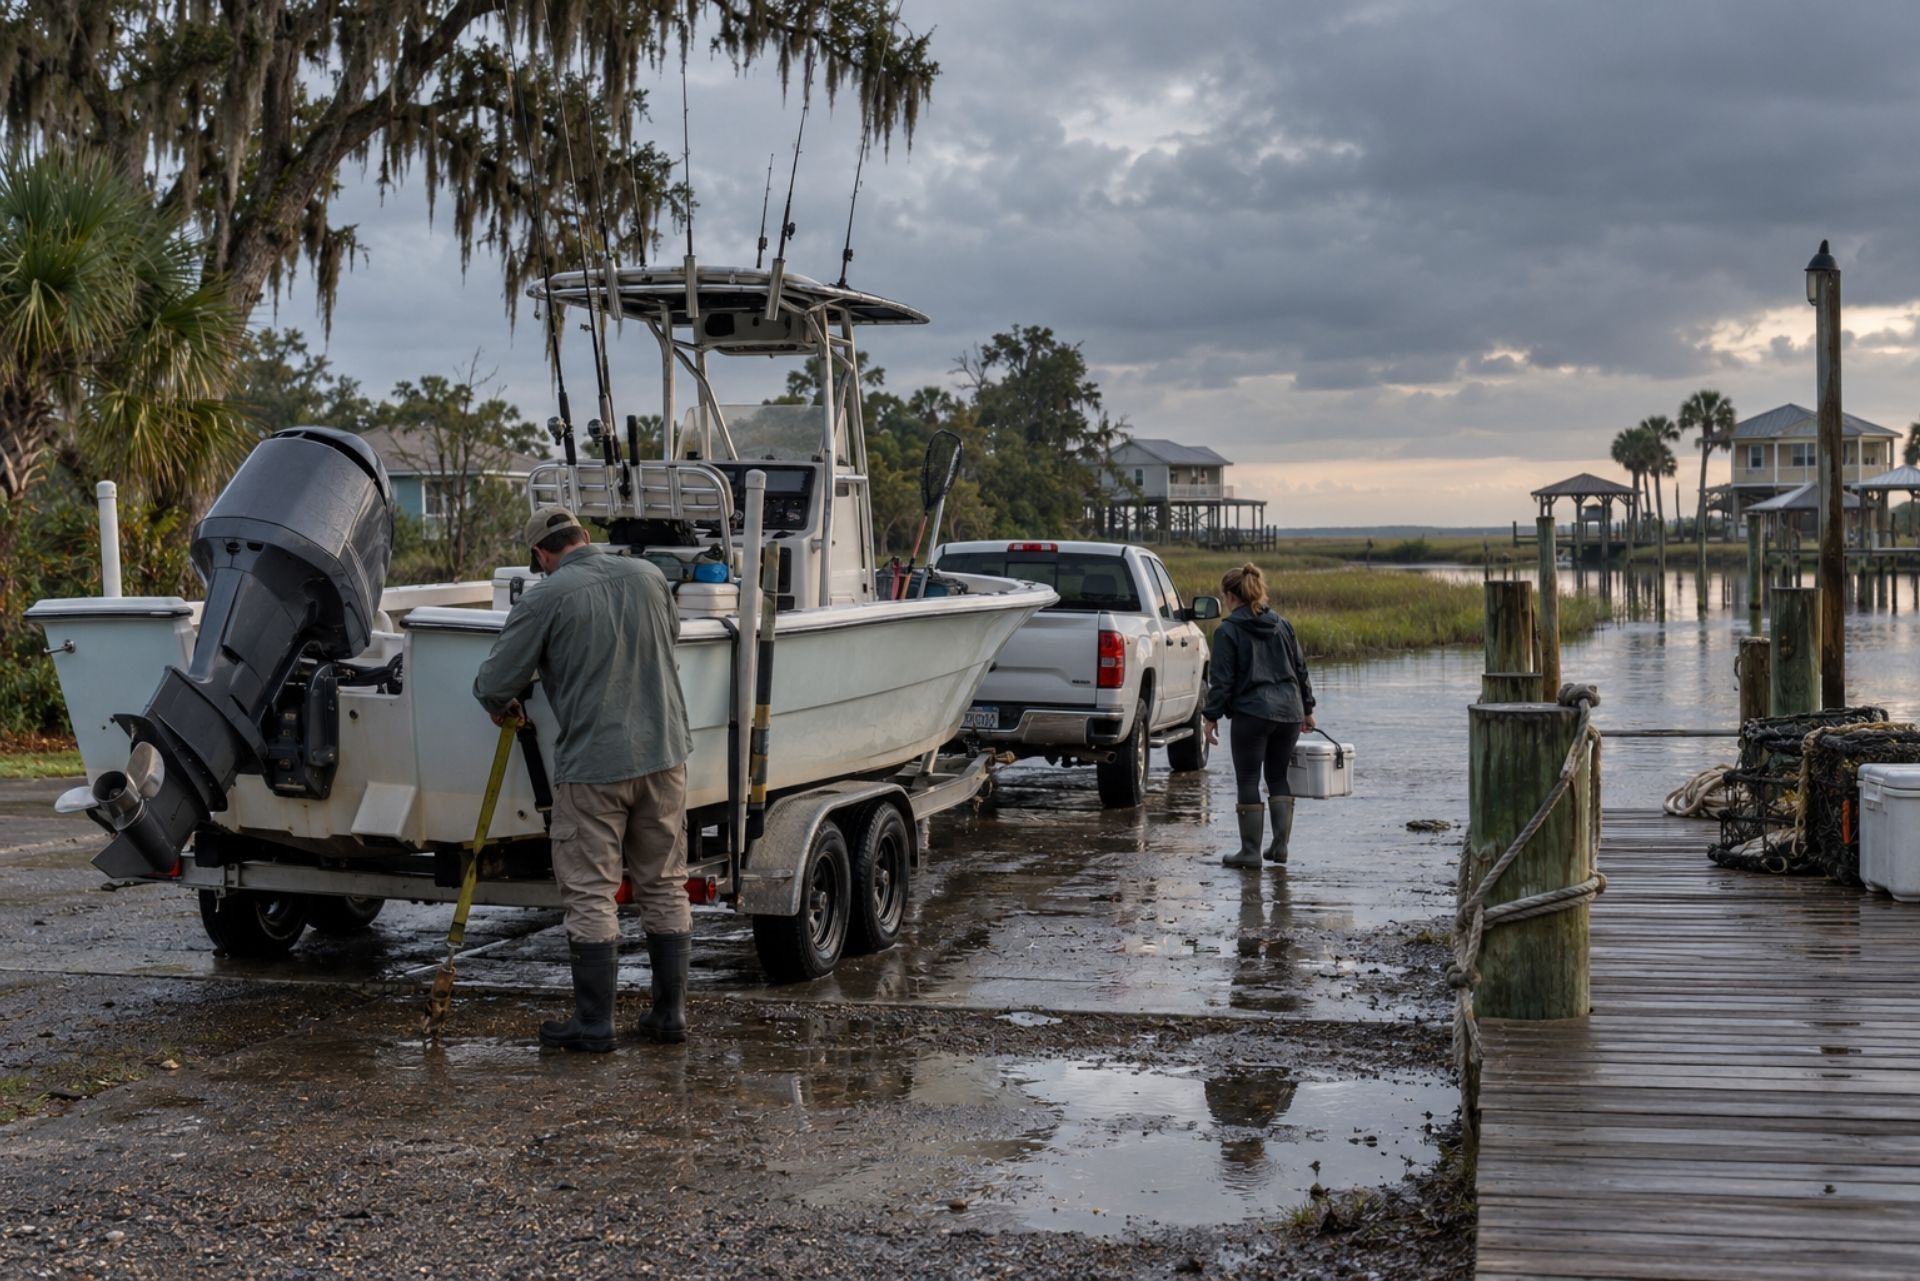
If you keep a boat in St. Tammany, plan to deal with at least one hurricane watch every few seasons. Many carriers that write boats in coastal Louisiana may ask for a written named storm plan, and some may reduce your coverage or raise your deductible if you don't follow it.


A workable plan answers four questions:


  1. Where will the boat go? Name a specific location: a dry stack facility, an inland storage yard, or your own property well above surge elevation.
  2. Who will move it? If you travel for work, list a backup person who can tow or haul the boat.
  3. When will you act? Many plans trigger at a hurricane watch, not a warning. Haul-out lines get long fast.
  4. How will you secure it? Strap it down, remove canvas and electronics, and take photos once it's secured.


Some policies may help pay for an emergency haul-out, often reimbursing part of the cost when a named storm threatens. That matters more than it sounds. In 2026, a basic haul and launch service runs roughly $300 to $500 for a 25-foot boat and $600 to $950 for a 40-foot boat. During an active storm season, that can add up.


Ask about named storm deductibles separately. Some carriers may apply a percentage-based deductible to storm losses instead of the flat deductible on your declarations page.

Liability on the Water and Wreckage Removal

Physical damage coverage protects your boat. Liability coverage protects your savings, and on crowded weekends near the Madisonville bridge, it's the coverage most likely to matter.


Consider some common scenarios. Your wake swamps a kayaker on the Tchefuncte. A guest slips boarding at the Slidell marina and breaks a wrist. You misjudge your approach and crunch a neighbor's boathouse. Each one can bring a claim for medical bills, property damage or a lawsuit, and minimum limits may not stretch far enough. Plenty of boat owners carry $300,000 or more, and many add a personal umbrella policy on top.


Wreckage removal is one of the less obvious gaps. If your boat sinks after a storm or collision, state and federal authorities can require you to remove it, especially if it blocks a channel or leaks fuel. Raising and hauling a sunken vessel can cost more than the boat was worth. Some policies may cover removal in addition to the hull limit, while others count it against the hull limit. That difference can leave you paying out of pocket after a total loss.


Fuel spill liability belongs in the same conversation. A ruptured tank in a marsh can trigger cleanup costs under federal pollution rules. Confirm that your policy addresses it.

Gaps Worth Knowing About

Frequently Asked Questions About Louisiana Boat Insurance

Do I legally need boat insurance in Louisiana? No, the state doesn't require it. Most lenders and marinas do, though, so most owners end up needing it anyway.


Does my homeowners policy cover my boat? Usually only small boats, and with low limits. A bay boat, offshore rig or pontoon typically needs its own policy.


Is Agreed Value worth the extra cost? For newer or financed boats, usually yes. It avoids depreciation surprises when you file a claim for a total loss.


What if I don't follow my hurricane plan? Your carrier may reduce or deny a storm claim. Write a realistic plan and stick to it.


Are my fishing rods and electronics covered? Not always. Many policies cover them only through a personal effects add-on, so ask before you assume.


Are boat rates going down in 2026? Many are. Louisiana regulators say policyholders should shop around to take advantage of rate decreases.

Making the Right Choice for Your Vessel

The right boat policy matches the boat you own, the water you run and the storms you're likely to face. For most St. Tammany owners, that means confirming your navigation territory, choosing Agreed Value when the numbers support it, setting liability limits high enough for a full pontoon, and writing a named storm plan you can actually carry out in August.


With rates easing across the state this year, it's a good time to compare. Your current carrier may not offer you the improved pricing unless you ask, and the next carrier may handle storm deductibles or wreckage removal very differently.


Aubert Insurance Agency has served Covington and Slidell since 1910 and has seen plenty of storm seasons come and go. As an independent agency, we compare coverage from several carriers and explain what each policy includes and excludes before you commit. Ready to see your options? Start a Quote today and get on the water knowing exactly what your policy covers.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
