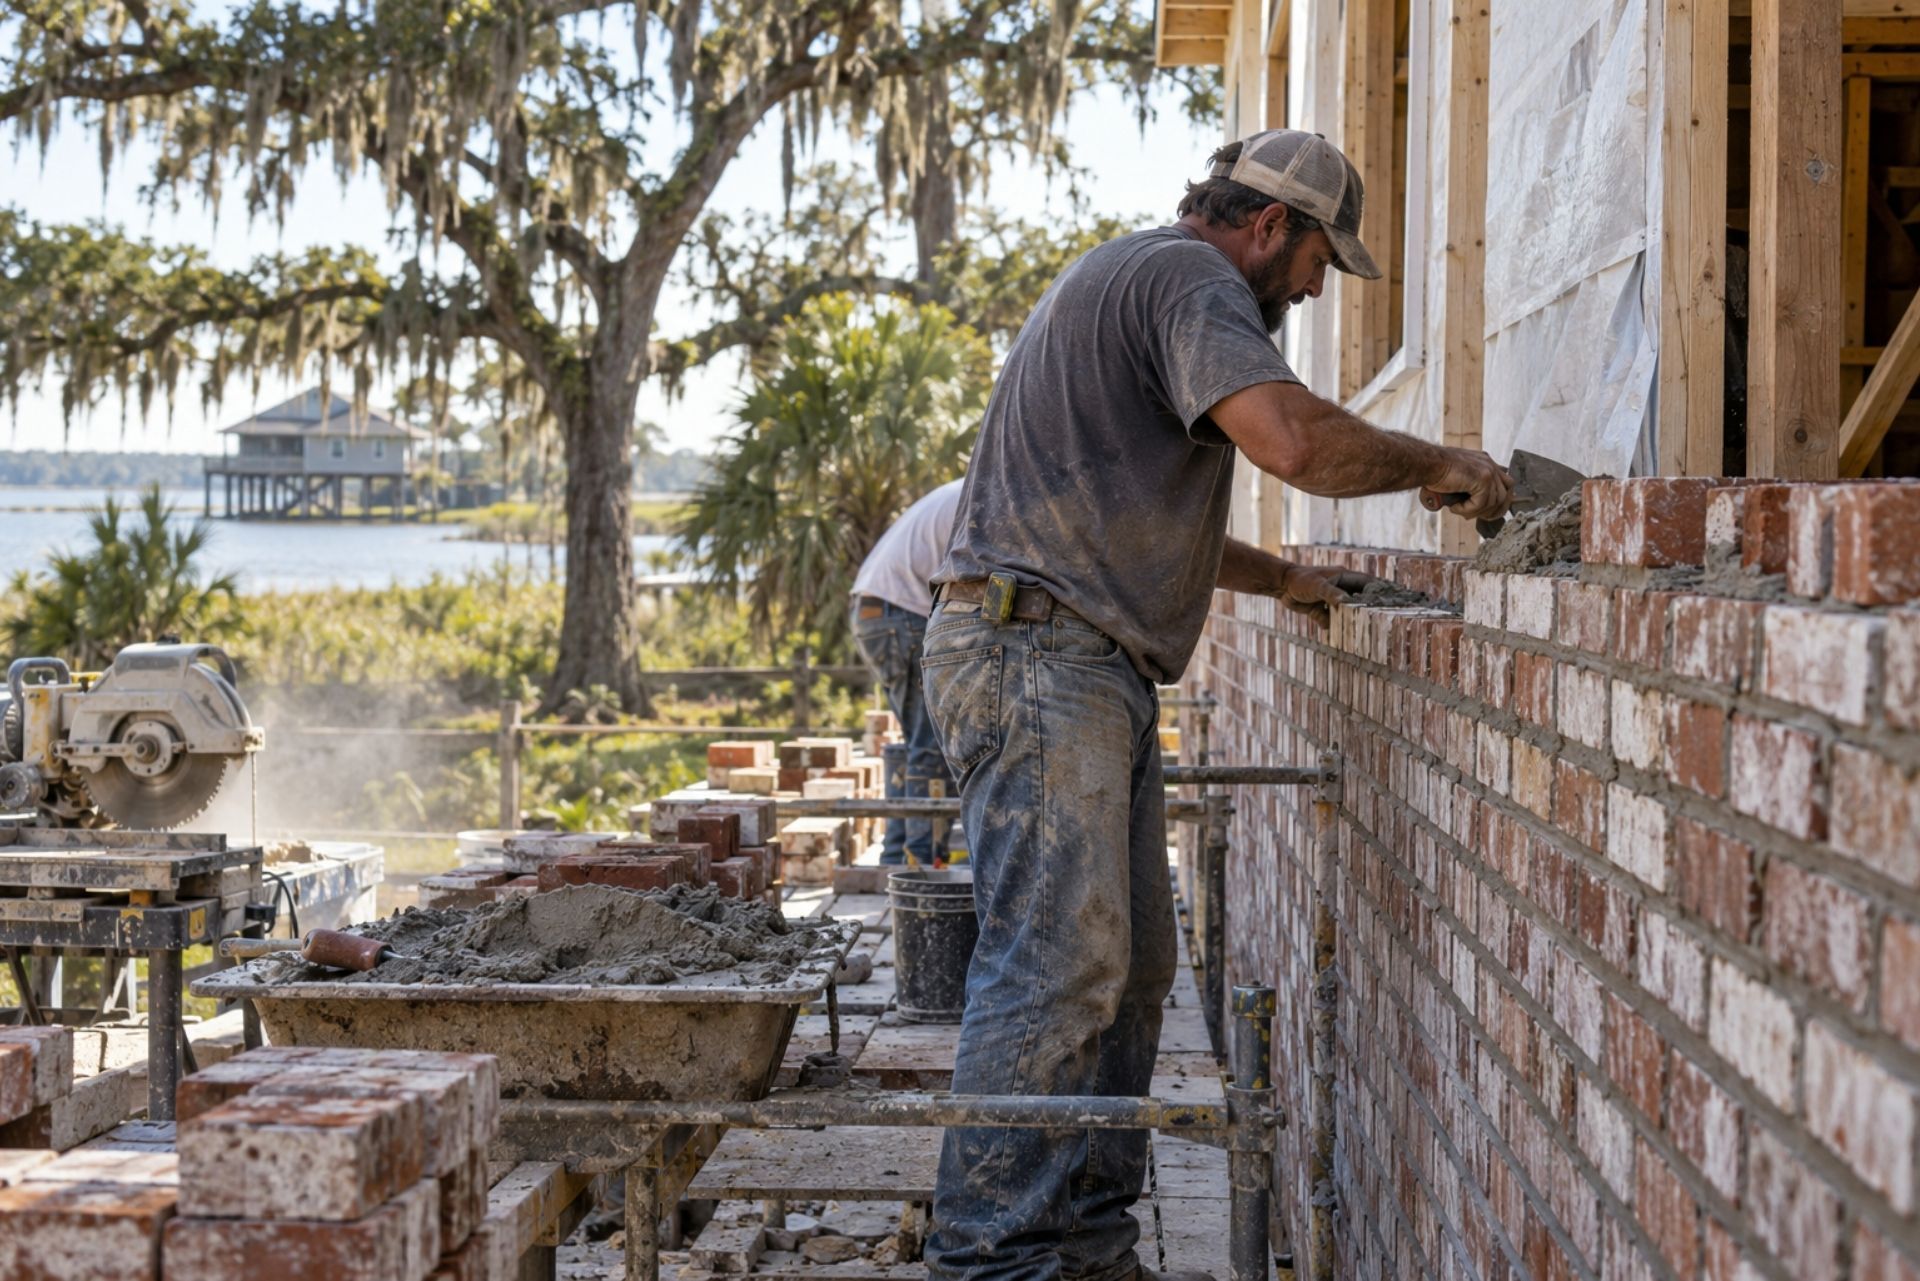
Louisiana Masonry Contractor Insurance

Most policies split protection into three core pieces:


  • Building: The structure itself, plus permanently attached fixtures. This may include signage, parking lot lighting, and fencing if they are listed or covered by endorsement.
  • Contents (Business Personal Property): Equipment, inventory, computers, and furniture. Contents matter most for businesses whose expensive equipment sits close to the ground. A car wash is a good example: its high-value machinery is often at ground level, which makes it more exposed to wind-driven damage and flooding.
  • Business Income: Replaces lost profits and pays continuing expenses like payroll and rent while you are shut down for repairs.


One common mistake is setting the business income limit too low. Rebuilding after a major Louisiana hurricane can take far longer than owners expect, because contractors and materials are stretched thin across the region.

Covington & Slidell Independent Insurance Agents

Buildings, Contents, and Business Income
Picture a summer ride across the Lake Pontchartrain Causeway or down Highway 190 through Covington. The bike is tuned, the weather is perfect, and then a distracted driver drifts into your lane. In that moment, the policy you picked months ago decides whether you recover financially or spend years paying off a crash you didn't cause.


This guide covers Louisiana motorcycle insurance from the ground up: the legal minimums, the helmet rules, and the optional coverages that matter most to St. Tammany Parish riders.

Protecting Your Louisiana Masonry Business

Louisiana masonry contractor insurance typically combines general liability, workers compensation, and inland marine coverage to protect against the risks this trade faces here: scaffold failures, falling brick, silica exposure, and water damage claims after the job ends. Aubert Insurance Agency has helped contractors in Covington and Slidell build that protection since 1910.


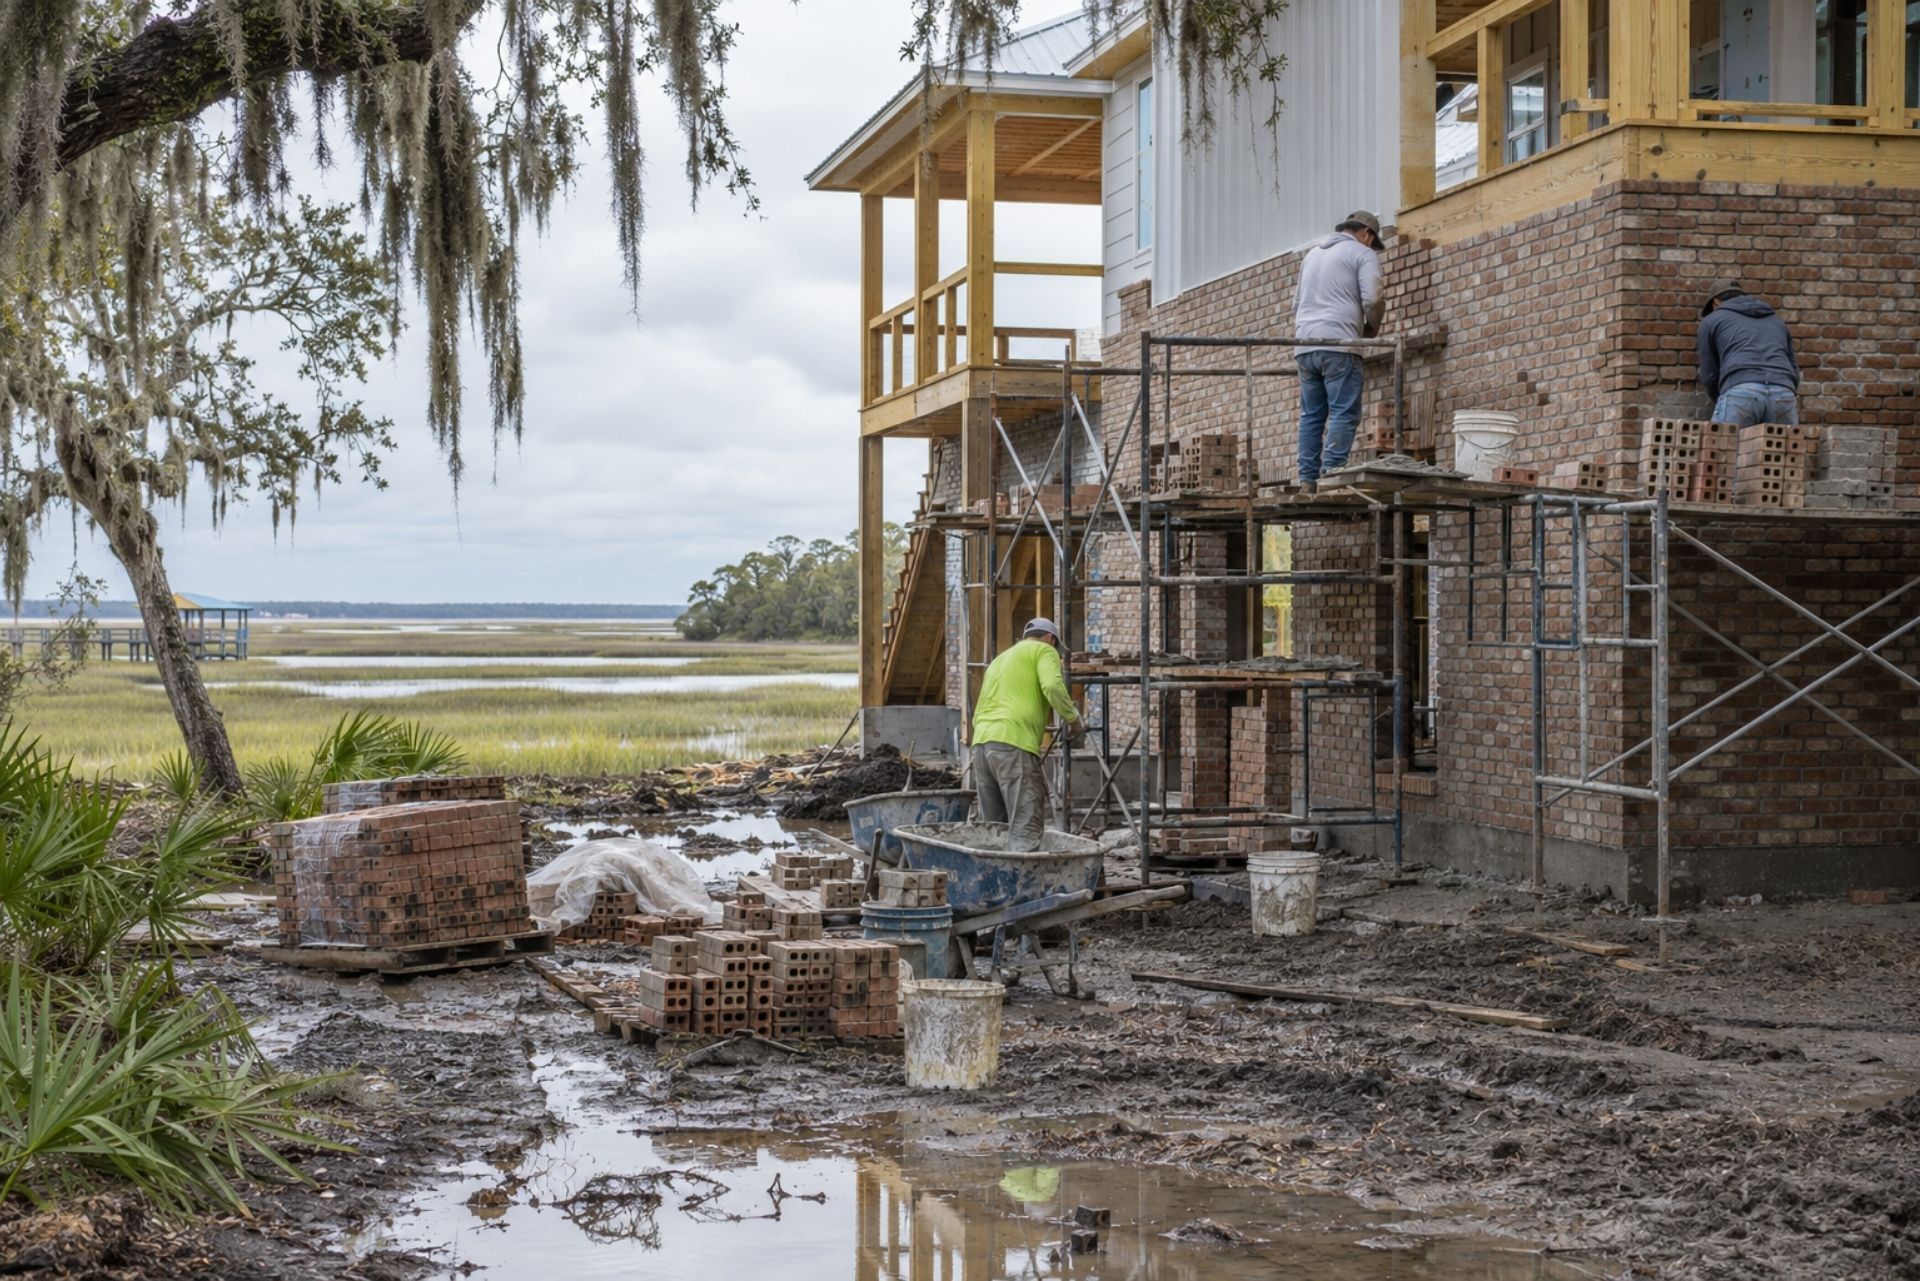
Masonry work in St. Tammany Parish looks different from masonry work in drier states. You're laying brick in heavy humidity, working on soft soils, hauling pallets of block down roads that flood in a summer storm, and finishing walls that will spend decades absorbing Gulf Coast rain. Each of those conditions creates a specific type of claim, and a generic contractor policy doesn't always line up with them.


The regulatory side changed this year too. Starting August 1, 2026, under Act 757, Louisiana residential and home improvement contractors must carry at least $500,000 in general liability insurance, up from the old $100,000 minimum. The LSLBC also requires policies to carry no exclusions for your licensed scope of work, with license suspension as the penalty. Contractors must list the LSLBC as certificate holder and keep coverage in force for at least six months. That exclusion rule matters for masons, because some carriers write policies that quietly carve out height work or certain structural tasks.


For a sense of cost, general liability for small Louisiana masonry crews of 2 to 5 employees in late 2026 typically runs between $1,300 and $3,800 a year, depending on payroll, claims history, and the type of work you take on.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Managing Scaffold Collapse and Falling Material Risks

Scaffolding is where masonry jobs most often turn into lawsuits. A crew stacks too much brick on a plank, a mudsill sinks into wet ground after an afternoon downpour, or a tie-in pulls loose. When it fails, you can be facing an injured worker, a damaged neighboring property, and a passerby hit by debris, all from the same incident.


Unbraced walls are their own hazard. Under OSHA's masonry construction standard, walls over 8 feet in height must be adequately braced to prevent overturning or collapse until permanent supports are in place. A strong wind off Lake Pontchartrain can push over a fresh, unbraced wall in seconds. If that wall lands on a parked car or a homeowner's carport, your general liability policy is typically the coverage that responds.


Here's how claims from one scaffold event usually split up:


  • Injured employee: workers compensation pays medical bills and lost wages
  • Injured visitor or subcontractor's worker: general liability may respond, subject to contract terms
  • Damaged scaffold equipment: inland marine or contractor's equipment coverage
  • Damaged building or neighbor's property: general liability, minus any applicable exclusions


One common mistake we see: masons assume a general contractor's policy will cover them on site. It often won't. Review the indemnity language in your subcontract before you mobilize.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Cutting brick, block, and stone releases respirable crystalline silica, and federal inspectors pay close attention to this trade. Masonry contractors are the second most-cited group for silica standard violations, trailing only fall protection. Citations cost money on their own, but the bigger exposure is what comes years later.


Silicosis and related lung diseases develop slowly. An employee who ran a dry-cut saw for your company in 2026 may file a claim long after the work ended. Those claims typically land under workers compensation as occupational disease, and carriers look closely at whether you followed the rules: wet cutting or vacuum dust collection, respirators where required, a written exposure control plan, and medical surveillance for workers above the action level.


Third-party exposure is a separate problem. If silica dust drifts onto a neighboring business or into an occupied home during a renovation, someone may claim health or property damage. Many general liability policies include pollution exclusions that may limit coverage for dust claims, so read that language carefully.


Compliance isn't only about avoiding fines. Documented controls are your strongest evidence when a claim gets disputed, and they can help with underwriting when you shop for renewal.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Brick Veneer Water Intrusion Claims in Louisiana

Water intrusion is the claim that shows up after you've been paid and moved on. Louisiana gets intense rainfall, and the humidity rarely lets walls dry out completely. If weep holes are blocked with mortar droppings, flashing is lapped wrong, or the air gap behind the veneer is bridged, water gets trapped against the sheathing. A year or two later, the homeowner finds rotted framing, mold, and stained drywall.


These claims are expensive because the damage is hidden and the repair means tearing off veneer. The homeowner, builder, or HOA may name every trade on the job, and the mason usually gets the first call.


This is why completed operations coverage matters. It's typically part of a general liability policy and responds to property damage arising from your finished work. A few things to check with your agent:


  1. Does your aggregate limit for products and completed operations match the size of the homes you build?
  2. Are there exclusions for mold, fungi, or "your work" that could gut coverage?
  3. Will your policy respond if a claim is filed after you switch carriers?


Good documentation helps too. Photograph flashing, weeps, and drainage mat before the veneer goes up. Those pictures may end a dispute before it reaches a lawyer.

Hauling Heavy Material on Trailers: Auto and Cargo Needs

A loaded trailer of brick, stone, or bagged mortar is some of the heaviest cargo any small contractor moves. That weight stresses brakes, tires, and hitches, and it makes stopping distances longer on wet roads like US-190 or I-12. A pallet shifting during a sudden stop can crush a tailgate, spill onto the highway, or cause a jackknife.


Know the limits before you load. The Louisiana DOTD 2026 weight limits are 80,000 lbs for Interstates and 88,000 lbs for non-Interstate state highways. For crews that regularly run heavy, an annual permit costing $400 allows a 10% weight variance when hauling finished masonry products or raw concrete inputs. Annual oversize/overweight permits now require a Registered Route approved through the LaGeaux system before each move.


On the insurance side, your commercial auto policy should list the tow vehicles and, depending on the carrier, may need the trailer scheduled as well. Liability typically follows the towing vehicle, but physical damage to the trailer itself may require separate coverage. The materials in the bed are another gap: inland marine or motor truck cargo coverage may protect brick and stone in transit, along with mixers, saws, and scaffolding.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Comparing Essential Masonry Coverage Options

Masons often ask whether they need professional liability. Most don't, unless they offer design or engineering advice. Here's how the core policies differ:

Feature General Liability Professional Liability Workers Compensation
Covers Third-party injury and property damage Errors in advice, design, or specs Employee injuries and illness
Masonry example Brick falls on a neighbor's car Faulty retaining wall design you drew Worker hurt in scaffold fall
Silica exposure May be limited by pollution exclusion Rarely applies Typically covers employee illness
Water intrusion Completed operations may respond Only if design caused it Not applicable
Required in Louisiana? Yes, $500,000 minimum for residential (Act 757) Usually not Yes, for most employers
Who needs it most Every masonry contractor Masons offering design services Any contractor with employees

The real value sits in how these fit together. A single bad day can trigger all three, and gaps between them are where contractors get hurt.

Common Questions About Masonry Insurance

Do I need insurance for my trailer if it is for business use?


Yes. Personal auto policies typically exclude or limit business use, so your trailer and tow vehicle should be on a commercial auto policy, with cargo or inland marine coverage for the materials.


Does general liability cover silica dust lawsuits?


Sometimes. Many policies include pollution exclusions that may restrict dust claims, so third-party silica coverage depends on your specific policy wording. Employee illness typically falls under workers compensation.


What happens if a brick falls and hits a car?


Your general liability policy typically pays for the vehicle damage and any injuries to people nearby, minus your deductible. If the brick fell off your moving trailer, commercial auto would respond instead.


Will my policy still cover a wall I built three years ago?


It may, if you carry completed operations coverage and the policy terms reach back to that work. Ask your agent how claims are handled if you've changed carriers since.


Can a policy exclusion affect my contractor license?


Yes. The LSLBC requires policies with no exclusions for your licensed scope of work, and an excluding policy can lead to license suspension.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Making the Right Choice for Your Crew

Masonry risk in Louisiana stacks up the same way your walls do: scaffold and falling material on the jobsite, silica exposure that surfaces years later, veneer water claims after closeout, and heavy loads on wet highways. Covering all four takes coordinated general liability, workers compensation, commercial auto, and inland marine, written with Louisiana's new Act 757 rules in mind.


As an independent agency, Aubert Insurance compares options from multiple carriers, then walks you through the exclusions and limits so you know exactly what your contract says before you sign it. That conversation tends to catch the gaps that cost masons the most.


Ready to see where your coverage stands? Start a Quote with Kyle Beerbohm at Aubert Insurance Agency, serving contractors in Covington and Slidell. Your crew works hard to build something lasting, and your insurance should hold up just as well.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.
certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.
general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.
louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.
how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.
what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.
what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.
workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.
who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.
louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.

Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461