













Covington & Slidell Independent Insurance Agents
The right Abita Springs policy depends on three things: how your home was built, what sits on your land beyond the main house, and how much tree damage your area sees. Here is how each of those affects coverage, written for owners who want to understand their policy before a claim forces the issue.
Protecting Your Abita Springs Property
Abita Springs home insurance means matching coverage to older cottages, rural acreage with outbuildings and wells, and heavy tree exposure. Historic wiring and pier foundations typically require specialized carriers, and detached structures and wells may need added endorsements. Aubert Insurance Agency, serving Covington and Slidell since 1910, compares multiple carriers to fit these properties.
Your fire protection rating matters too. St. Tammany Fire Protection District 8 serves the Abita Springs area, and improved fire ratings on a scale of 1 to 10 lead to lower homeowners insurance costs for local residents. Ask your agent which rating applies to your address. A rural lot far from a hydrant may be rated differently than a cottage near the town center.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Many St. Tammany families end up with both: standalone coverage for the land, plus an umbrella over the home and vehicles.
Comparison: Standalone Liability vs. Umbrella Coverage
Understanding the Named Storm Deductible
A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.
There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.
| Factor | Standalone Liability | Umbrella Policy |
|---|---|---|
| Underlying policy required | No | Yes, home and auto typically |
| When it pays | First dollar of a covered claim | After underlying limits run out |
| Typical use | Vacant land, hunting tracts, specific risks | Broad extra protection across policies |
| Cost structure | Priced by acreage, use, and limit | Priced by number of homes, cars, drivers |
| Scope | Narrow, tied to named property or risk | Wide, follows underlying coverage |
| Common limits | $300,000 to $1 million | $1 million and up |
Insuring Historic District Cottages and Older Construction
Many cottages near the trailhead and along the older streets have original heart pine floors, wide porches, and wiring that predates air conditioning. That charm is the reason people buy them. The same features are what make standard carriers hesitate.
Wiring is usually the first problem. Major carriers like Allstate and Progressive require removal of active knob-and-tube wiring within 30 days of closing, while State Farm may allow it with a licensed electrician's certification. Fuse boxes, ungrounded outlets, and aluminum branch circuits can trigger similar underwriting questions. Order the electrician's inspection before closing rather than after, so you know your options while you can still negotiate repairs with the seller.
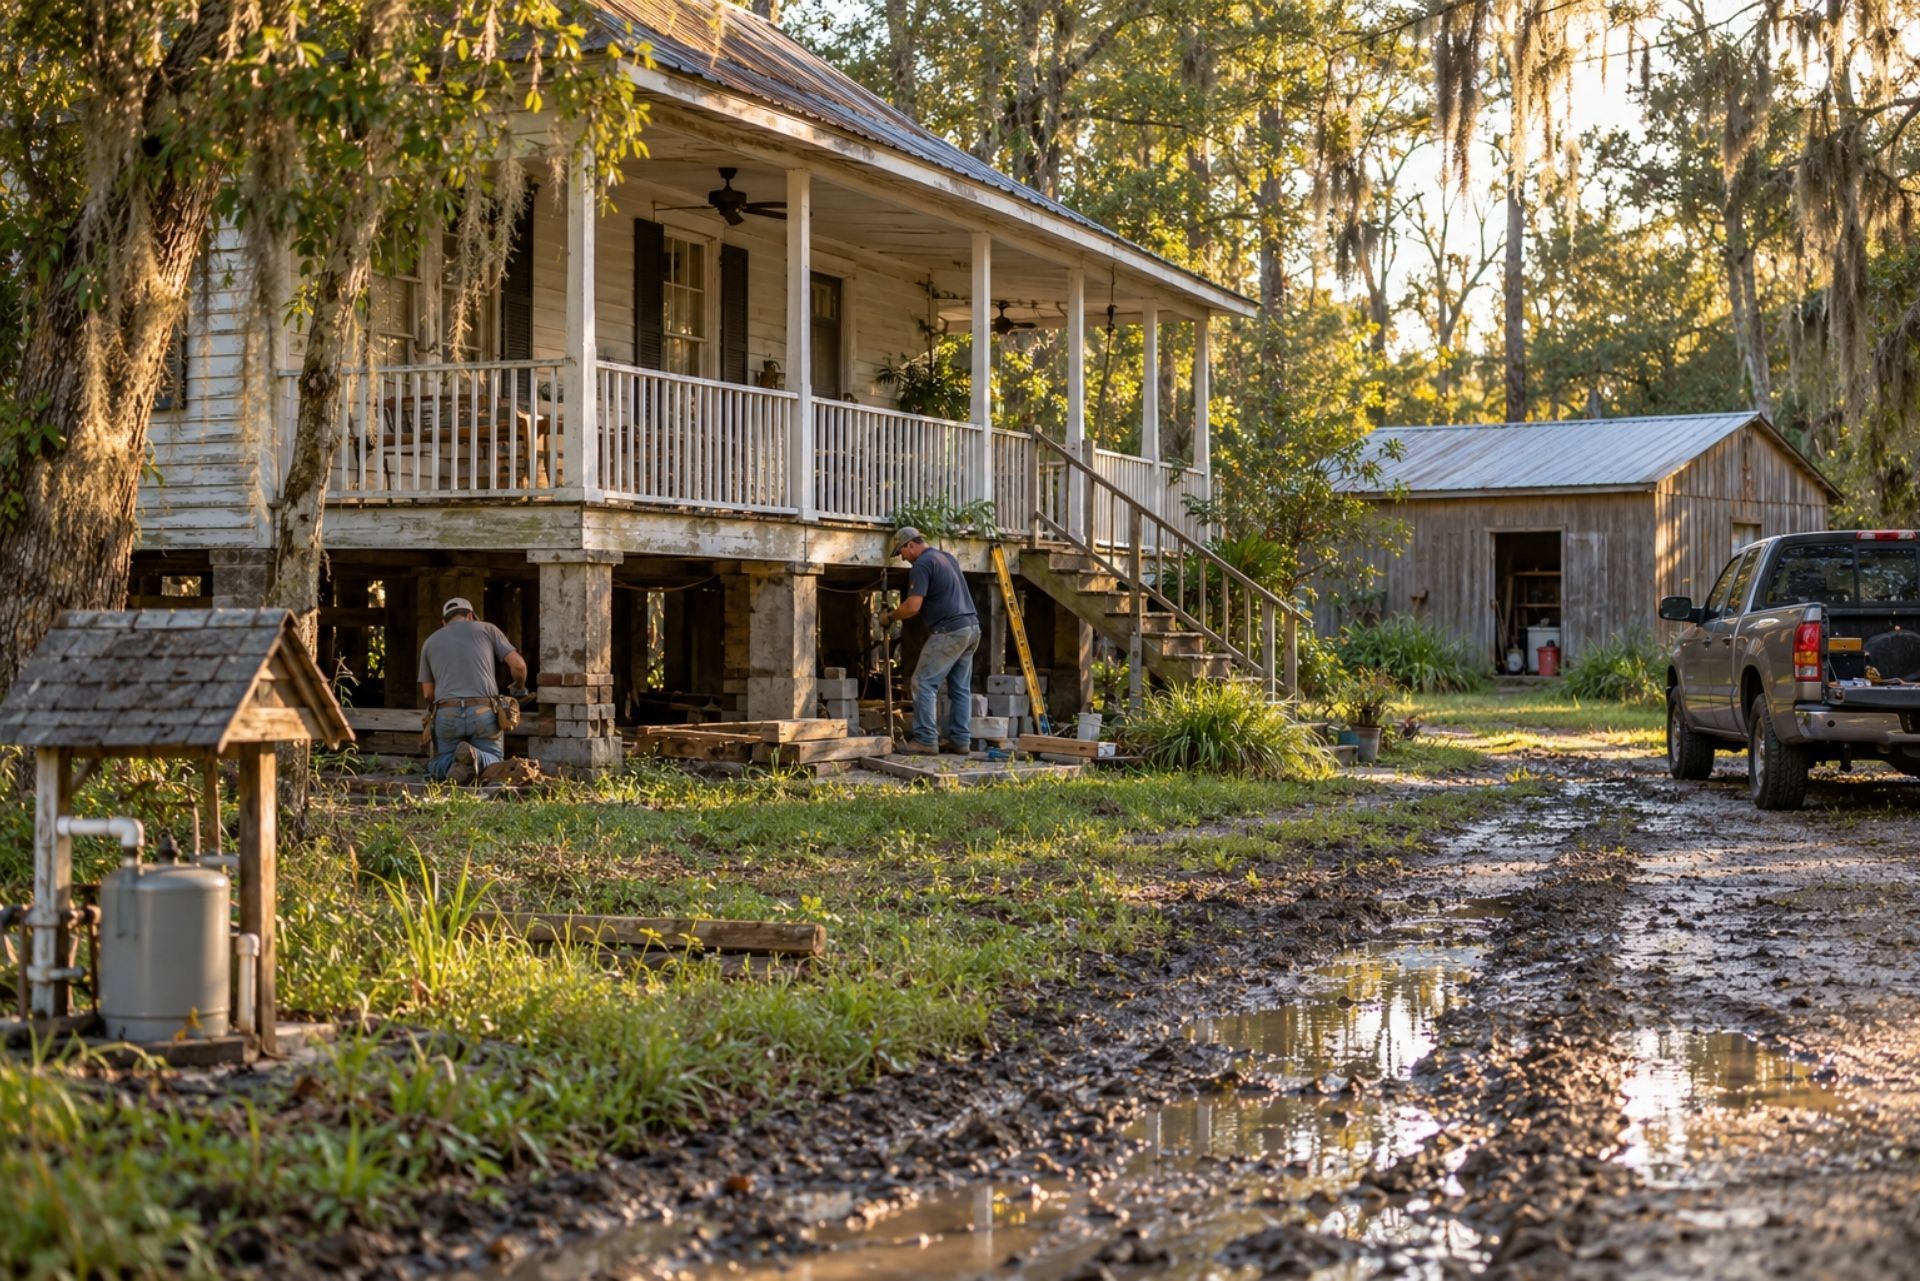
Pier foundations raise a different question. Underwriters typically want to know the condition of the piers, whether the skirting is intact, and whether sills show rot or termite damage. A home that sits on well-maintained brick piers often places without trouble. A visibly leaning structure may be declined outright.
Specialized carriers and excess-and-surplus markets typically fill the gap when standard companies decline. They may price older construction higher or offer actual cash value terms instead of replacement cost, so read the declarations page closely. Raised homes do have one advantage: under Risk Rating 2.0, elevated homes in 2026 can save between $500 and $2,500 a year on flood insurance compared with slab-on-grade homes.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Rural Lots With Outbuildings and Wells
Drive a few minutes out of town toward the Bogue Chitto side, and you'll see five-acre lots with a pole barn, a workshop, a detached garage, and a wellhouse. The standard homeowners form handles some of that well and some of it poorly.
Detached Structures
Most Louisiana homeowners policies include Coverage B for "other structures," usually set at 10% of the dwelling limit. On a $300,000 home, that gives $30,000 for every fence, shed, barn, and carport combined. A single metal shop building can exceed that amount. Coverage B can typically be raised by endorsement. One thing to keep in mind: outbuildings used for a business, such as a woodworking shop selling furniture, are often excluded and may need a separate commercial policy.
Wells and Private Water Systems
The wellhouse structure usually falls under Coverage B. The pump is a different matter. A pump that burns out from age or an electrical fault is generally treated as wear and tear or mechanical breakdown, which the base policy excludes. Equipment Breakdown Coverage is an optional endorsement needed to cover sudden electrical or mechanical failure of well systems, water heaters, and HVAC units. It typically costs little compared to a pump replacement, which makes it one of the more sensible add-ons for a rural owner.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Managing Tree Fall Claims in the Abita Forest
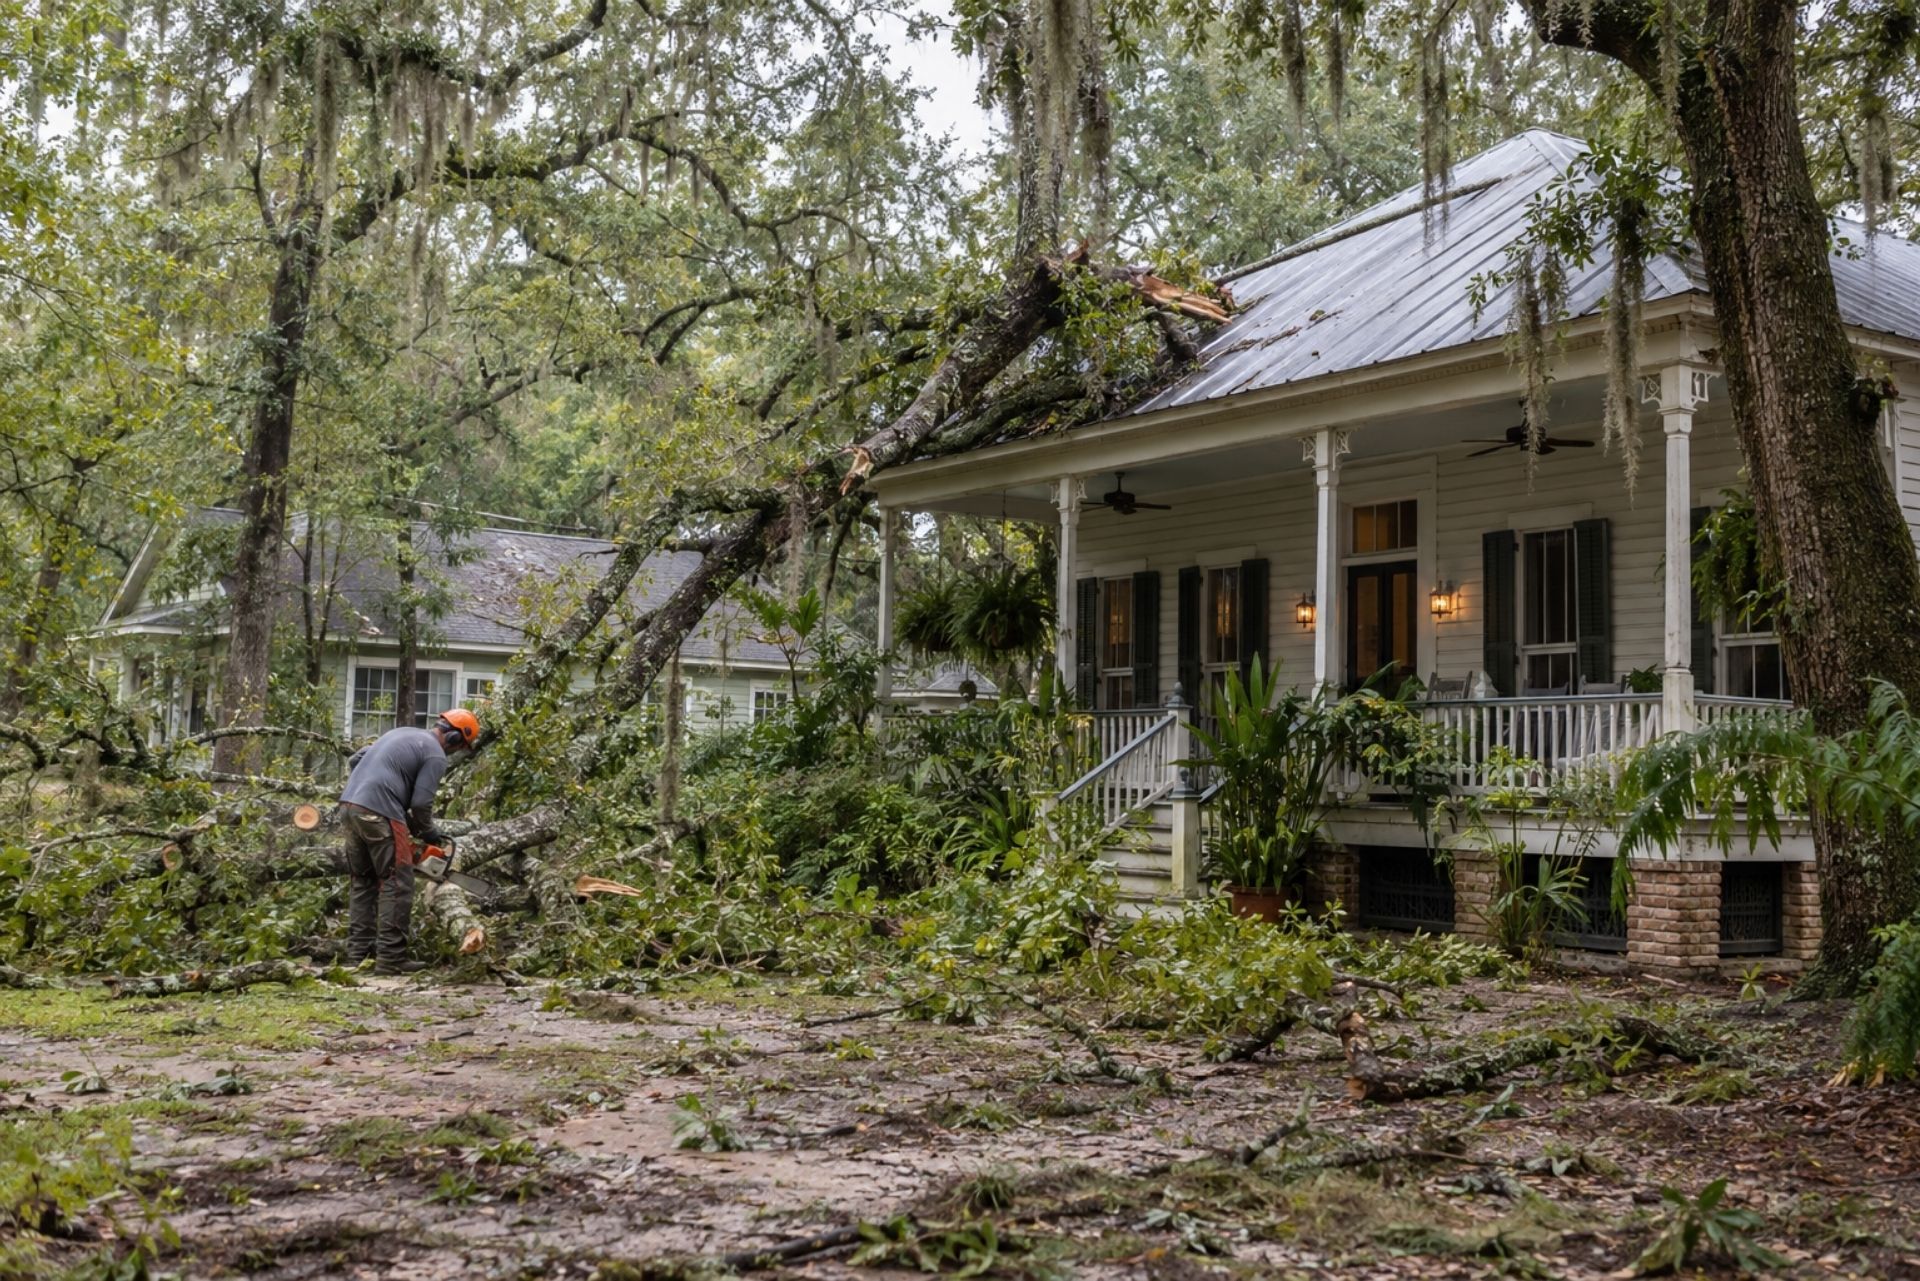
Abita Springs sits under a canopy of longleaf pine, water oak, and live oak. That canopy keeps summer bearable, and it also produces a steady stream of tree claims after every strong storm.
Here is how a typical tree fall claim works:
- Document first. Photograph the tree, the root ball or break point, and every damaged area before anything moves.
- Prevent further damage. Tarp the roof and keep receipts. Most policies require reasonable steps to protect the property.
- Report promptly. Call your agent or carrier. Delays may complicate a claim, especially after a regional storm when adjusters are backlogged.
- Get removal quotes. Tree removal from a structure is usually included as part of the covered loss.
The catch is what happens when a tree falls and hits nothing. If a pine drops across your yard or driveway without striking a covered structure, removal is commonly excluded, or limited to a small amount such as $500 per tree and around $1,000 per occurrence, depending on the carrier. Owners are often surprised to find themselves paying for cleanup on two acres out of pocket.
Whose tree it was matters less than people think. If your neighbor's healthy oak falls on your roof, your own policy typically responds. If the tree was visibly dead and the owner was warned, liability may shift. Trim dead limbs over the roofline now, because an adjuster may question damage from a tree that was clearly rotten.
Comparing Coverage for Older vs. Modern Homes
Coverage for older and modern homes differs in eligibility, settlement terms, and the endorsements carriers typically offer. This chart summarizes common patterns. Actual terms vary by carrier.
| Feature | Basic Coverage | Extended Coverage |
|---|---|---|
| Pier foundations | May require inspection; ACV settlement possible | Replacement cost available if piers are sound |
| Slab foundations | Standard eligibility | Standard, with options for added foundation water damage |
| Knob-and-tube wiring | Often declined or must be removed | Specialty carriers may accept with certification |
| Updated electrical panel | Standard eligibility | May qualify for better pricing |
| Well pump failure | Excluded as mechanical breakdown | Covered with equipment breakdown endorsement |
| Outbuildings | 10% of dwelling (typical) | Increased limits by endorsement |
| Tree debris (no structure hit) | Usually excluded | Limited removal allowance may apply |
Here's what this means for you: a 1920s cottage and a 2020 build on the same street can carry very different policies. An upgraded panel, re-leveled piers, or a new roof can move an older home toward extended terms.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Common Questions About Abita Springs Home Insurance
Does my insurance cover my well pump? The base policy typically excludes pump failure from age or mechanical breakdown. An equipment breakdown endorsement may cover sudden electrical or mechanical failure.
Can I get coverage for a home on piers? Yes. Carriers usually want the piers in good condition, and an inspection may be required. Elevated homes can also see lower flood premiums.
Will a carrier insure a house with knob-and-tube wiring? Some carriers require removal within 30 days of closing, while others may accept an electrician's certification. Specialty markets may be an option if standard carriers decline.
Who pays when a tree falls but misses the house? Removal is usually your expense unless the tree damaged a covered structure. Some policies offer a small removal allowance.
How much notice do I get if my policy is non-renewed? Starting July 1, 2026, Act 182 requires insurers to give at least 60 days' written notice before canceling or non-renewing, along with a specific reason.
Does my fire district affect my rate? Yes. The Louisiana Department of Insurance has recognized 18 fire districts statewide for improved fire ratings as of August 2026, and better ratings directly lead to reduced premiums.
Making the Right Choice for Your Property
An Abita Springs home rarely fits a standard policy. A cottage with original wiring, a barn that outgrew its Coverage B limit, a well pump with no breakdown endorsement, and a yard full of tall pines each create a gap that only shows up when you file a claim. The fix is usually simple: an inspection, an endorsement, or a carrier that specializes in older construction.
As an independent agency, Aubert Insurance Agency can compare several carriers in one place and explain what each policy covers and excludes before you sign. The agency has helped families across St. Tammany Parish protect what matters since 1910 from its Covington and Slidell offices.
Gather your electrician's report, your outbuilding dimensions, and your well details, then Start a Quote. It is much easier to sort out these details before hurricane season than after the first oak comes down.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













