













Louisiana Flood Insurance

Covington & Slidell Independent Insurance Agents

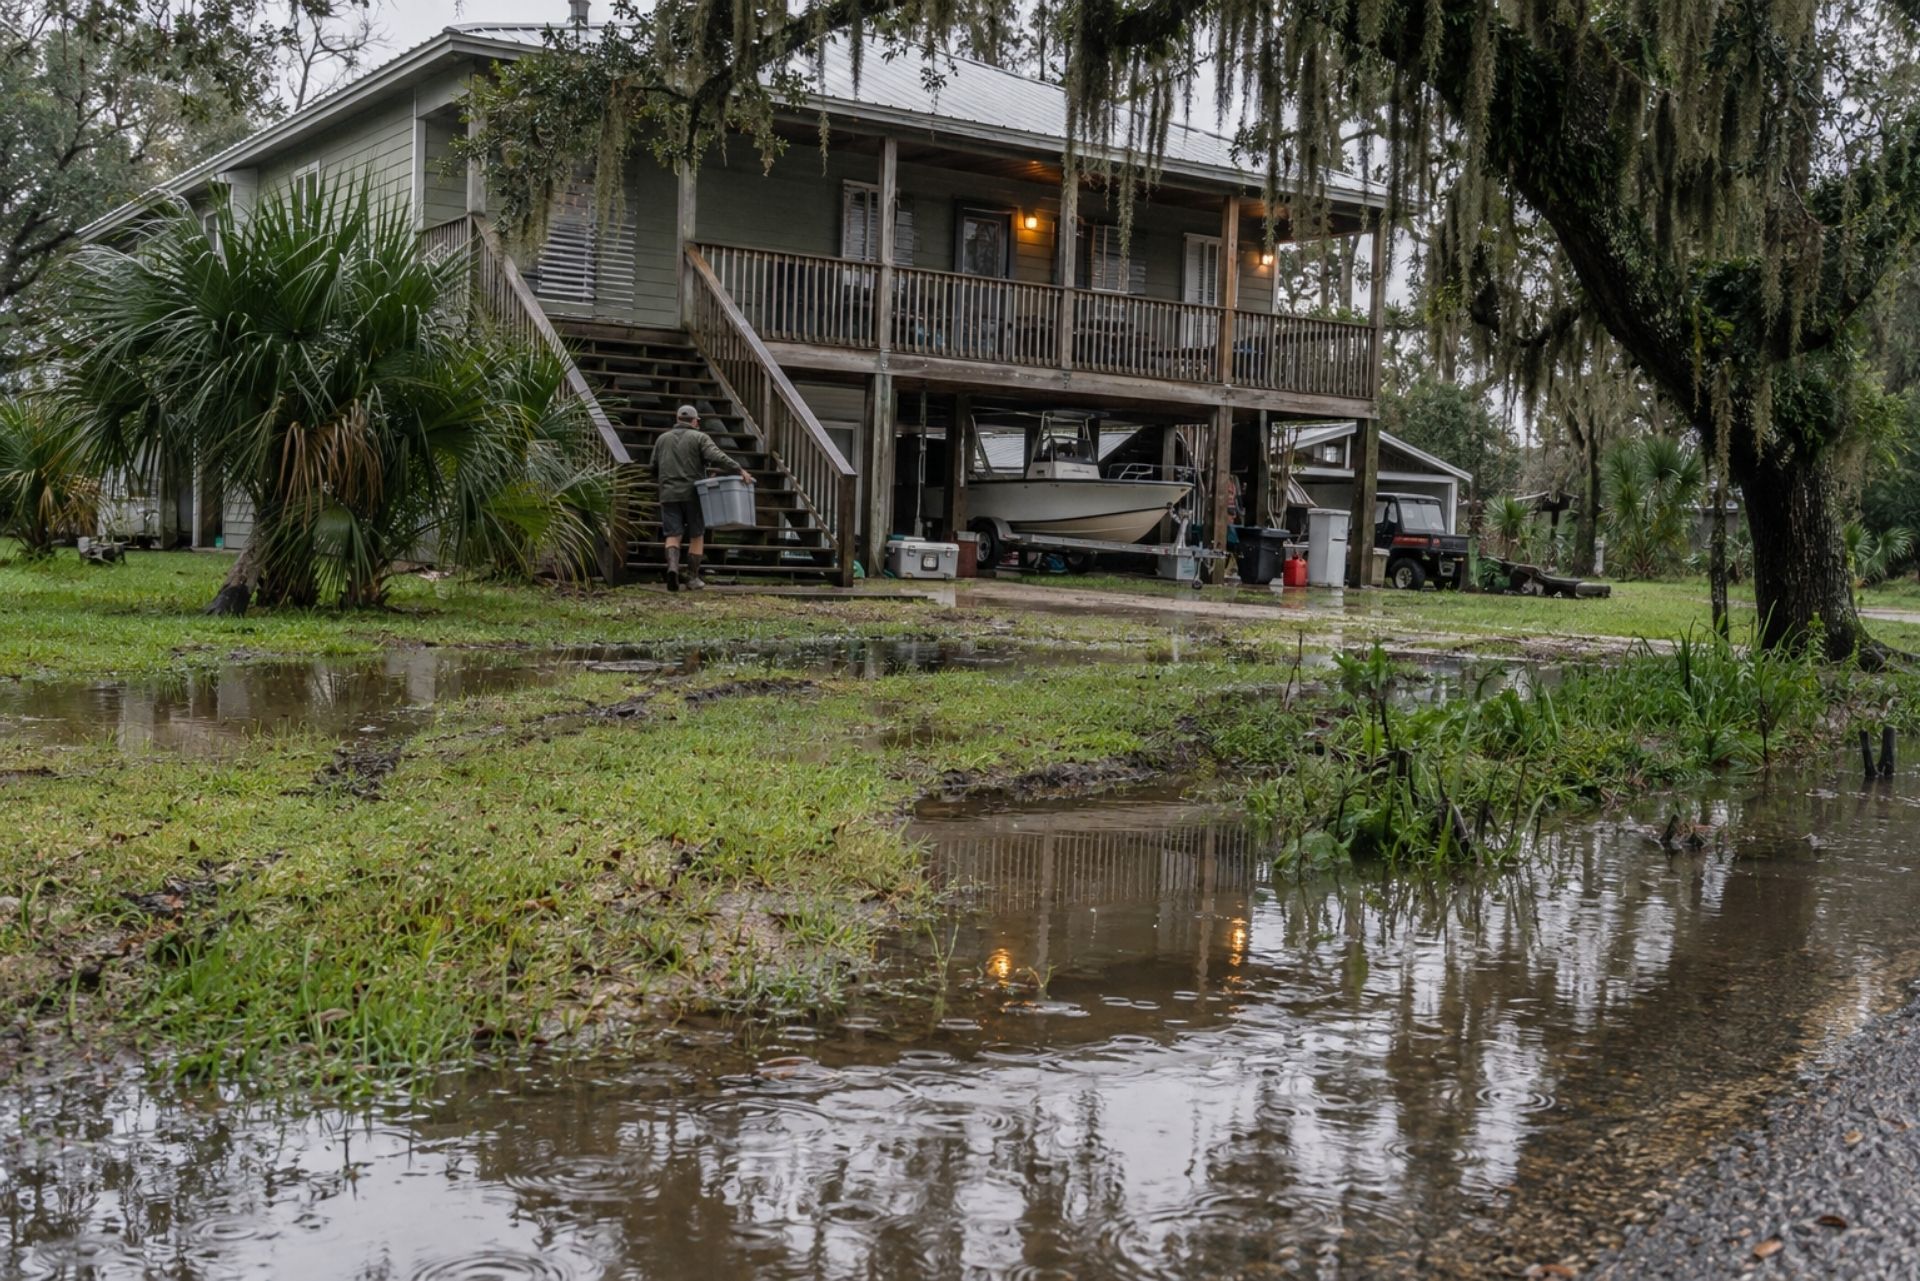
Every few years, a storm reminds St. Tammany Parish homeowners that water does not read flood maps. It may be a slow-moving tropical system, a stalled front over the Tchefuncte, or a summer downpour that overwhelms a neighborhood drainage ditch. Whatever the cause, the homeowners who recover fastest are usually the ones who bought flood coverage months earlier, not the night before landfall.


Flood insurance in Louisiana is more complicated than it used to be. Prices have shifted under a new federal rating system. Private carriers now compete with the federal program. Lenders, waiting periods and zone designations all affect what you pay and when you are protected. Here is how the pieces fit together for homeowners in Covington, Slidell and the surrounding parish.

Understanding Louisiana Flood Insurance Options

Louisiana residents can protect their homes from flood damage in two main ways. The first is a National Flood Insurance Program (NFIP) policy, typically written and serviced by carriers such as Wright Flood. The second is a private flood policy, which may offer higher limits or different pricing as costs rise.


Flood coverage matters more here than almost anywhere else in the country. Louisiana holds roughly 419,000 active NFIP policies, about 9% of the national total. That is an outsized share for a state of our population, and it reflects how much of daily life in south Louisiana sits near water.


The program itself runs on congressional reauthorization. The NFIP has been extended through December 11, 2026 under the latest continuing appropriations legislation. Lapses in authorization have happened before, and they can briefly stall new policies and home closings. That is one reason some buyers like having a private market option in their back pocket.


The Louisiana Department of Insurance flood resource page is a useful starting point if you want a plain explanation of your rights as a policyholder.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

How coverage choices change a Louisiana homeowners premium. Structure only — your rate depends on your property. [CONFIRM figures]

NFIP Policies Through Wright Flood

Most people who carry federal flood insurance never deal with FEMA directly. They buy through a "Write Your Own" carrier, a private insurance company that sells and services NFIP policies under the federal program's rules. Wright Flood is one of the largest of these carriers in Louisiana.

How Wright Flood Administers Federal Coverage

When you buy an NFIP policy through Wright Flood, the coverage terms, limits and rates are set by FEMA. Wright Flood handles the paperwork: issuing the policy, collecting premiums, processing renewals and managing claims. Think of it as the federal product with a private company's customer service attached.


This setup means the price for a given home is generally the same no matter which Write Your Own carrier issues it. What can differ is the experience, especially at claim time. A carrier with deep Louisiana volume may be more familiar with the elevation certificates, crawlspace foundations and raised slab construction common in St. Tammany.


Wright Flood has also moved further into the private market. In November 2025, it acquired Poulton Associates, adding proprietary products like ResiFlood and FocusFlood. For an independent agency, that means one carrier relationship may open both federal and private options for the same client.

NFIP vs. Private Flood Insurance Comparison

The federal program has hard caps. Private policies may go higher and may include features the NFIP does not offer, though terms vary by carrier and policy.

Feature NFIP Policy Private Flood Policy
Building limit $250,000 max May offer higher limits
Contents limit $100,000 max May offer higher limits
Contents valuation Actual cash value (depreciated) Replacement cost may be available
Waiting period Typically 30 days Often shorter, varies by carrier
Pricing Set by FEMA under Risk Rating 2.0 Set by carrier underwriting
Additional living expenses Not included May be included
Cancellation Federal rules apply Carrier can typically non-renew

One common mistake: a family in a $450,000 Covington home carries only the NFIP maximum and assumes they are fully protected. A total loss would leave a $200,000 gap. Excess flood coverage or a private policy can close that gap.

Landlords, condo owners and renters

Each needs a different form. We write rental property, condo and renters policies alongside standard homeowners cover.

Risk Rating 2.0 Pricing in Louisiana

Before Risk Rating 2.0, NFIP premiums were driven mostly by your flood zone and elevation. FEMA's newer system looks at each property individually, factoring in distance to water, flood frequency, rebuilding cost and the type of flooding likely to occur, such as storm surge, river overflow or heavy rainfall.


The goal was fairness. The result, for many Louisiana households, was sticker shock. Nationwide, about 77% of policyholders saw premium increases after FEMA rolled it out. The average annual NFIP premium in Louisiana has climbed to roughly $1,420, currently the highest in the nation.


Pushback has been loud. In February 2026, Senators John Kennedy and Bill Cassidy urged FEMA to halt Risk Rating 2.0, pointing to increases topping 100% in some areas and falling NFIP participation as people drop coverage they can no longer afford. Louisiana is also leading a lawsuit joined by 9 other states and 44 parishes arguing the methodology is "arbitrary and capricious."


Here is what that means for you: existing policyholders typically see increases phased in each year rather than all at once. If your renewal keeps creeping up, it may make sense to get a private quote for comparison. Some homes that look expensive under FEMA's model price more favorably with a private carrier, and some do not. You only find out by comparing.

Distance from open water, the flood zone and the fire district all move the rate, sometimes street by street inside Covington.

The named-storm deductible is a percentage of the dwelling limit, so it is real money at claim time. Pairing the policy with your auto insurance usually lowers both.

Location and elevation

Deductibles and bundling

Why Zone X Homes Still Flood

Zone X is the designation FEMA uses for moderate- to low-risk areas. Lenders usually do not require flood insurance there, and that is exactly why so many Zone X homeowners skip it. The problem is that water does not stop at a map boundary.


More than 20% of NFIP claims come from properties outside high-risk flood zones. That number surprises people, but it makes sense once you picture how flooding actually happens in St. Tammany. A clogged culvert, a backed-up drainage canal or ten inches of rain in an afternoon can put water in homes that have never flooded before. The May 2021 rains and August 2016 floods both caught plenty of "low-risk" homeowners in the region off guard.


A useful way to think about it: every home in Covington and Slidell is in a flood zone. Some are just lower risk than others. Zone X describes probability, not immunity.


The good news is that Zone X homes often qualify for lower premiums, so the cost of protection may be far less than people expect. If you are in Zone X and uninsured, you are carrying the full cost of a flood yourself, and federal disaster assistance is typically a loan or a small grant, not a rebuild check.

The 30-Day Waiting Period

NFIP policies typically do not take effect until 30 days after purchase. This rule exists to stop people from buying coverage only when a storm is already on the radar. In practice, it means hurricane season preparation has to start well before the National Hurricane Center starts drawing cones.


The timeline catches people every year. A homeowner watches a system form in the Caribbean, calls on a Monday, and learns the policy will not activate until weeks after landfall. By the time a storm enters the Gulf, it is almost always too late to get NFIP coverage in place.


There are a few exceptions worth knowing:


  • Lender-required purchases: A 0-day waiting period applies when flood insurance is bought in connection with making, increasing or renewing a home loan.
  • Map changes: Shorter waits may apply in certain situations when a property is newly mapped into a high-risk zone.
  • Private policies: Many private flood carriers use shorter waiting periods, though terms vary and some may restrict new policies once a named storm is approaching.


The practical advice is simple. Buy or review your flood policy in winter or early spring, long before June 1. If you are closing on a home, line up flood coverage during underwriting so it is ready at closing.

Distance from open water, the flood zone and the fire district all move the rate, sometimes street by street inside Covington.

The named-storm deductible is a percentage of the dwelling limit, so it is real money at claim time. Pairing the policy with your auto insurance usually lowers both.

Location and elevation

Deductibles and bundling

Common Louisiana Flood Insurance Questions

Do I need flood insurance if I am in Zone X? Your lender may not require it, but you are still exposed. Over 20% of flood claims come from outside high-risk zones, and Zone X premiums are often lower than people assume.


Does my homeowners insurance cover rising water? No. Standard homeowners policies typically exclude flood damage from rising water, storm surge and overflowing waterways, so you need a separate flood policy.


Can I switch from an NFIP policy to a private one? Usually, yes. Make sure the private policy meets your lender's requirements and starts before your NFIP policy ends so there is no gap.


Will my flood policy pay for a hotel if I cannot live at home? NFIP policies do not include additional living expenses. Some private flood policies may include this coverage, so ask before you buy.


How much flood coverage should I carry? Aim to insure the full cost of rebuilding your home, not its market value or loan balance. If that exceeds $250,000, look at private or excess flood options.


Is it too late to buy coverage once hurricane season starts? Not necessarily, but the 30-day wait means you should act early. Once a storm is in the Gulf, NFIP coverage will likely not start in time.

Making the Right Choice for Your Property

Flood insurance in Louisiana comes down to a few honest questions. Is the NFIP limit enough for your home? Has Risk Rating 2.0 pushed your premium to a point where a private quote is worth checking? Are you in Zone X and assuming you are safe? And is your coverage in place well before the next storm forms?


There is rarely one right answer for every street in St. Tammany. A raised home near Bayou Liberty and a slab home in an older Covington subdivision can price very differently, even under the same program. That is where comparing federal and private options side by side pays off.


Aubert Insurance Agency has served Covington and Slidell since 1910. As an independent agency, we compare NFIP and private flood options from multiple carriers and explain what each policy covers, and what it does not, before you sign. Start a Quote today and get your coverage working before you need it.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
