


Louisiana Commercial Auto Insurance

Dwelling coverage rebuilds the house itself. Other structures coverage handles the detached garage, the fence, the shed and the pool house, usually at ten percent of the dwelling limit.

Covington & Slidell Independent Insurance Agents

Your house and other structures

Commercial auto insurance protects Louisiana businesses from financial loss when company vehicles are involved in accidents. It typically combines liability coverage for injuries and damage you cause with physical damage coverage for your own trucks and trailers. Aubert Insurance Agency has helped business owners in Covington and Slidell protect what matters since 1910.

Understanding Louisiana Commercial Auto Insurance for Your Business

Picture a landscaping crew pulling a loaded trailer down Highway 190 at 7 a.m. A sedan cuts across two lanes, the truck brakes hard, and the trailer jackknifes into a parked car. In about four seconds, that business owner may be facing a property damage claim, a possible injury lawsuit, and a truck that won't run for three weeks.


That is the job commercial auto coverage is built to handle. A typical policy may include several pieces:


  • Liability: pays for injuries and property damage your drivers cause to others
  • Collision and comprehensive: covers damage to your own vehicles from crashes, theft, flooding, or falling limbs
  • Uninsured/underinsured motorist: protects your drivers when the at-fault party has little or no insurance
  • Medical payments: helps with injury costs for your driver and passengers


The most common mistake we see is a contractor who titles a truck to the business but keeps it on a personal auto policy. Personal carriers often exclude or limit business use. If that truck is hauling equipment to a job when the accident happens, the claim may be denied outright.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Policies pay for sudden accidental damage, not for a roof at the end of its life, a slow leak, termites, or mould that followed a maintenance problem.

Wear, maintenance and mould

Coverage for Work Trucks, Trailers, and Fleets

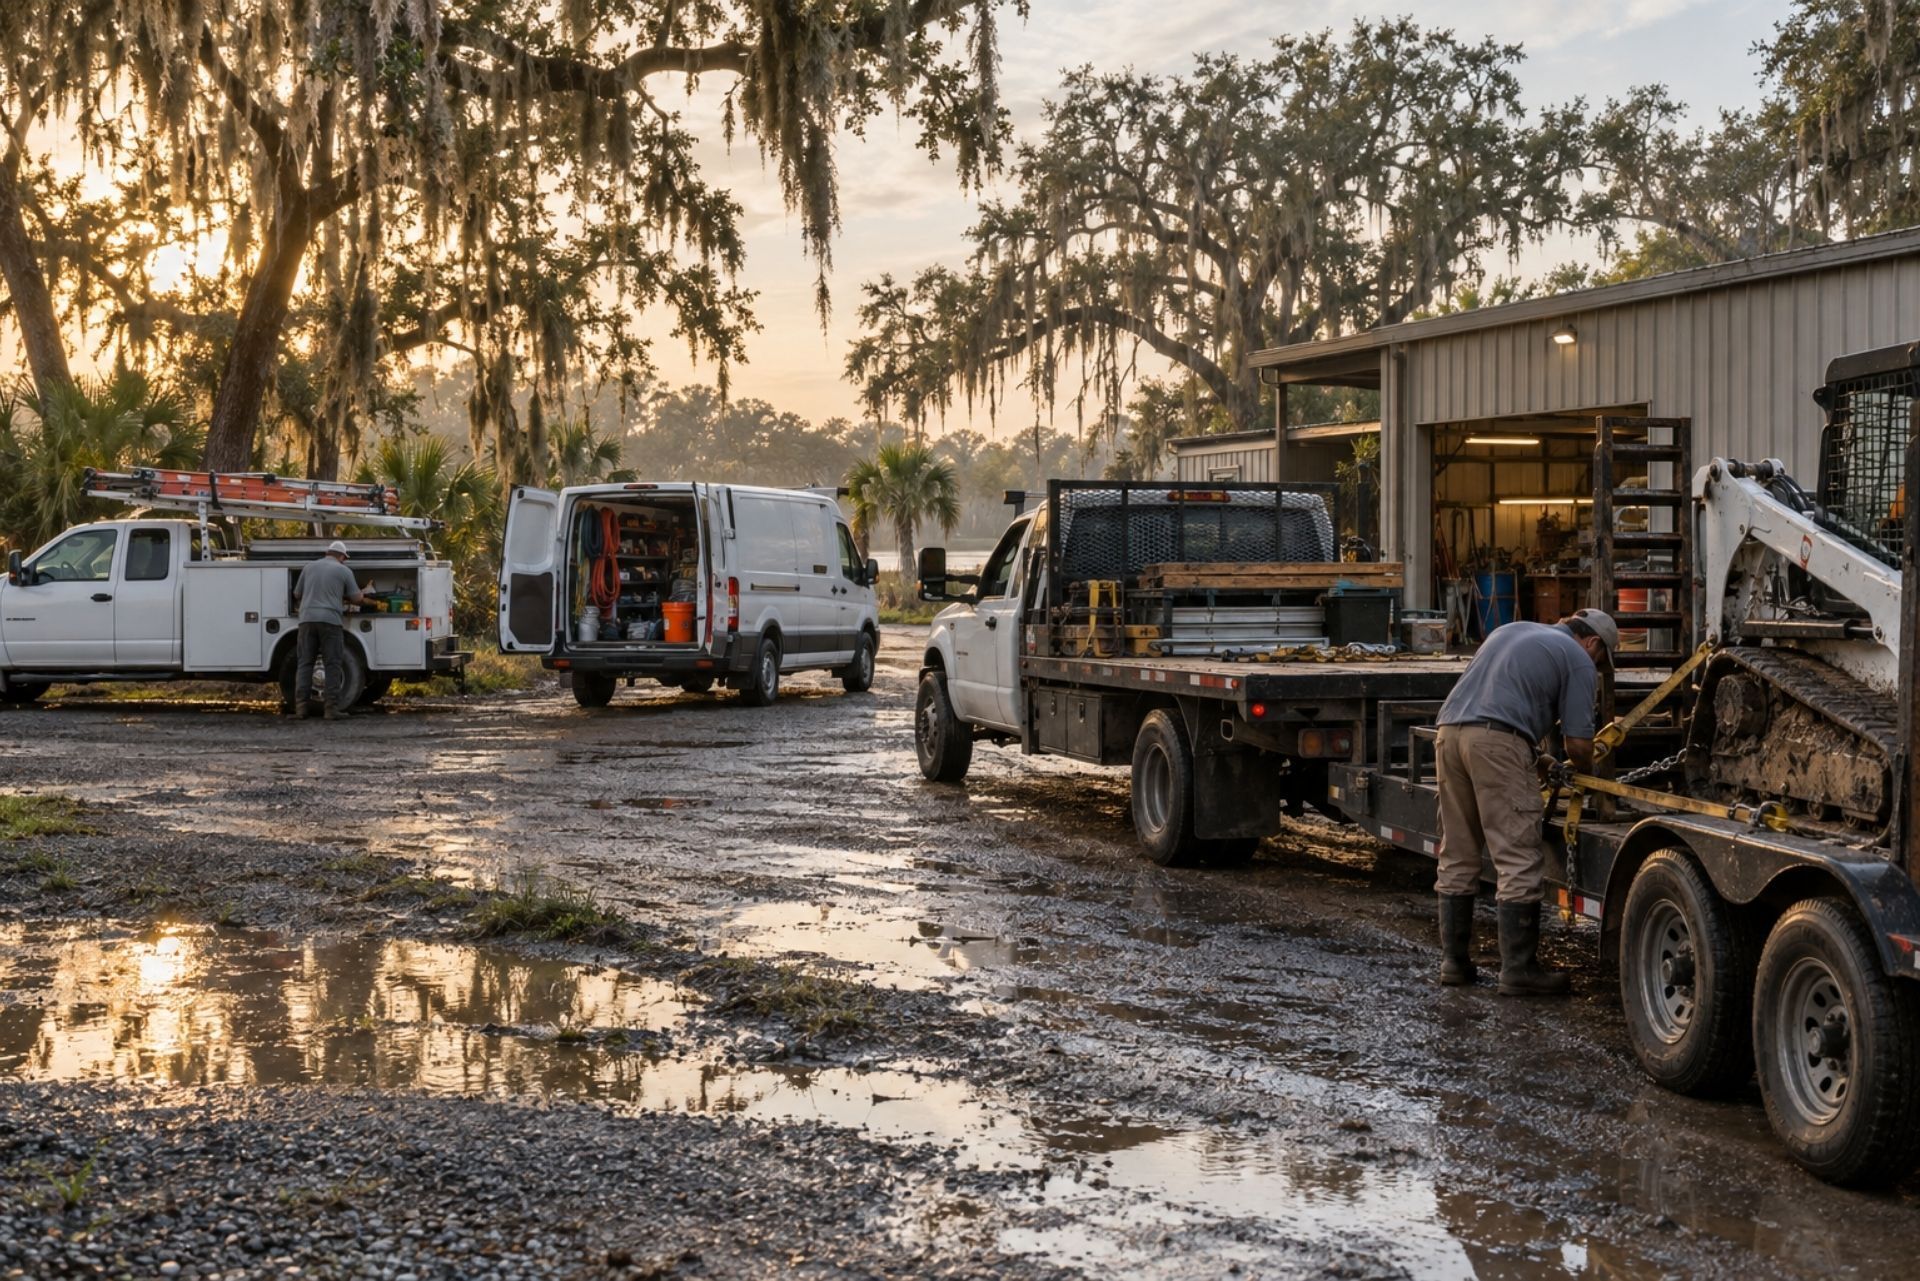
Not every business vehicle looks like a box truck. In St. Tammany Parish, we see pickups with ladder racks, dump trucks, enclosed trailers, food trucks, and service vans packed with tools. Each one carries different risks, and your policy should reflect how the vehicle is actually used.


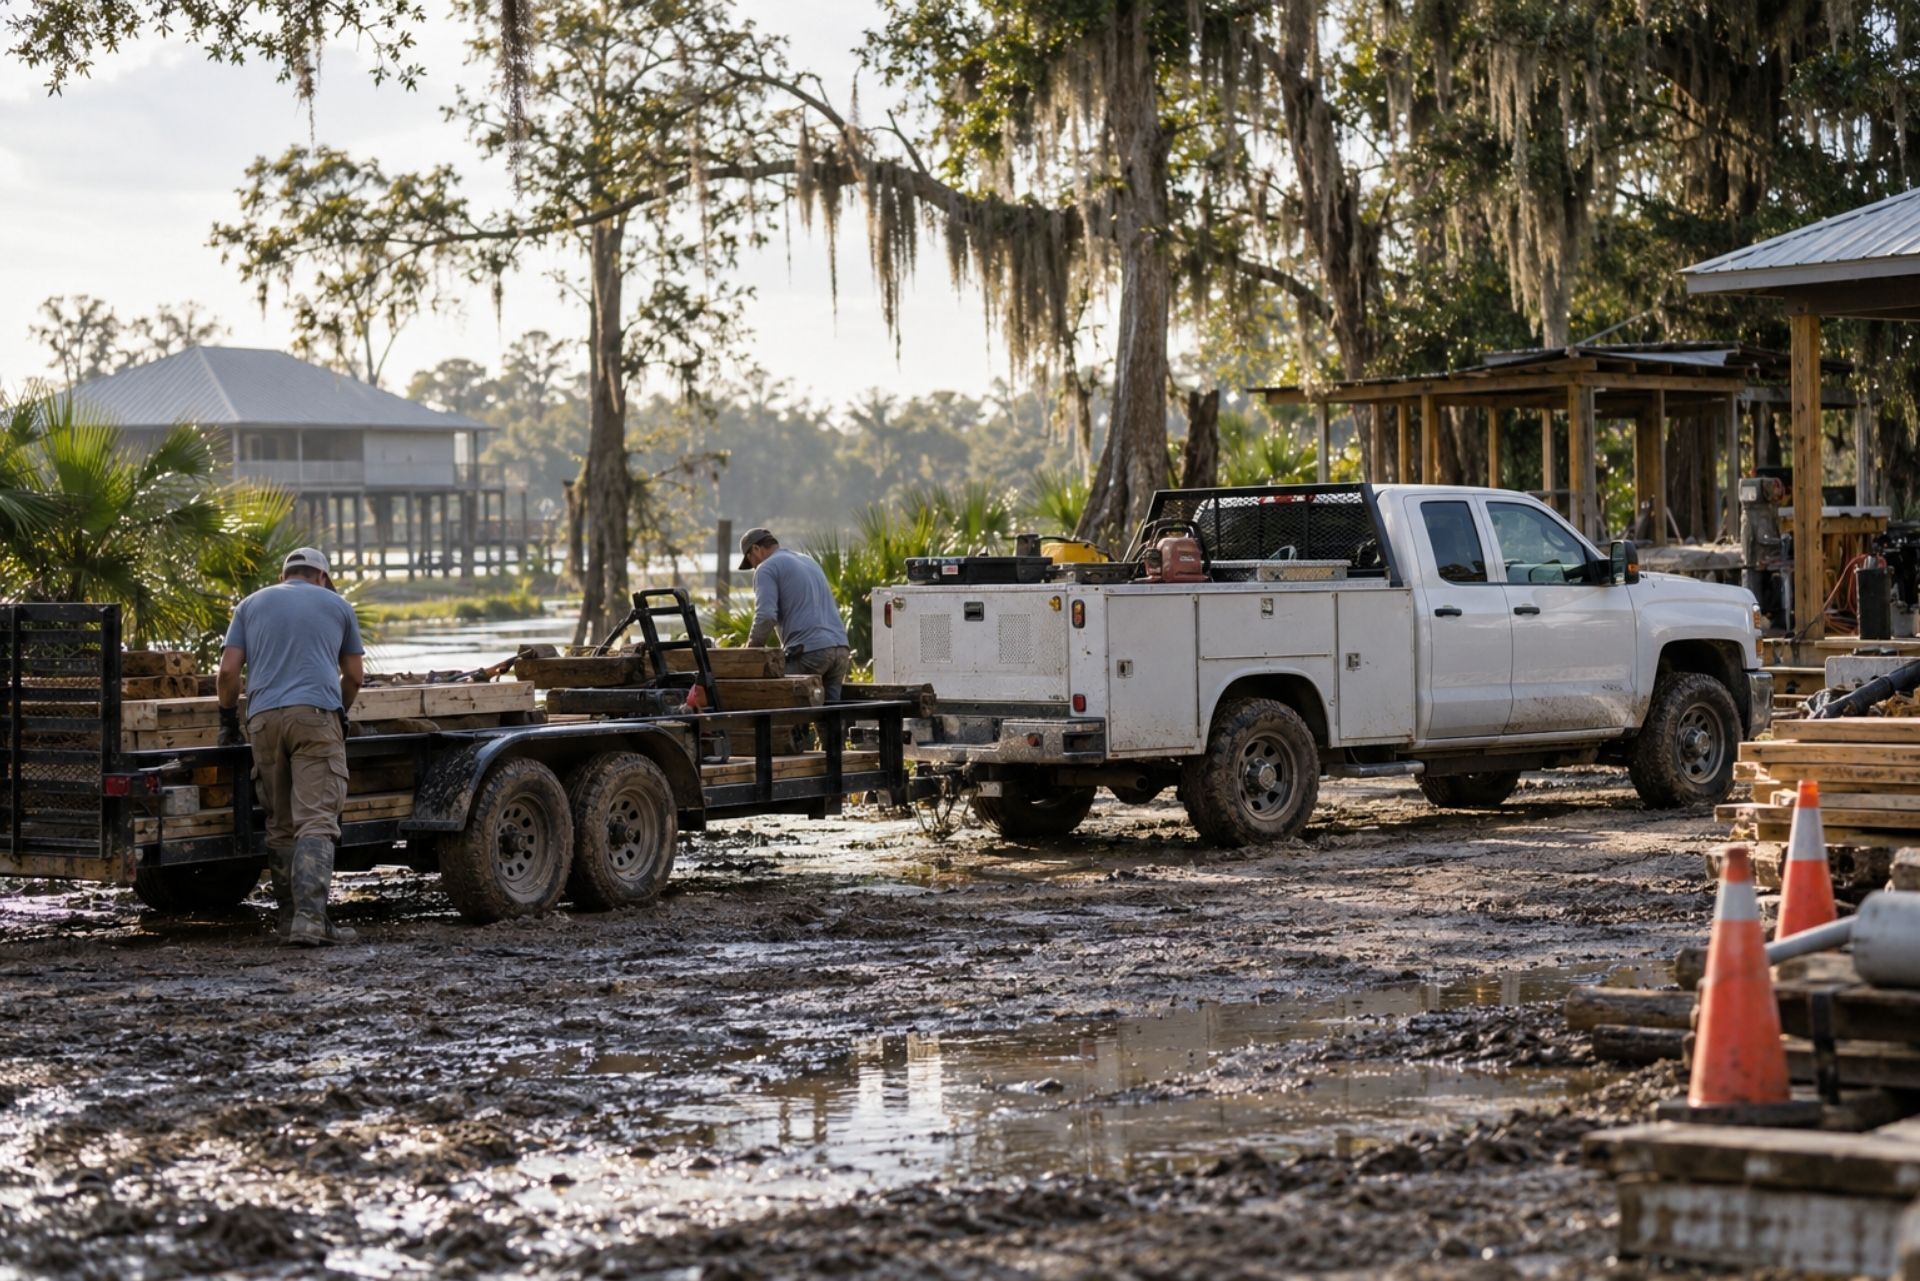
Trailers deserve special attention. A trailer attached to your power unit generally picks up liability from the truck, but physical damage to the trailer itself may need separate coverage. If you haul trailers owned by someone else under a written agreement, trailer interchange coverage typically protects that trailer against physical damage even when it's unhooked from your truck. A standard non-owned trailer endorsement usually won't do that.


For fleets of five or more vehicles, many carriers offer fleet policies that simplify billing and may add flexibility for adding or removing units. Tools and equipment stored in the vehicle are another gap. Commercial auto usually covers the truck, not the $8,000 in generators and saws inside it, so ask about inland marine coverage for that gear.

Louisiana Liability Limits and State Requirements

Louisiana sets minimum liability limits for every vehicle on the road, and those minimums are low compared to what a serious commercial crash costs. Interstate and for-hire carriers face separate federal filing requirements. Here's how state minimums typically compare to what we often recommend for working fleets:

Coverage Area Louisiana State Minimum Typical Recommended for Fleets
Bodily injury liability Low split limits set by state law $1 million combined single limit
Property damage liability Low per-accident amount Included in $1 million CSL
Uninsured motorist Can be rejected in writing Match your liability limit
Umbrella/excess Not required $1 to $5 million for larger fleets
Physical damage Not required (lender may require) Actual cash value with sensible deductible

A single injury verdict involving a commercial truck can blow past state minimums quickly. Anything above your limit can come out of business assets. Ask your agent to confirm the current state figures for your vehicle class.

Landlords, condo owners and renters

Each needs a different form. We write rental property, condo and renters policies alongside standard homeowners cover.

Protecting Assets with Hired and Non-Owned Auto Coverage

Your office manager drives her own SUV to the bank to drop off deposits. Your foreman runs to the supply house in his personal truck. You rent a moving truck for a weekend job site cleanup. In each case, if there's an accident, the injured party may sue your business, not just the driver.


Hired and non-owned auto coverage, often called HNOA, steps in for those situations. The "non-owned" part may cover your company's liability when employees use personal vehicles for work tasks. Their personal policy typically responds first, but if the damages exceed their limits (and personal limits are often modest), your business is next in line.


The "hired" part applies to vehicles your business rents, leases short-term, or borrows. Rental counter coverage is often limited or expensive, and it may not extend to how you're actually using the vehicle.


HNOA can be added to a commercial auto policy or, for businesses without owned vehicles, sometimes to a business owner's policy. Real estate offices, home health agencies, and consultants in Covington and Slidell often need it without realizing it. If anyone drives on your behalf, even occasionally, this coverage deserves a look.

Gaps Worth Knowing About

Distance from open water, the flood zone and the fire district all move the rate, sometimes street by street inside Covington.

The named-storm deductible is a percentage of the dwelling limit, so it is real money at claim time. Pairing the policy with your auto insurance usually lowers both.

Location and elevation

Deductibles and bundling

Why Louisiana Commercial Auto Rates Run High

Louisiana business owners regularly ask why their premiums seem out of step with other states. The honest answer is a mix of legal, weather, and road conditions that carriers price into every policy.


Litigation tops the list. Social inflation, meaning rising claim costs driven by more lawsuits and larger jury awards, remains a primary headwind for the Louisiana casualty market as of mid-2026. Fraud has played a role too. In September 2026, a New Orleans jury convicted a former attorney in a years-long scheme to stage crashes with semi-trucks, the kind of activity that has historically pushed commercial rates up.


Nationally, the commercial auto line posted a net underwriting loss for the 15th straight year in 2025, with liability running a combined ratio above 100 since 2014. Carriers paying out more than they collect tend to raise rates and tighten underwriting.


Then there's the local picture. Hurricanes and flash flooding total vehicles in bulk, and potholed roads, heavy truck traffic on I-12 and I-10, and congested bridge corridors raise accident frequency.


Some relief may be coming. Louisiana shifted to a 51% bar rule for comparative fault on January 1, 2026, so a plaintiff found 51% or more at fault recovers nothing. Uninsured motorists are now barred from recovering the first $100,000 of bodily injury or property damage, up from the prior $15,000/$25,000. And a plan announced in September 2026 for PICA to take over commercial policies from Louisiana Citizens, with potential premium reductions of 15 to 40%, may help those specific policyholders. Changes like these usually take time to show up in pricing.

We explain each quote's limits, deductibles and exclusions in plain language, side by side.

3

Review the options together

4

Your policy starts, and we revisit the limits with you at every renewal as values change.

Bind and review yearly

Driver Standards That Help Lower Risk

You can't control jury verdicts or hurricane season. You can control who gets behind the wheel. Underwriters look closely at driver records, and a single employee with two recent at-fault accidents can affect what a carrier offers your whole company, or whether it will write you at all.


Strong driver standards typically include:


  1. Motor vehicle record checks before hiring, then at least annually. Many carriers set their own thresholds for violations and at-fault accidents.
  2. Minimum experience requirements, especially for anyone towing trailers or driving heavier units.
  3. A written vehicle use policy covering personal use, passengers, and phone use while driving.
  4. Telematics or dash cams. Camera footage can clear your driver quickly when the other party claims your truck caused the crash, which matters in a state with a staged-accident history.
  5. Regular safety training, from defensive driving courses to backing and trailer hookup refreshers.
  6. Documented maintenance logs for brakes, tires, and lights.


Write these rules down and enforce them consistently. A safety program that exists only on paper won't help you at renewal or in court. Carriers may reward documented programs with more favorable terms, and the roads around Covington and Slidell get a little safer when fewer fatigued or distracted drivers are out there.

Gaps Worth Knowing About

Distance from open water, the flood zone and the fire district all move the rate, sometimes street by street inside Covington.

The named-storm deductible is a percentage of the dwelling limit, so it is real money at claim time. Pairing the policy with your auto insurance usually lowers both.

Location and elevation

Deductibles and bundling

Common Questions About Louisiana Business Vehicle Coverage

Do I need a commercial policy for one truck? Often, yes. If the truck is titled to your business, carries tools or signage, or is used mainly for work, a personal policy may limit or exclude coverage.


Does my personal insurance cover business deliveries? Usually not. Most personal auto policies exclude delivering goods or food for pay, so a commercial policy or a specific delivery endorsement is typically needed.


Are my tools covered if someone breaks into my work van? Commercial auto generally covers the vehicle, not the contents. Inland marine or tool and equipment coverage typically fills that gap.


What happens if an employee wrecks their own car running a work errand? Their personal policy usually pays first. If a lawsuit targets your business or exceeds their limits, hired and non-owned auto coverage may protect you.


Can one bad driver raise my whole policy cost? It can. Carriers rate the entire schedule of drivers, so a single poor record may raise premiums or limit carrier options.


Do I need extra coverage for a borrowed trailer? If you haul someone else's trailer under a written agreement, trailer interchange coverage may be needed to protect against physical damage to it.

We explain each quote's limits, deductibles and exclusions in plain language, side by side.

3

Review the options together

4

Your policy starts, and we revisit the limits with you at every renewal as values change.

Bind and review yearly

Making the Right Choice for Your Fleet

Commercial auto coverage in Louisiana isn't something to guess at. The right policy matches how your trucks, trailers, and drivers actually work, carries limits that reflect today's lawsuit climate, and closes gaps like non-owned vehicles and equipment in the bed. Strong driver standards may help you hold onto better terms even when the market tightens.


As an independent agency, Aubert Insurance Agency compares options from multiple carriers in one place and walks you through what your policy covers and excludes before you sign. We've been part of the Covington and Slidell community since 1910, and we know the roads, the weather, and the businesses here.


Ready to see where your coverage stands? Start a Quote with Aubert Insurance Agency today, and let a local team that's been here for more than a century help you protect the vehicles that keep your business moving.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461









