













Abita Springs LA Business Insurance

Covington & Slidell Independent Insurance Agents

Abita Springs businesses can secure coverage by working with an independent agency that compares policies from multiple carriers. Aubert Insurance Agency has served the Northshore since 1910 from offices in Covington and Slidell. Owners start online, the team shops several carriers, and the business picks the plan that fits its risks, whether that is a cafe, brewery, trade, or festival booth.


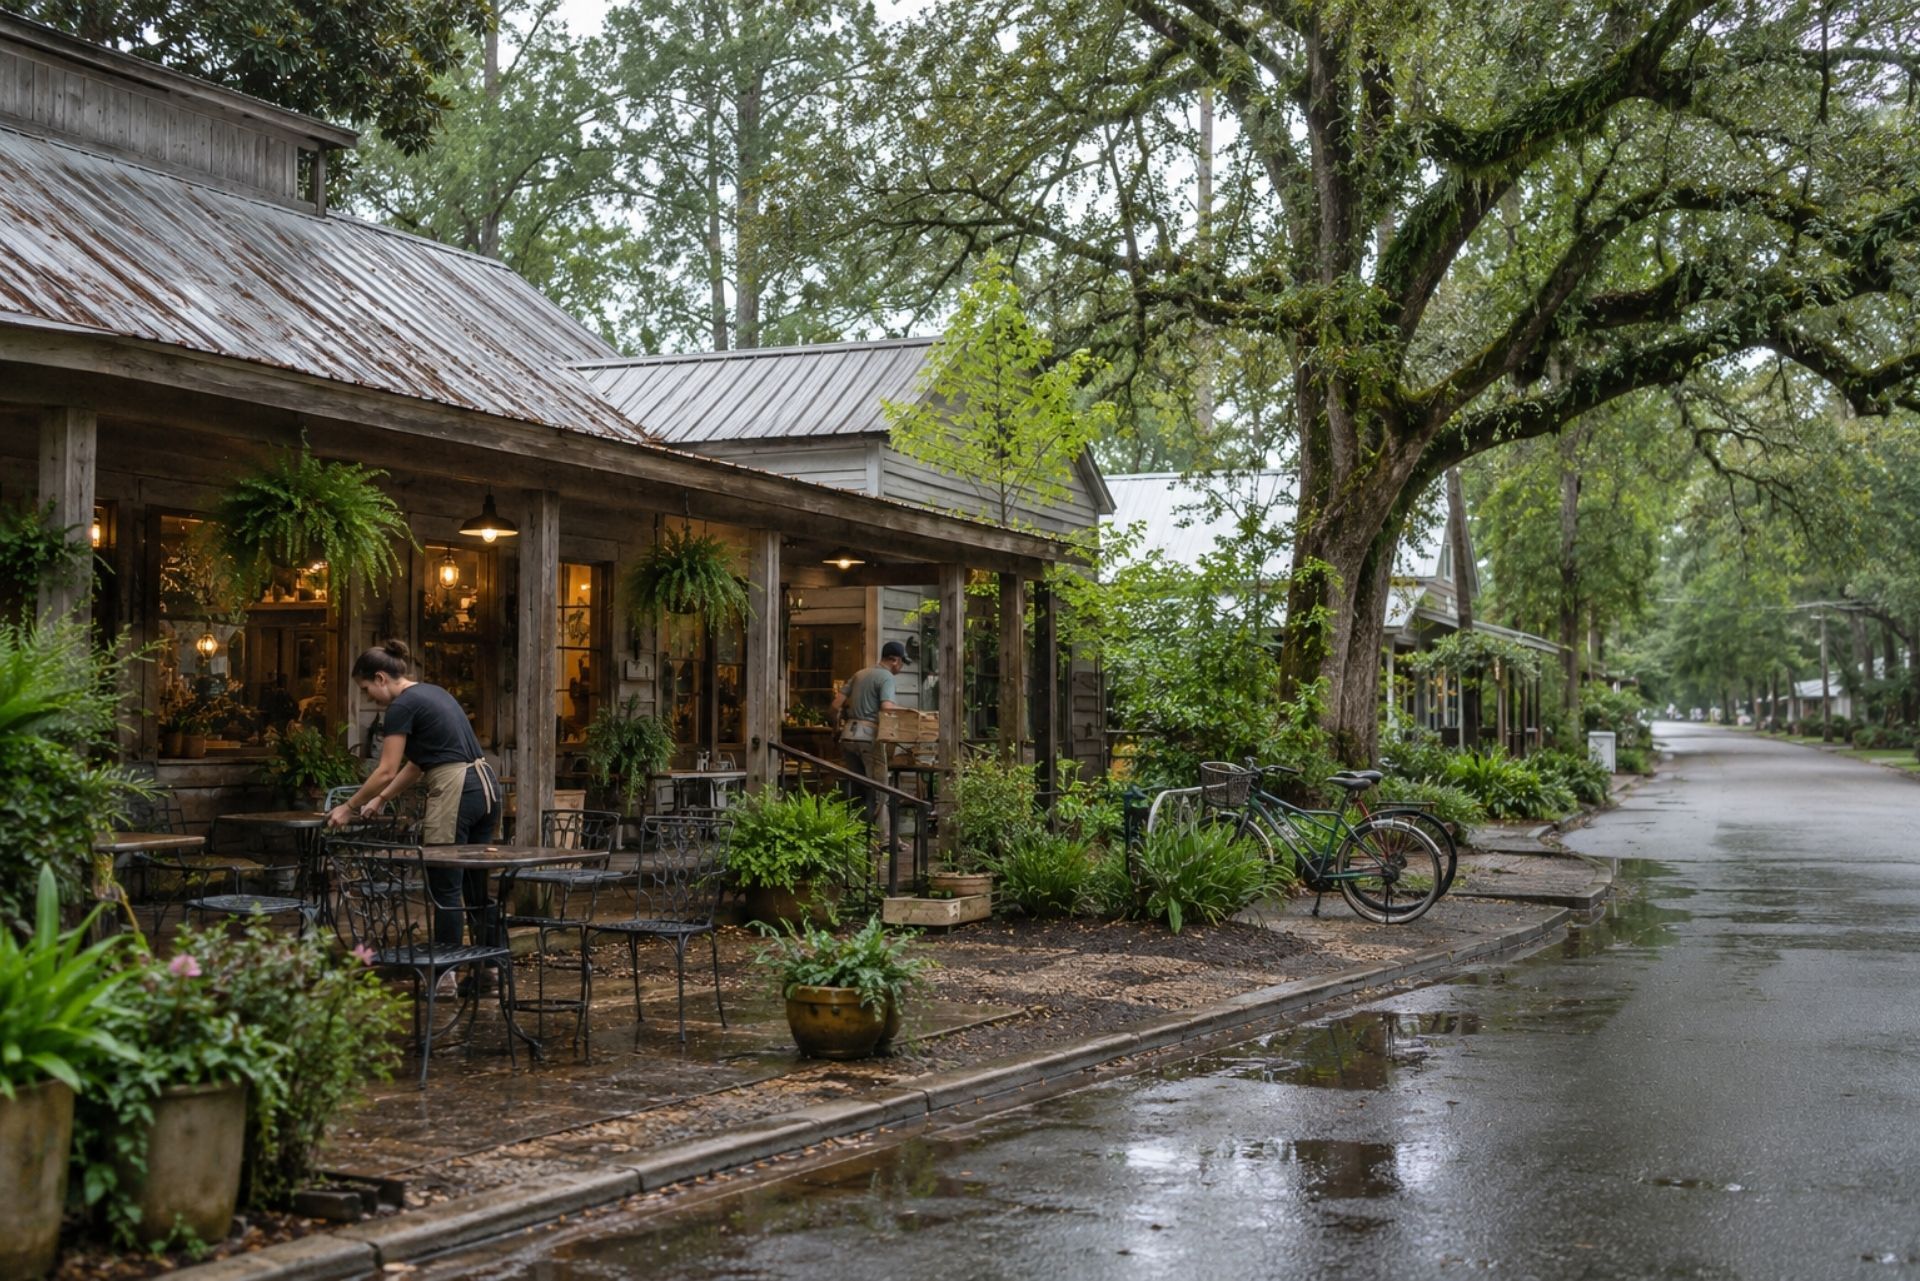
A cyclist rolls off the Tammany Trace, leans a bike against your porch railing, and trips on a loose board on the way in for an iced coffee. That one moment can test whether your policy was built for an Abita Springs business or copied from a generic template. This small town packs a lot of risk into a few blocks: trail traffic, brewing equipment, home workshops, and festival crowds that swell on weekends.


The good news is that coverage for each of these businesses is well understood. The tricky part is matching the right pieces together so nothing falls through the cracks. What follows walks through business insurance in Abita Springs, LA, for trailhead shops and cafes, breweries and food producers, home-based trades, and event and festival liability. It also covers some Louisiana regulatory changes from 2026 that affect what you pay and what you need to carry.

Understanding Business Insurance in Abita Springs

Most small businesses here start with a Business Owner's Policy (BOP). A BOP typically bundles general liability, commercial property, and business income coverage at a lower combined cost than buying each one separately. From there, you add pieces based on what you actually do: product liability for food makers, inland marine for tools, or liquor liability if you pour.


Costs vary widely. Small businesses in St. Tammany Parish typically pay between $121 and $605 per month for commercial property insurance as of October 2026. Building age, flood zone, and contents value drive most of that spread.


Two 2026 changes are worth knowing. Louisiana now requires insurers to give you a Rate Transparency Report at renewal that breaks down the specific cost elements of your premium. State regulators are also encouraging policyholders to shop around because rate decreases have started appearing after several hard years. Both changes favor owners who compare carriers instead of auto-renewing.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Many St. Tammany families end up with both: standalone coverage for the land, plus an umbrella over the home and vehicles.

Comparison: Standalone Liability vs. Umbrella Coverage

Understanding the Named Storm Deductible

A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.


There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.

Factor Standalone Liability Umbrella Policy
Underlying policy required No Yes, home and auto typically
When it pays First dollar of a covered claim After underlying limits run out
Typical use Vacant land, hunting tracts, specific risks Broad extra protection across policies
Cost structure Priced by acreage, use, and limit Priced by number of homes, cars, drivers
Scope Narrow, tied to named property or risk Wide, follows underlying coverage
Common limits $300,000 to $1 million $1 million and up

Insuring Trailhead Shops and Local Cafes

The Abita Springs Trailhead brings steady foot traffic, which is great for sales and also raises your exposure. Most claims we see in this category are slip-and-falls, not fires. Wet floors from melting ice, muddy trail shoes, uneven porch steps, and bikes parked in walkways all create premises liability risk.


For a retail shop or cafe near the trail, the core coverage usually looks like this:


  • General liability: Covers customer injuries and property damage you cause to others.
  • Commercial property: Protects your building (if owned), inventory, espresso machines, coolers, and furniture.
  • Business income: May replace lost revenue if a covered loss like a fire forces you to close temporarily.
  • Equipment breakdown: Often an add-on, and worth it if a dead walk-in cooler would spoil your stock.
  • Spoilage coverage: Important for cafes holding perishable inventory.


One common mistake is assuming your landlord's policy covers your stuff. It doesn't. Your lease probably requires you to carry your own liability and name the landlord as an additional insured. Read that clause before you sign.


Flood also deserves a mention. Standard commercial property policies typically exclude flood, and Abita Springs sits close to the Abita River. A separate flood policy is worth discussing even if your lender doesn't require one.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Risk Management for Breweries and Food Producers

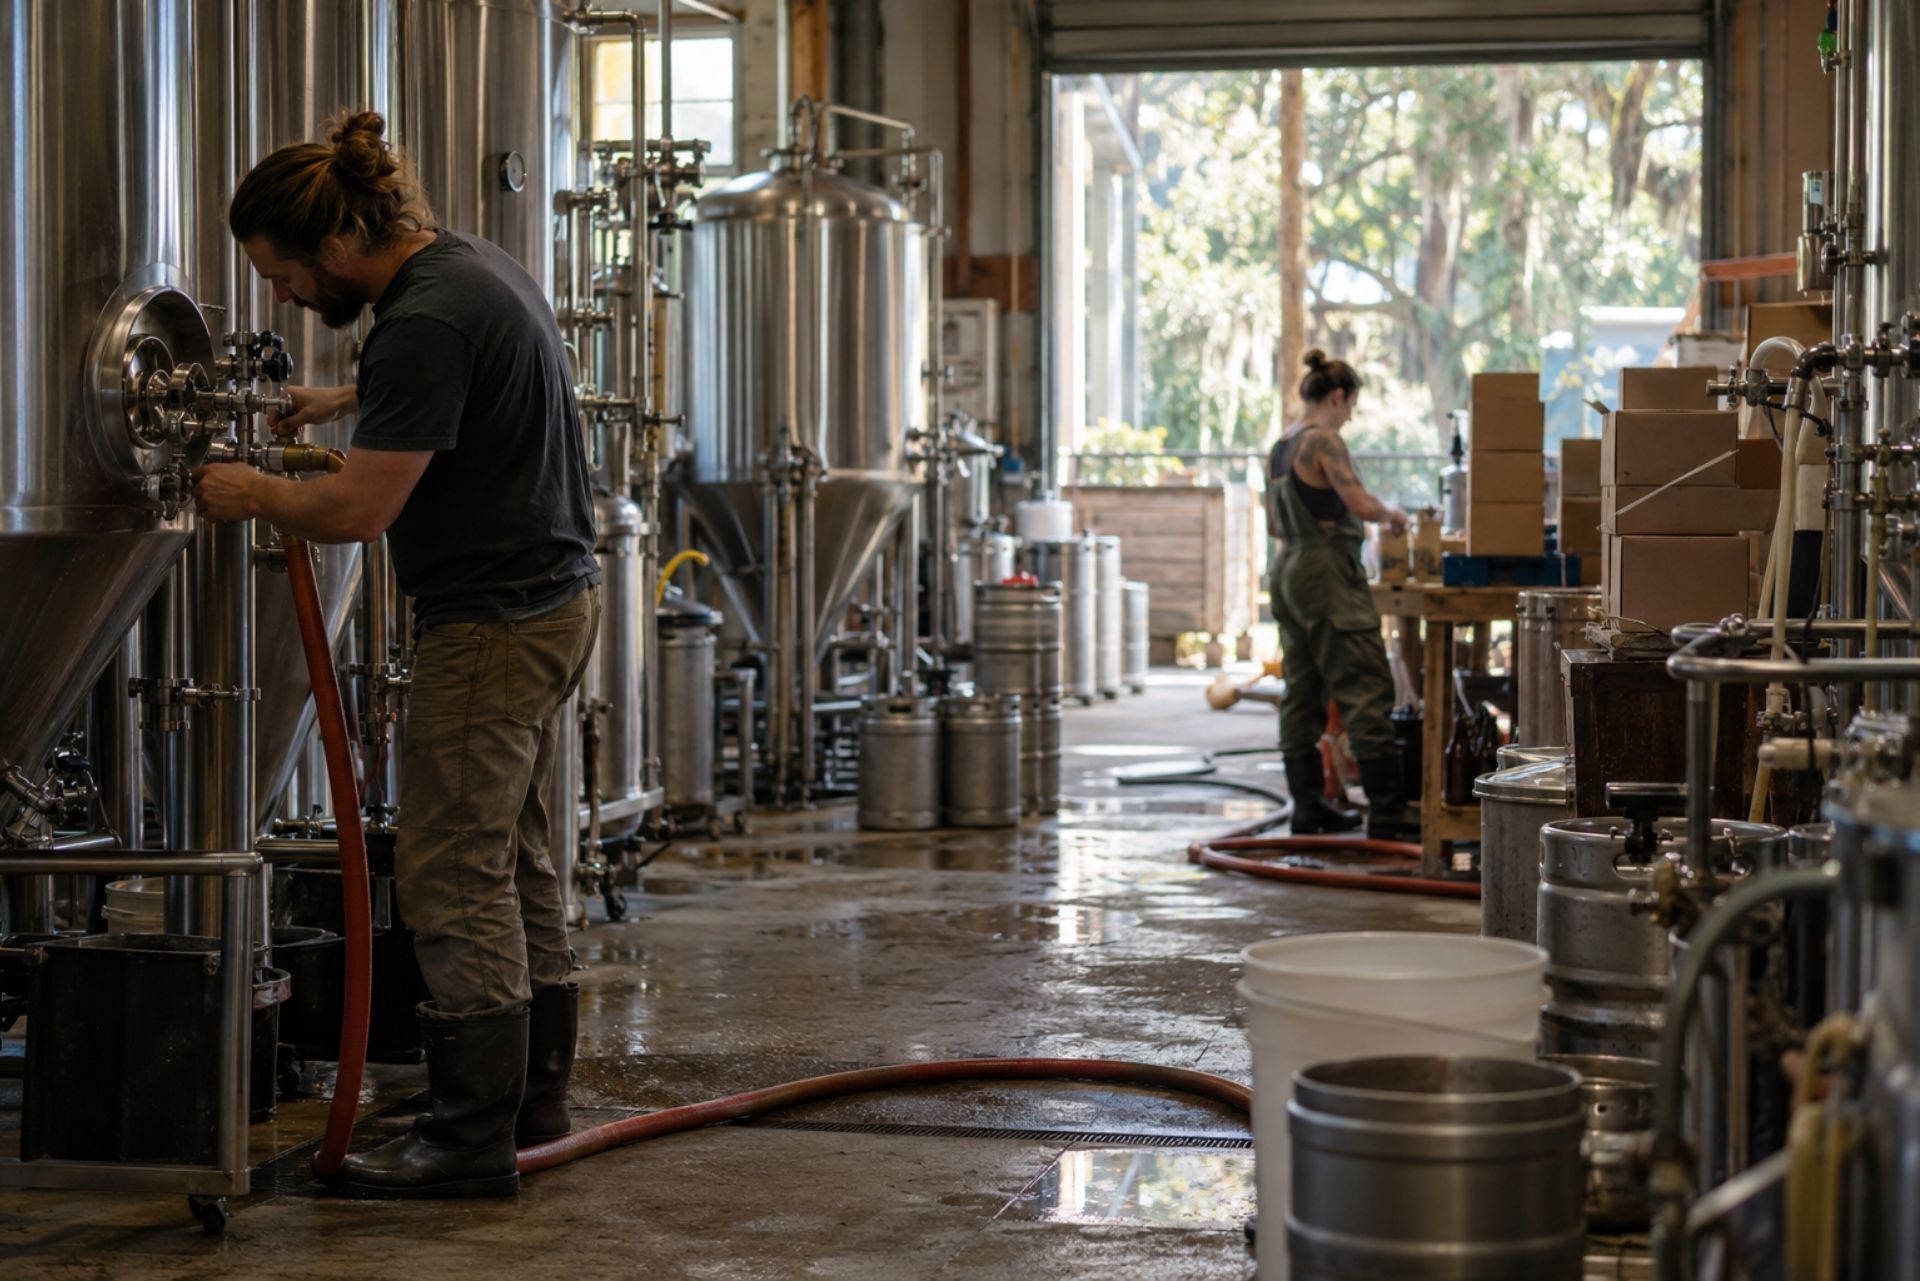
Abita Springs is known for brewing, and the industry keeps changing. The town's best-known brewer has become the Abita Beverage Group, focusing on contract manufacturing for over 15 beverage partners. That shift points to a growing local supply chain of co-packers, ingredient suppliers, and small brands, and each of them carries product risk.

Product Liability and Recalls

If someone gets sick from your hot sauce or a bottle shatters because of over-carbonation, product liability responds. Many small producers assume general liability covers this, and some policies do include products-completed operations. Limits may be too low, though. Product recall coverage is separate and typically excluded unless you add it. Recall expenses like notification, retrieval, and disposal can add up quickly.

Equipment and Contracts

Brewhouses, canning lines, and fermentation tanks need equipment breakdown coverage, since a standard property policy usually won't pay for mechanical failure. Contamination from a glycol leak or power loss may also be excluded unless you specifically add spoilage coverage.


Small home producers have more room to grow in 2026. Under Act 801, Louisiana home-prepared low-risk food producers saw their gross annual sales limit rise from $30,000 to $100,000, effective August 1, 2026. More sales mean more exposure, and a farmers market vendor doing $90,000 a year needs real product liability, not just hope.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Coverage for Home-Based Trades and Artisans

Abita has plenty of woodworkers, potters, electricians, and painters working out of garages and backyard sheds. Many of them assume their homeowners policy covers their business. It usually doesn't, at least not fully.


Homeowners policies typically cap business property at a small amount, often around a few thousand dollars, and that limit may drop even lower when equipment is away from the house. They also tend to exclude liability arising from business activities. If a client trips over a sander in your driveway, or a cabinet you installed falls off a wall, your homeowners carrier may deny the claim outright.


A business policy closes those gaps in a few ways. Home-based business endorsements or a standalone BOP cover tools, inventory, and customer visits. Inland marine, sometimes called tools and equipment coverage, follows your gear to job sites and in your truck. General liability covers damage you cause at a client's property, and commercial auto applies if your vehicle is titled to the business or used heavily for work.


Licensed contractors face a new reason to get this right. Act 757 gave the Louisiana State Licensing Board for Contractors increased authority to revoke licenses when insurance doesn't match specific work subclassifications. If you're licensed for electrical work but your liability policy is written for general carpentry, that mismatch could now cost you your license.

Event and Festival Liability for Town Gatherings

Abita's town events draw serious crowds. Vendors at gatherings like the Water Festival or artists painting during En Plein Air often get the same request from organizers: send a certificate of insurance naming us as additional insured. If your annual policy can't do that, short-term event coverage can.


For organizers, the risks are broader. You're responsible for the grounds, the stage, the crowd, and sometimes alcohol. Typical coverage includes:


  1. Special event general liability for attendee injuries and property damage
  2. Host liquor liability if alcohol is served or sold
  3. Hired and non-owned auto if volunteers run errands in personal vehicles
  4. Cancellation coverage for weather. A spring thunderstorm can wipe out deposits fast


For vendors, one-day or weekend policies are usually available at modest cost. If you work five or more events a year, though, an annual policy often costs less overall and saves you from buying coverage at the last minute. The gap we see most often is a food vendor with general liability but no products coverage, selling food to hundreds of strangers.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Comparing Essential Coverage Options

General liability and professional liability get confused constantly. One covers physical harm, and the other covers mistakes in advice or service. Here's how they differ for Louisiana businesses:

Feature General Liability Professional Liability (E&O)
Covers Bodily injury, property damage, advertising injury Errors, negligence, bad advice, missed deadlines
Typical claim Customer slips in your cafe Client loses money from your design error
Who usually needs it Nearly every business with customers or a location Consultants, designers, bookkeepers, inspectors
Often required by Landlords, festivals, contractor licensing Client contracts
Policy trigger Usually occurrence-based Usually claims-made
Abita example Bike shop customer injured by display rack Event planner books the wrong venue date

A brewery or cafe may never need professional liability. A home-based interior designer may need both. The claims-made detail matters: if you cancel a professional liability policy, you may lose coverage for past work unless you buy tail coverage.

Common Questions About Abita Springs Business Insurance

Do I need insurance for a home business? Most likely, yes. Homeowners policies typically limit or exclude business property and business-related liability, so a home-based endorsement or business policy fills that gap.


Is general liability required by law in Louisiana? Not for every business, but licensed contractors, landlords, and event organizers commonly require it. Workers' compensation is generally required once you have employees.


Can I buy coverage for just one festival weekend? Yes. Short-term event and vendor liability policies are typically available for single events.


Does my policy cover flooding? Standard commercial property policies usually exclude flood. You'll need a separate flood policy.


Why did my renewal price change? Starting in 2026, your insurer must provide a rate transparency report at renewal explaining the cost elements of your premium. Ask your agent to walk through it with you.


Should I shop my policy every year? With Louisiana rates beginning to ease in some lines, comparing quotes at renewal is a smart habit.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Making the Right Choice for Your Local Business

Every business in Abita Springs carries a different mix of risk. A trail cafe worries about slips and spoiled stock. A beverage producer worries about recalls. A home woodworker needs protection for tools, and a festival vendor needs a certificate by Friday. Picking coverage piece by piece from a single carrier can leave expensive gaps.


That's where an independent agency earns its keep. Aubert Insurance Agency has insured what matters on the Northshore since 1910, from offices in Covington and Slidell. Because we're independent, we compare rates from multiple leading carriers in one place rather than pushing one company's product. We also take the time to explain what your policy covers, what it excludes, and why, since a policy is a legally binding contract you should understand before you need it.


The process stays simple: start online, we shop for you, and you pick the plan that fits. Whether you're opening near the trailhead or finally moving your craft out of the garage, coverage built for Abita Springs gives you room to focus on the work.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
