

Covington & Slidell Independent Insurance Agents
Protecting Your Assets with a Business Owners Policy
MNot every BOP is built the same. These features deserve a close look before you sign:
Equipment breakdown: May cover electrical or mechanical failure, like a power surge frying an imaging machine's circuit board. Standard property forms often exclude this.
Business income: Typically replaces lost revenue and continuing expenses if a covered loss forces you to close temporarily.
Spoilage coverage: May pay for vaccines or medications lost when refrigeration fails during an outage.
Flood: Usually excluded from a BOP. Practices in flood-prone parts of St. Tammany often need a separate flood policy.
Named storm deductibles: Louisiana policies frequently carry percentage-based hurricane deductibles, so know the dollar figure before storm season.
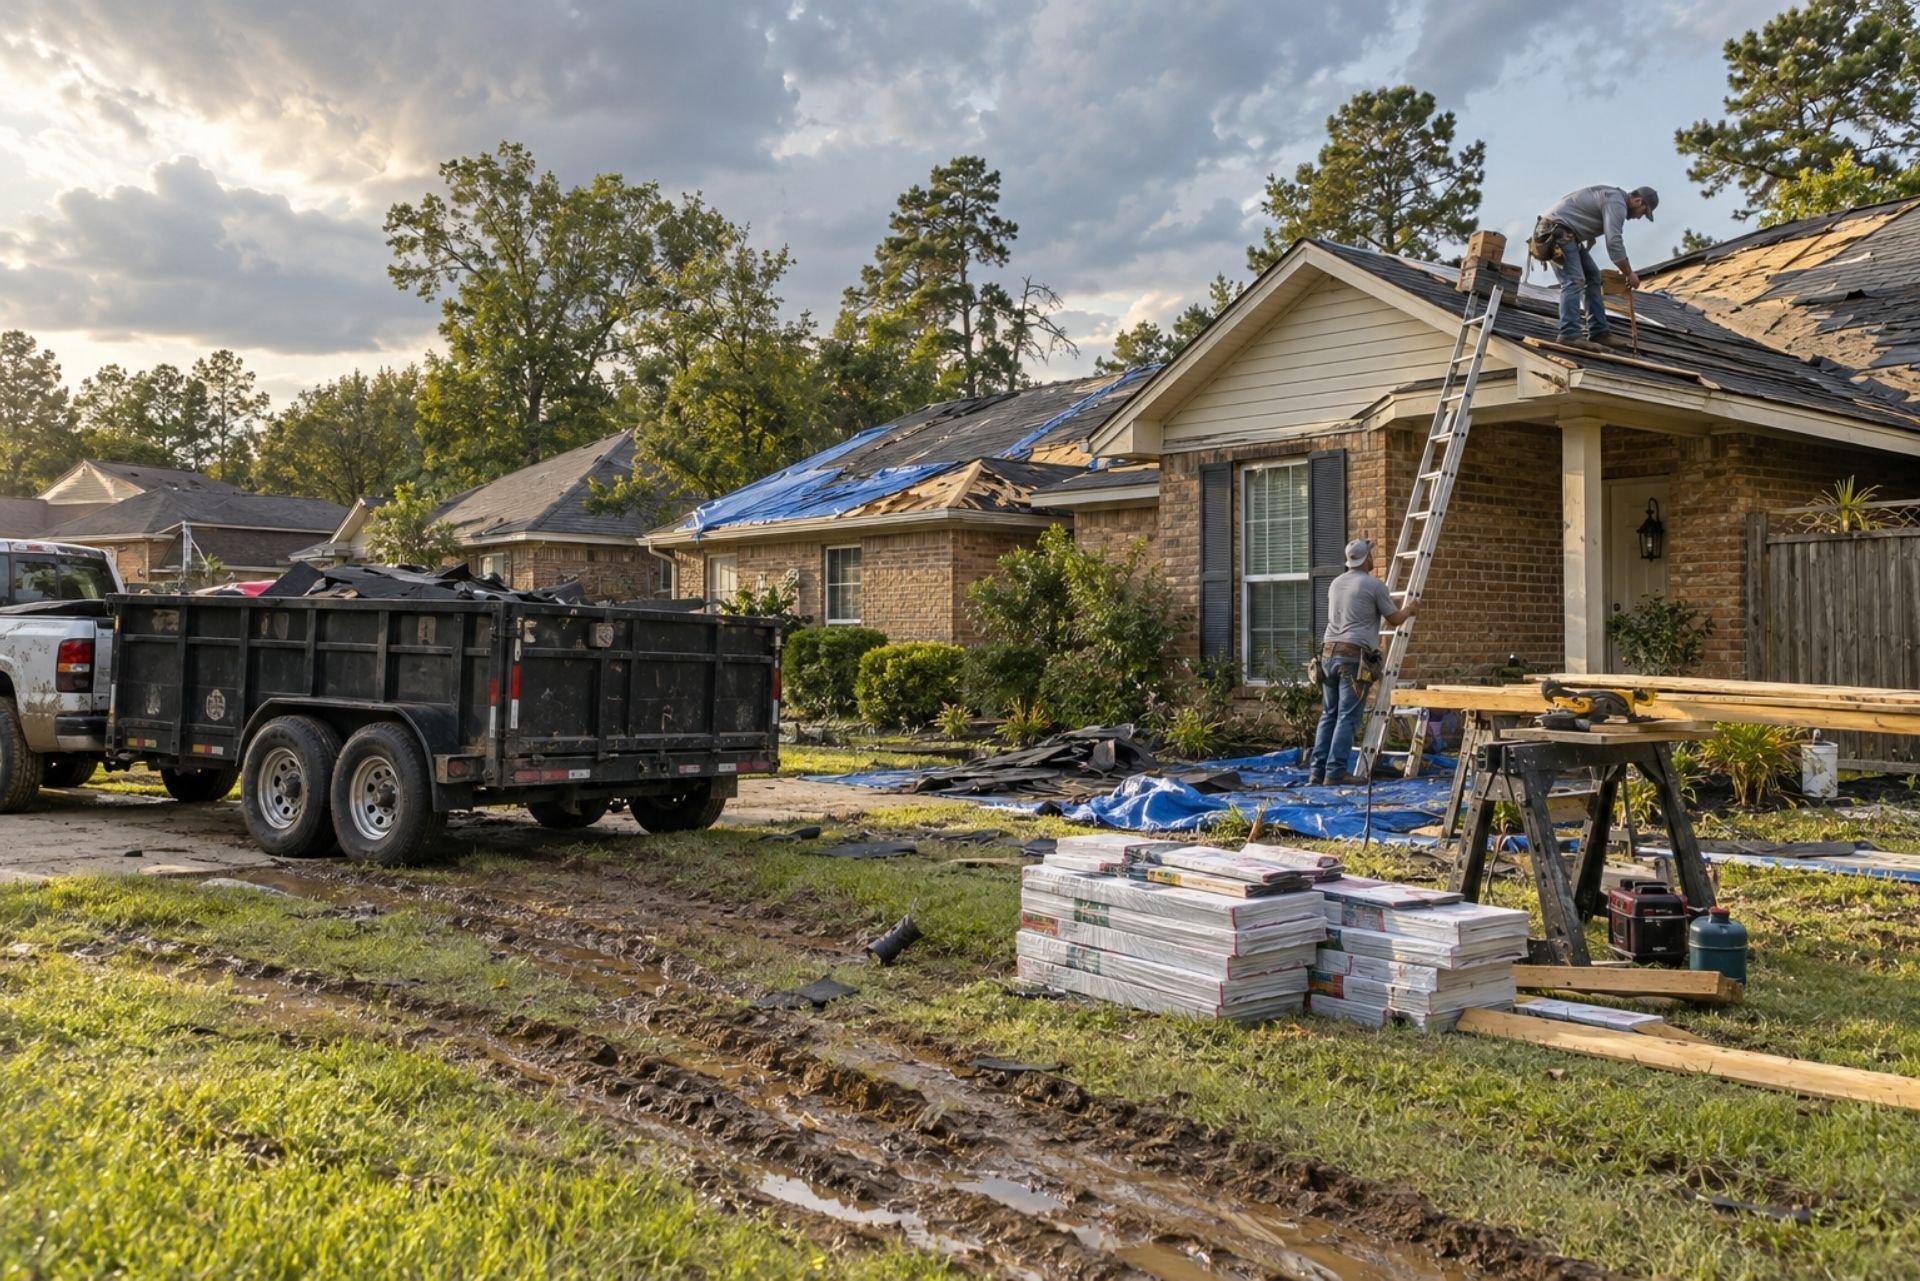
Spring storms roll across the ArkLaTex fast, and contractors in Shreveport and Bossier City often feel it first. One hail line can bring a month of roofing calls, while new retail and office projects keep interior crews busy year-round. Your insurance has to keep pace with both kinds of work, plus the miles your trucks cover between parishes.
Essential Insurance for Shreveport and Bossier City Contractors
Contractors in North Louisiana typically need three core policies: General Liability for property damage and injury claims, Workers Compensation for crew injuries, and Inland Marine for tools and materials on the move. Together they cover storm repair work and commercial growth projects. Aubert Insurance Agency has been insuring Louisiana businesses since 1910.
That trio is the foundation, not the whole house. Your trade, crew size, and project mix decide which add-ons matter. A two-person handyman outfit in Bossier City needs something very different from a 25-person commercial framing company bidding work in downtown Shreveport.
State rules have also tightened. As of August 1, 2026, residential, home improvement, and mold remediation contractors must carry at least $500,000 in general liability insurance under Act 757. If your current policy carries a lower limit, it may no longer meet licensing requirements, and permit offices check.
The upside of working with an independent agency is choice. Aubert compares rates and coverage forms from multiple carriers, then walks you through what each contract actually covers and excludes. Shreveport LA contractors insurance gets far less confusing when someone explains the fine print before a claim exposes it.
On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Understanding the Named Storm Deductible
A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.
There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.
Navigating North Louisiana Hail and Tornado Repair Work
Storm work in Caddo and Bossier parishes is profitable, but it carries a risk many contractors miss: the materials sitting on the jobsite. Picture this: you drop $14,000 in shingles, underlayment, and flashing at a Southern Hills home on Tuesday. A second storm cell comes through Wednesday night, and half of it blows into the neighbor's yard or gets soaked.
Your General Liability policy usually won't pay for that. GL covers damage you cause to others, not your own uninstalled materials. That's where two coverages come in:
- Builders Risk: Typically covers a structure under construction or major renovation, including materials on-site, against perils like wind, hail, fire, and theft.
- Installation Floater: Generally designed for trades installing specific items (HVAC units, windows, roofing systems) and may cover those materials from the supplier until they're permanently installed and accepted.
Licensing matters here too. A specific LSLBC classification is required for residential roofing projects over $7,500, which covers nearly every full roof replacement after a hail event. Storm chasers from out of the area sometimes skip this step. Local contractors who hold the license and carry proper coverage can point to both when homeowners compare bids.
One common mistake: buying a floater with a per-job limit lower than your largest storm jobs. Check that number before the next hail season, not after.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Being named as a certificate holder just means someone receives proof. Being named as an additional insured means your policy may actually defend and pay for that party if they're sued because of your work. General contractors, developers, and property managers ask for this because they get pulled into lawsuits over subcontractor mistakes constantly.
Read the contract language closely. Some agreements require "primary and noncontributory" wording or completed operations coverage for the additional insured, which needs specific endorsements. Many contractors sign a subcontract agreeing to these terms without checking whether their policy includes them. If a claim comes in and the endorsement isn't there, you may be in breach of contract on top of facing the lawsuit.
Actual Cash Value Versus Replacement Cost
Understanding the Valuation Gap
Actual Cash Value (ACV) pays what the damaged item was worth at the time of loss, which means depreciation comes off the top. For an older roof, that deduction can be large. If your roof is 18 years into a 25-year lifespan, an ACV settlement may cover only a fraction of what a new roof costs, and you pay the rest along with your deductible.
Replacement Cost (RC) typically pays what it costs to replace damaged property with new materials of like kind and quality, without subtracting for age. Some carriers pay the ACV portion first and release the remaining amount once repairs are finished, so keep your receipts. On older Bogalusa homes, carriers may offer RC on the dwelling but apply ACV to the roof only. That split is common and easy to miss, so read the roof settlement language before you sign.
There's also a newer option. Louisiana's Act 480 created stated-value policies that let homeowners insure a property for a specific declared amount, such as a mortgage balance, rather than full replacement cost. That may help when rebuilding cost far exceeds what you need protected, but it also means you could be underinsured after a total loss.
Bossier City Growth and Commercial Tenant Build-Outs
The construction demand around Shreveport-Bossier is real. Amazon is investing an estimated $18 billion in three data centers in the Shreveport-Bossier MSA, a project expected to support roughly 1,500 construction jobs. Statewide, Louisiana led the nation with 7.7% year-over-year construction employment growth as of June 2026.
That growth pulls new retail, restaurant, and office tenants into the market, and every one needs a build-out. In Shreveport, recent planning approvals include a new Public Safety Facility on St. Vincent Ave and several restaurant drive-throughs on Mansfield Road.
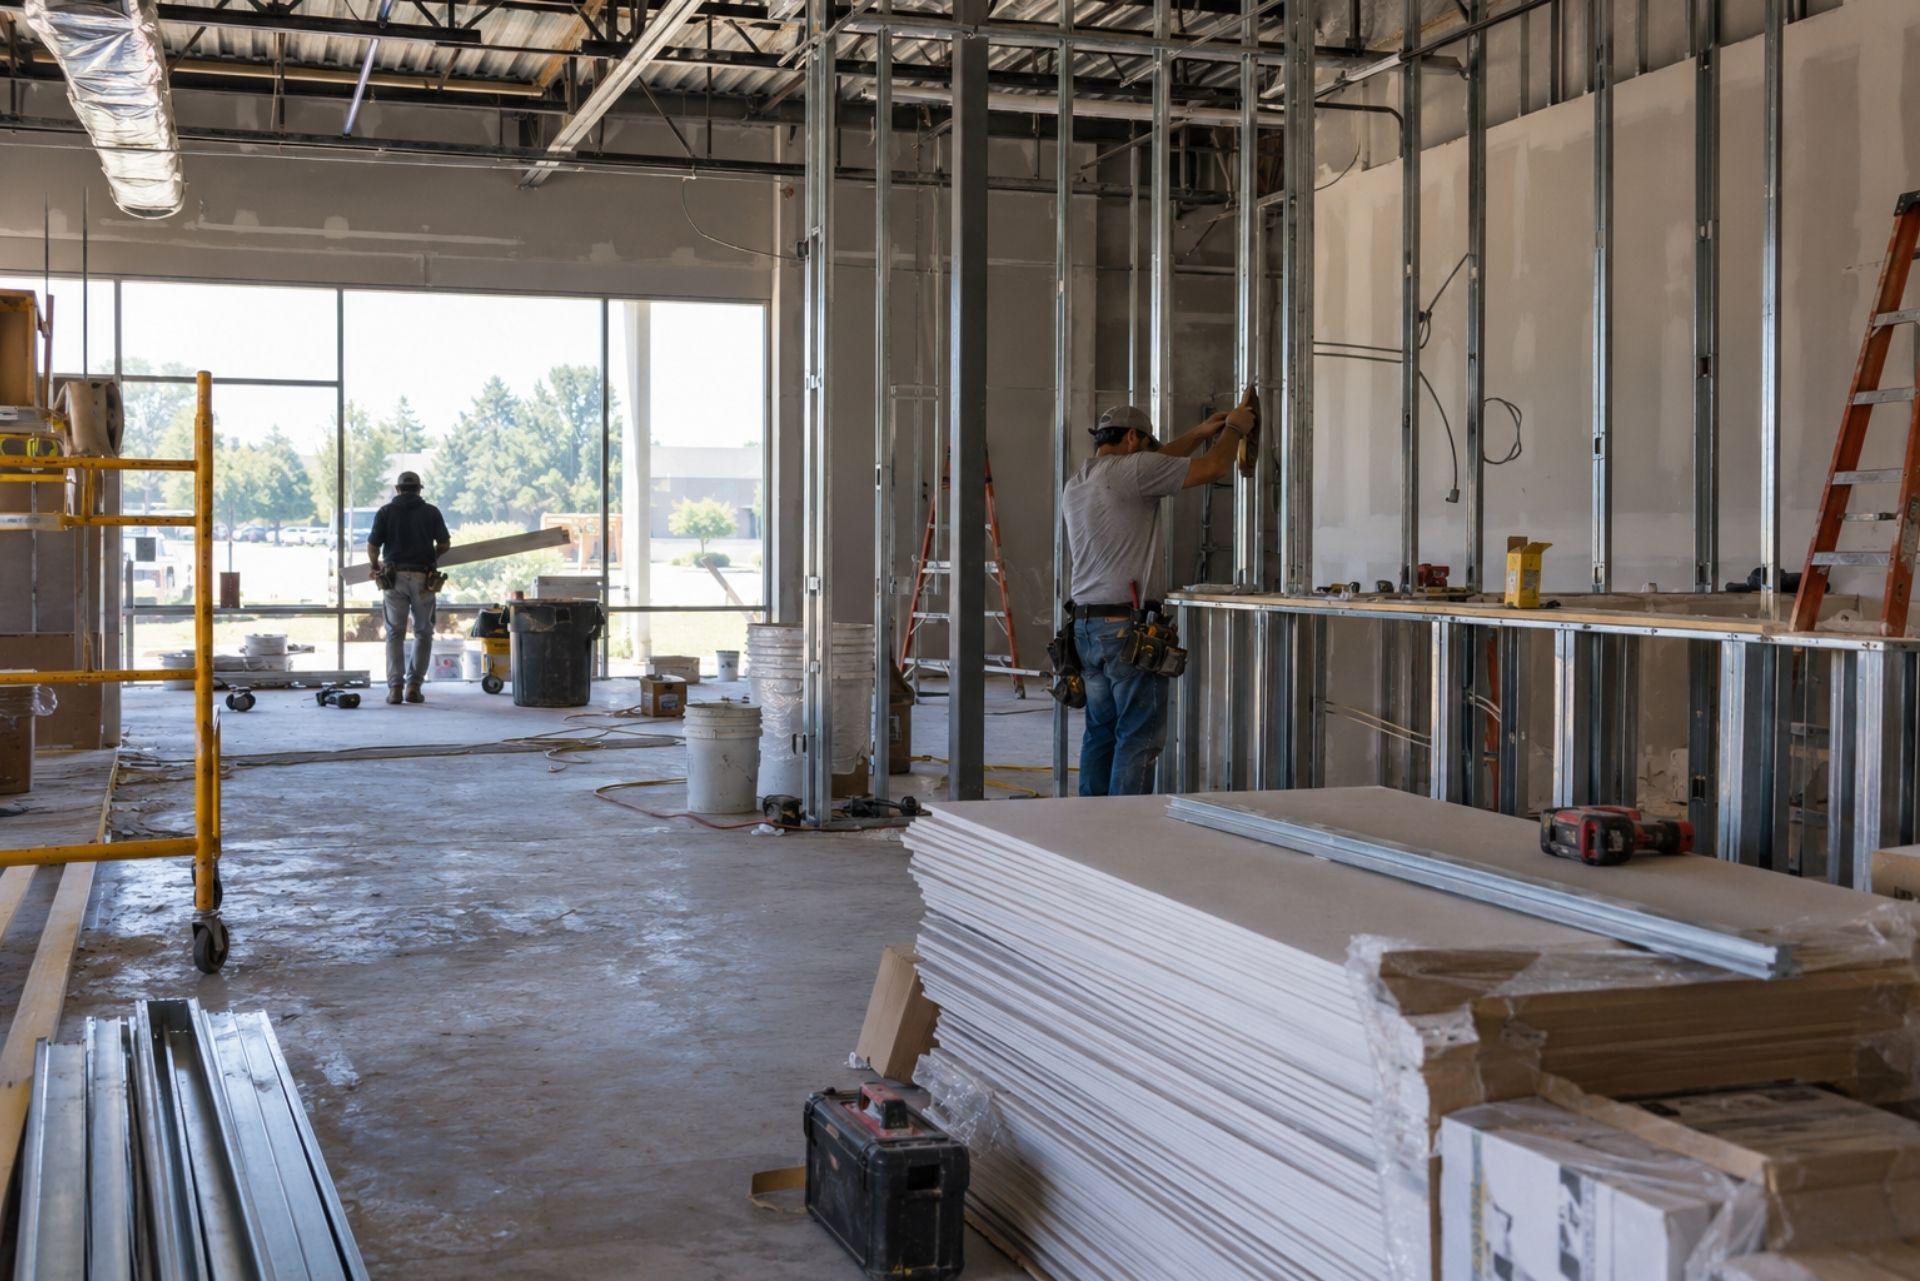
Interior contractors face a specific liability problem. You're working inside an existing building owned by someone else, often next to occupied units. Cut into a sprinkler line while framing a new suite, and water can ruin the dentist's office next door. That claim lands on your General Liability policy.
Landlords and general contractors typically require you to name them as additional insureds and may ask for waiver of subrogation and primary/non-contributory wording. Read the lease or subcontract language carefully. Some GL policies include these endorsements automatically, while others require you to add them. Bossier City's two-week average review time for commercial plans assumes your licensing and insurance proofs are verified, so a missing certificate can stall a whole project.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Evaluating Wind and Tree Exposure Risks
Pine and oak trees are part of why people love living in the Pearl River area. They're also a leading cause of roof claims after tropical storms and severe thunderstorms. A single limb through a roof can open the house to water damage that runs far beyond the cost of the roof repair.
Carriers have noticed. In 2026, more insurers are making trimming of limbs that touch or hang over a roof a condition of renewal. A drive-by or aerial inspection may flag overhanging branches, and you could receive a notice giving you a deadline to fix it. Ignoring that letter can lead to nonrenewal, which makes finding new coverage harder.
The roof itself is the other half of the wind picture. Louisiana offers incentives for stronger roofs, and the state's wind mitigation program details explain how certain construction features can lower your premium. Beginning January 1, 2027, Louisiana insurers must apply a premium reduction of 16% to 49% to the hurricane portion for homes with a certified FORTIFIED roof. If you're planning a roof replacement anyway, it may make sense to price out FORTIFIED certification at the same time.
Also review your named storm or wind deductible. In this part of Louisiana, it's often a percentage of the dwelling limit rather than a flat dollar amount, so a 5% deductible on a $250,000 home means $12,500 out of pocket.
Your belongings
Personal property covers furniture, clothing, tools and electronics. Jewellery, firearms and silver carry low internal caps, so we schedule those items separately when they are worth more than the cap.
Farm Equipment and Machinery Protection
Tractors, bush hogs, UTVs, and zero-turn mowers are where a lot of Pearl River landowners find gaps. Personal property coverage on a homeowners policy may cover some yard equipment, but it often limits or excludes motorized vehicles and items used for farming or business purposes.
Options depend on how you use the equipment:
- Hobby or property maintenance use: An endorsement or scheduled item on the homeowners policy may work.
- Small-scale farming or hay production: A farm or ranch policy, or an inland marine/equipment floater, typically fits better.
- Off-road vehicles like UTVs: These often need their own policy, especially if driven off your property.
Keep serial numbers and photos of every machine. Theft of tractors and trailers from rural lots is a real claim type, and documentation speeds up recovery.
Managing Crews That Travel Across Parish Lines
A typical week for a mid-size crew might start in Shreveport, swing to a Benton job on Wednesday, and finish in Minden by Friday. Every mile between Caddo, Bossier, and Webster parishes adds exposure, both to your vehicles and to the gear riding in them.
Commercial Auto covers vehicles your business owns or leases. It typically protects against liability if your driver causes an accident, plus physical damage to the truck itself. Hired and Non-Owned Auto (HNOA) fills a gap many owners don't see coming. If your foreman runs to the supply house in his own pickup and rear-ends someone, his personal policy may deny the claim because he was working, and the injured driver may come after your business.
Permitting gets more complicated across boundaries, too. Projects outside Bossier City limits that tap city utilities fall into a "Dual Permit Zone," requiring submittals to both the Bossier Parish Permit Office and the Bossier City Permits Department. Expect to supply insurance certificates to both.
Don't forget the trailer full of tools. Inland Marine coverage is generally recommended for equipment in transit between jobsites in different parishes, since standard auto and property policies often exclude it once it leaves your shop.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Comparing Common Contractor Coverage Options
Here's how the three core policies stack up in plain terms. Coverage specifics vary by carrier and policy form.
| Coverage | What It Typically Pays For | Example Claim | Who Usually Requires It |
|---|---|---|---|
| General Liability | Damage or injury you cause to others | A ladder falls and cracks a client's tile floor | State licensing, GCs, landlords |
| Inland Marine | Your tools, equipment, and materials on the move or on-site | Generator stolen from a Bossier City jobsite | Lenders, equipment lessors |
| Workers Compensation | Medical bills and lost wages for injured employees | Roofer falls during a hail repair | Louisiana law for most employers |
The value difference is about whose loss gets covered. GL protects other people's property and bodies. Inland Marine protects your stuff. Workers Comp protects your people. Most contractors need all three, and skipping one tends to show up as an uncovered claim at the worst possible time.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Evaluating Wind and Tree Exposure Risks
Pine and oak trees are part of why people love living in the Pearl River area. They're also a leading cause of roof claims after tropical storms and severe thunderstorms. A single limb through a roof can open the house to water damage that runs far beyond the cost of the roof repair.
Carriers have noticed. In 2026, more insurers are making trimming of limbs that touch or hang over a roof a condition of renewal. A drive-by or aerial inspection may flag overhanging branches, and you could receive a notice giving you a deadline to fix it. Ignoring that letter can lead to nonrenewal, which makes finding new coverage harder.
The roof itself is the other half of the wind picture. Louisiana offers incentives for stronger roofs, and the state's wind mitigation program details explain how certain construction features can lower your premium. Beginning January 1, 2027, Louisiana insurers must apply a premium reduction of 16% to 49% to the hurricane portion for homes with a certified FORTIFIED roof. If you're planning a roof replacement anyway, it may make sense to price out FORTIFIED certification at the same time.
Also review your named storm or wind deductible. In this part of Louisiana, it's often a percentage of the dwelling limit rather than a flat dollar amount, so a 5% deductible on a $250,000 home means $12,500 out of pocket.
Your belongings
Personal property covers furniture, clothing, tools and electronics. Jewellery, firearms and silver carry low internal caps, so we schedule those items separately when they are worth more than the cap.
Farm Equipment and Machinery Protection
Tractors, bush hogs, UTVs, and zero-turn mowers are where a lot of Pearl River landowners find gaps. Personal property coverage on a homeowners policy may cover some yard equipment, but it often limits or excludes motorized vehicles and items used for farming or business purposes.
Options depend on how you use the equipment:
- Hobby or property maintenance use: An endorsement or scheduled item on the homeowners policy may work.
- Small-scale farming or hay production: A farm or ranch policy, or an inland marine/equipment floater, typically fits better.
- Off-road vehicles like UTVs: These often need their own policy, especially if driven off your property.
Keep serial numbers and photos of every machine. Theft of tractors and trailers from rural lots is a real claim type, and documentation speeds up recovery.
Common Questions About Louisiana Contractor Insurance
These are the questions contractors in North Louisiana ask most when setting up or reviewing a policy
Does my personal auto policy cover my work truck?
Usually not, especially if the truck is titled to your business or used mainly for jobs. Personal policies often exclude business use, so a Commercial Auto policy is typically the right fit.
What happens if a storm destroys materials before I finish the job?
Without Builders Risk or an Installation Floater, you'll likely absorb the loss yourself. General Liability generally won't cover your own uninstalled materials.
Do I need insurance if I only use subcontractors?
Yes. You still need General Liability for your own operations, and if a sub lacks Workers Comp, the injury claim may fall back on you, so always collect their certificates.
How much General Liability do I need in Louisiana now? Residential, home improvement, and mold remediation contractors need at least $500,000 as of August 1, 2026. Commercial contracts often demand $1 million or more per occurrence.
Can one policy cover my work in Caddo, Bossier, and Webster parishes? Yes, most contractor policies apply statewide. The key is making sure your vehicles, tools, and limits fit how far your crews actually travel.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Protecting Your Business in North Louisiana
The Shreveport-Bossier market is giving contractors more opportunity than it has in years. Louisiana's construction sector added 10,500 jobs between June 2025 and June 2026, and the area is forecast to add 2,500 nonfarm jobs in 2027. More work means more certificates, more contract requirements, and more chances for a coverage gap to cost you a job or a claim.
Before your next bid, sit down with a map of where your crews actually went last year. Count the parishes, the vehicles, the storm jobs, and the tenant build-outs. Then compare that picture to what your policies cover. Ask a few pointed questions:
- Does my GL limit meet the new $500,000 minimum, or what my commercial contracts require?
- Are my materials protected before installation?
- Is every employee driving for work covered under Commercial Auto or HNOA?
- Does my Inland Marine follow tools across parish lines?
Aubert Insurance Agency makes this review simple. Start online, let the team shop multiple carriers for you, then pick the plan that matches your work, with a clear explanation of exclusions along the way. Coverage built around your actual routes and projects beats a generic contractor package every time. Ready to see your options? Start a Quote today.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.

Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.

Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.

Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.

Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.

Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

Residential General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Trade Contractors
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.
Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.










Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Visit
614 E. Boston St., Covington, LA 70433 — Get Directions
58418 Tyler Drive, Slidell, LA 70461 — Get Directions


