

Covington & Slidell Independent Insurance Agents
Protecting Your Assets with a Business Owners Policy
MNot every BOP is built the same. These features deserve a close look before you sign:
Equipment breakdown: May cover electrical or mechanical failure, like a power surge frying an imaging machine's circuit board. Standard property forms often exclude this.
Business income: Typically replaces lost revenue and continuing expenses if a covered loss forces you to close temporarily.
Spoilage coverage: May pay for vaccines or medications lost when refrigeration fails during an outage.
Flood: Usually excluded from a BOP. Practices in flood-prone parts of St. Tammany often need a separate flood policy.
Named storm deductibles: Louisiana policies frequently carry percentage-based hurricane deductibles, so know the dollar figure before storm season.
Ponchatoula drivers need Louisiana's required liability coverage plus protections matched to local risk. That means planning for long I-55 commutes over the Manchac swamp, crash-prone Highway 22 traffic, trucks that may split time between farm work and errands, and a parish where uninsured drivers are common. Uninsured motorist coverage deserves a close look.
Ponchatoula sits at an unusual crossroads. You can be stuck behind a tractor on a rural parish road in the morning and merge into elevated interstate traffic headed for New Orleans by lunch. A policy built for a suburban driver who rarely leaves town often leaves gaps here. This guide walks through the risks that shape a smart Ponchatoula auto insurance plan, from the swamp bridge to the strawberry fields.
Navigating Ponchatoula Car Insurance Requirements
Louisiana requires every registered vehicle to carry liability insurance that pays for injuries and property damage you cause to others. That's the legal floor. It covers the other driver's medical bills and car repairs up to your policy limits. It does nothing for your own vehicle, your own injuries or your passengers if someone else causes the wreck and can't pay.
The state minimum was written for the whole state, not for a driver who crosses a long elevated bridge twice a day. A serious multi-car crash on the interstate can produce medical and repair bills that blow past minimum limits quickly. When that happens, the injured party can pursue you personally for the difference.
Here's what that means for you: think of the state requirement as a starting point. Most Ponchatoula households should review three things beyond it:
- Liability limits high enough to protect your savings and home
- Collision and comprehensive for vehicles you couldn't easily replace
- Uninsured and underinsured motorist coverage for your own protection
On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Understanding the Named Storm Deductible
A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.
There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.
Commuting Over the Manchac Swamp on I-55
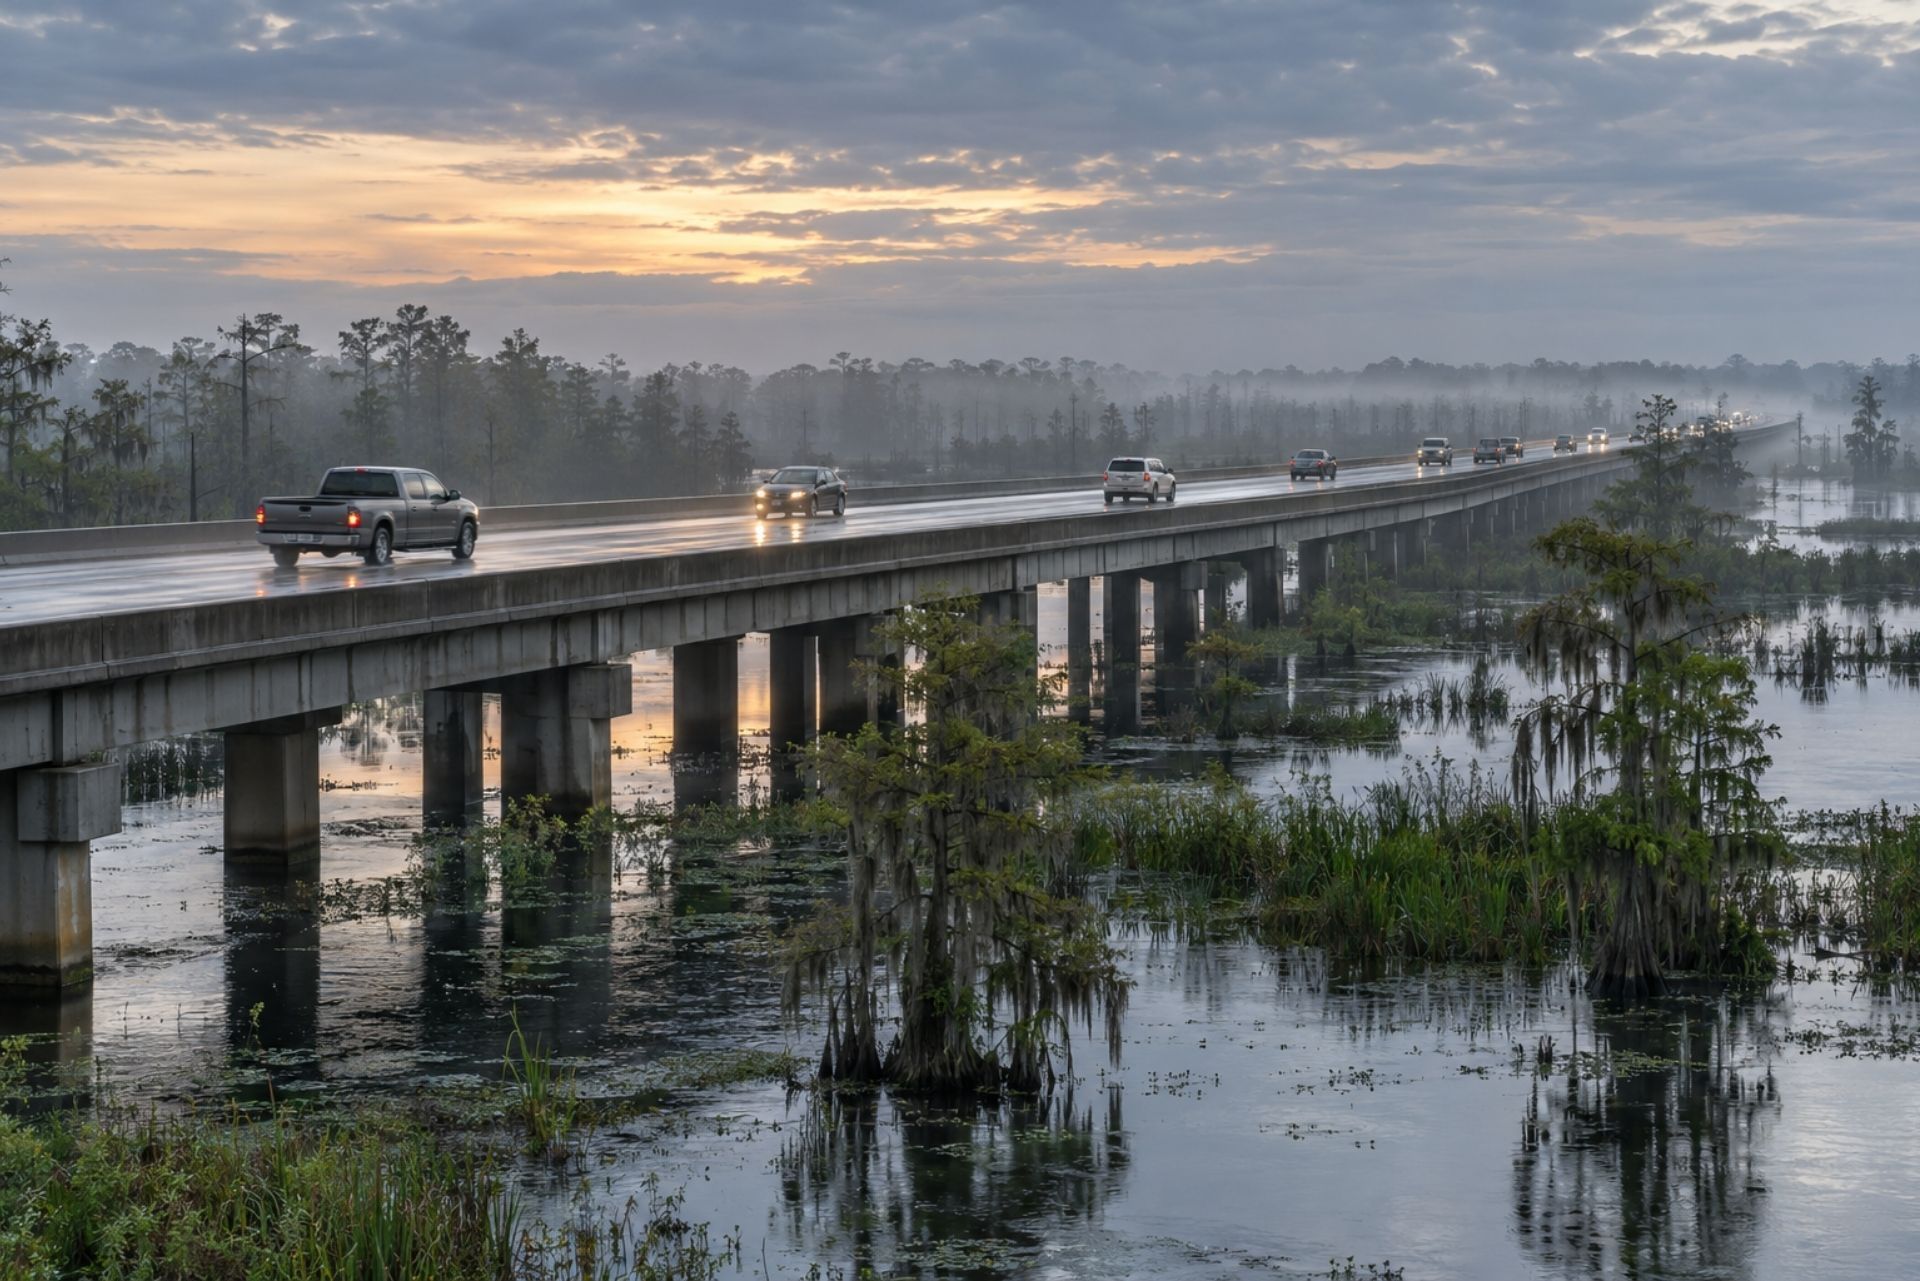
The stretch of I-55 between Ponchatoula and LaPlace runs on an elevated bridge over the Manchac swamp. There are limited exits, almost no shoulder room in spots and no easy way to pull off when something goes wrong. A stalled car, a fog bank rolling off Lake Maurepas or a sudden slowdown can create chain-reaction collisions in seconds.
Those multi-vehicle crashes are where coverage gaps show up. If you rear-end someone who rear-ended someone else, the claims can stack up across several cars. Low liability limits may get split among multiple injured drivers, leaving you exposed for the rest.
A few policy features matter more for Manchac commuters:
- Higher liability limits to handle claims involving more than one vehicle
- Roadside assistance and towing, since a breakdown on the bridge often means an expensive tow off the span
- Rental reimbursement, which may help keep you commuting while your car sits in a shop
- Comprehensive coverage for flying debris, which is common on long high-speed runs
Daily mileage also affects your premium. Report your commute honestly, because a misstated annual mileage can create problems at claim time.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Being named as a certificate holder just means someone receives proof. Being named as an additional insured means your policy may actually defend and pay for that party if they're sued because of your work. General contractors, developers, and property managers ask for this because they get pulled into lawsuits over subcontractor mistakes constantly.
Read the contract language closely. Some agreements require "primary and noncontributory" wording or completed operations coverage for the additional insured, which needs specific endorsements. Many contractors sign a subcontract agreeing to these terms without checking whether their policy includes them. If a claim comes in and the endorsement isn't there, you may be in breach of contract on top of facing the lawsuit.
Managing Highway 22 Traffic and Congestion Risks
Highway 22 is Ponchatoula's main east-west artery, connecting downtown to I-55, I-12 and the growing neighborhoods toward Madisonville. It carries school traffic, delivery trucks and weekend crowds, often all at once. Stop-and-go congestion produces a steady stream of low-speed rear-end collisions and parking lot fender benders.
Festival season pushes it further. During the Strawberry Festival, the Louisiana State Police have advised Baton Rouge commuters to exit I-12 at Pumpkin Center (Exit 35) and take LA 22 East into Ponchatoula to avoid I-55 backups. That rerouting funnels even more out-of-town drivers onto a road that's already busy.
Congestion crashes are rarely catastrophic, but they're frequent. One thing to keep in mind is your deductible. If you carry a $1,500 collision deductible, a minor bumper hit may come entirely out of pocket. Some drivers on busy corridors prefer a lower deductible and accept a slightly higher premium. Medical payments coverage can also help with smaller injury bills for you and your passengers regardless of fault.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Evaluating Wind and Tree Exposure Risks
Pine and oak trees are part of why people love living in the Pearl River area. They're also a leading cause of roof claims after tropical storms and severe thunderstorms. A single limb through a roof can open the house to water damage that runs far beyond the cost of the roof repair.
Carriers have noticed. In 2026, more insurers are making trimming of limbs that touch or hang over a roof a condition of renewal. A drive-by or aerial inspection may flag overhanging branches, and you could receive a notice giving you a deadline to fix it. Ignoring that letter can lead to nonrenewal, which makes finding new coverage harder.
The roof itself is the other half of the wind picture. Louisiana offers incentives for stronger roofs, and the state's wind mitigation program details explain how certain construction features can lower your premium. Beginning January 1, 2027, Louisiana insurers must apply a premium reduction of 16% to 49% to the hurricane portion for homes with a certified FORTIFIED roof. If you're planning a roof replacement anyway, it may make sense to price out FORTIFIED certification at the same time.
Also review your named storm or wind deductible. In this part of Louisiana, it's often a percentage of the dwelling limit rather than a flat dollar amount, so a 5% deductible on a $250,000 home means $12,500 out of pocket.
Your belongings
Personal property covers furniture, clothing, tools and electronics. Jewellery, firearms and silver carry low internal caps, so we schedule those items separately when they are worth more than the cap.
Farm Equipment and Machinery Protection
Tractors, bush hogs, UTVs, and zero-turn mowers are where a lot of Pearl River landowners find gaps. Personal property coverage on a homeowners policy may cover some yard equipment, but it often limits or excludes motorized vehicles and items used for farming or business purposes.
Options depend on how you use the equipment:
- Hobby or property maintenance use: An endorsement or scheduled item on the homeowners policy may work.
- Small-scale farming or hay production: A farm or ranch policy, or an inland marine/equipment floater, typically fits better.
- Off-road vehicles like UTVs: These often need their own policy, especially if driven off your property.
Keep serial numbers and photos of every machine. Theft of tractors and trailers from rural lots is a real claim type, and documentation speeds up recovery.
Insuring Farm and Personal Use Trucks in Tangipahoa Parish
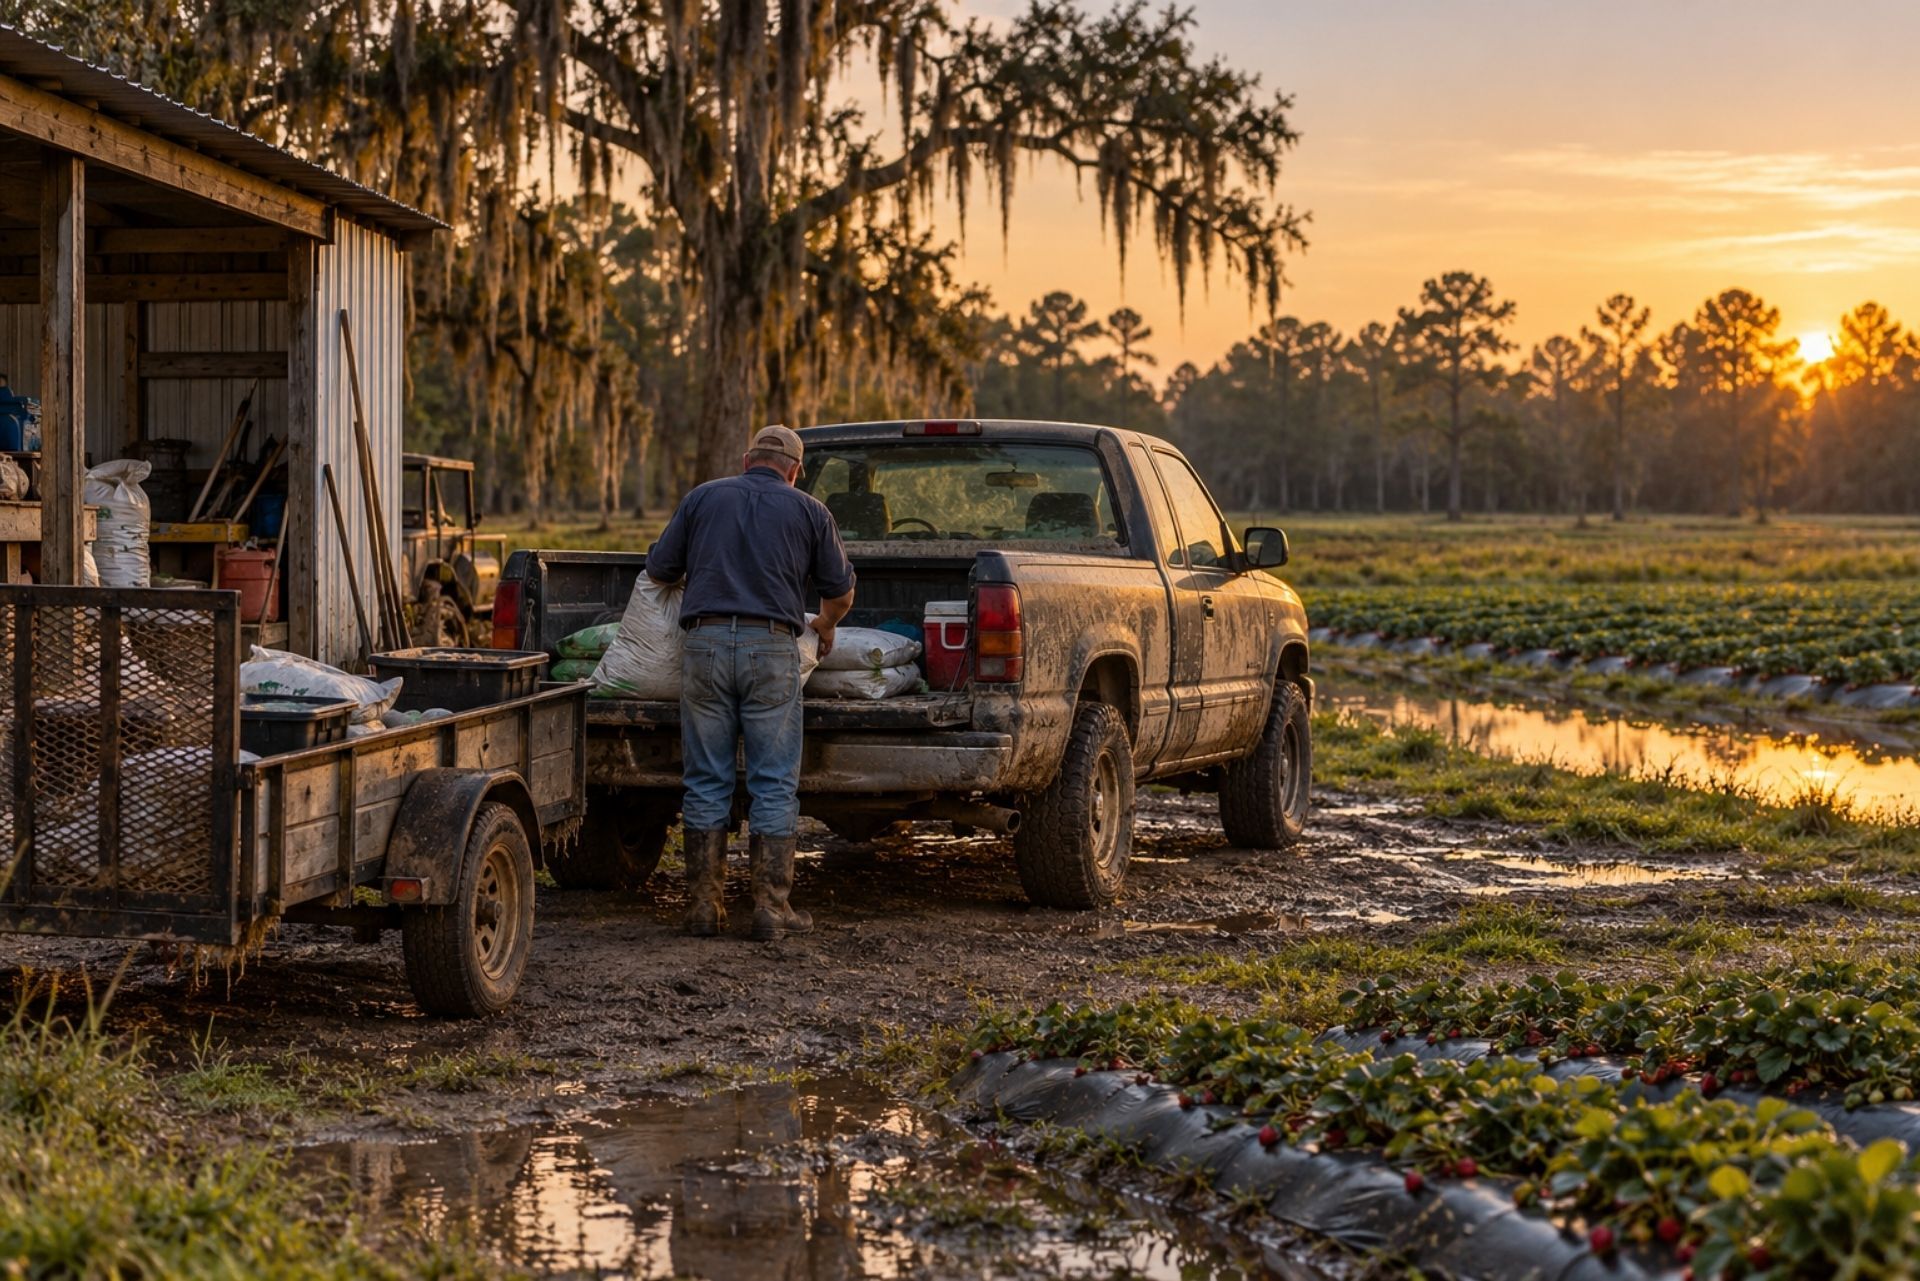
Plenty of Ponchatoula pickups live double lives. The same truck might haul strawberry flats on Tuesday and carry kids to practice on Wednesday. How you insure it depends on how it's actually used, and getting that wrong is one of the most common mistakes we see with rural households.
Farm Use Trucks
Under Louisiana OMV Policy 10.00, vehicles owned by active farmers and used primarily to carry farm produce qualify for Class 5 "Farm Use" plates. Those plates carry their own rules. In 2026, an executive order also allows Class 5 farm trucks and Class 2 forest products trucks to run dyed off-road diesel on public highways through October 22, 2026 because of high fuel prices. That's a temporary allowance, so don't assume it continues after that date.
A truck used heavily for farming may need a farm auto policy or coverage endorsed onto a farm package. Hauling equipment, towing trailers or carrying hired hands can fall outside a standard personal auto policy.
Personal Use Trucks
If your pickup mostly handles commuting, errands and the occasional load of mulch, a personal auto policy typically fits. Just be clear about any business or farm activity. An adjuster who learns a "personal" truck regularly hauls produce for sale may question the claim. When in doubt, describe the real use to your agent and let them match the policy.
Why Uninsured Motorist Coverage is Essential in Louisiana
Tangipahoa Parish has an uninsured motorist rate of roughly 18.3% as of 2026, higher than the statewide average of 12 to 14%. Put simply, close to one in five drivers around you may have no coverage at all. Many others carry only the minimum, which may not cover a serious injury.
Uninsured and underinsured motorist (UM) coverage pays for your injuries when the at-fault driver can't. Louisiana lets you reject it in writing, and some people sign that form to save a few dollars without understanding what they gave up. That's a decision we'd ask anyone to reconsider.
There's a nuance most people miss. If you're riding as a passenger and an uninsured driver hits the car, the UM coverage on the vehicle you're in typically pays first. Your own household policy may then act as excess coverage on top of it. So your UM limits protect you even in a friend's car, and the UM you carry also protects your passengers.
Ask your agent about UM limits that match your liability limits. It's often a modest cost for meaningful protection.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Evaluating Wind and Tree Exposure Risks
Pine and oak trees are part of why people love living in the Pearl River area. They're also a leading cause of roof claims after tropical storms and severe thunderstorms. A single limb through a roof can open the house to water damage that runs far beyond the cost of the roof repair.
Carriers have noticed. In 2026, more insurers are making trimming of limbs that touch or hang over a roof a condition of renewal. A drive-by or aerial inspection may flag overhanging branches, and you could receive a notice giving you a deadline to fix it. Ignoring that letter can lead to nonrenewal, which makes finding new coverage harder.
The roof itself is the other half of the wind picture. Louisiana offers incentives for stronger roofs, and the state's wind mitigation program details explain how certain construction features can lower your premium. Beginning January 1, 2027, Louisiana insurers must apply a premium reduction of 16% to 49% to the hurricane portion for homes with a certified FORTIFIED roof. If you're planning a roof replacement anyway, it may make sense to price out FORTIFIED certification at the same time.
Also review your named storm or wind deductible. In this part of Louisiana, it's often a percentage of the dwelling limit rather than a flat dollar amount, so a 5% deductible on a $250,000 home means $12,500 out of pocket.
Your belongings
Personal property covers furniture, clothing, tools and electronics. Jewellery, firearms and silver carry low internal caps, so we schedule those items separately when they are worth more than the cap.
Farm Equipment and Machinery Protection
Tractors, bush hogs, UTVs, and zero-turn mowers are where a lot of Pearl River landowners find gaps. Personal property coverage on a homeowners policy may cover some yard equipment, but it often limits or excludes motorized vehicles and items used for farming or business purposes.
Options depend on how you use the equipment:
- Hobby or property maintenance use: An endorsement or scheduled item on the homeowners policy may work.
- Small-scale farming or hay production: A farm or ranch policy, or an inland marine/equipment floater, typically fits better.
- Off-road vehicles like UTVs: These often need their own policy, especially if driven off your property.
Keep serial numbers and photos of every machine. Theft of tractors and trailers from rural lots is a real claim type, and documentation speeds up recovery.
Seeing the coverages side by side makes the value of extended protection easier to judge.
Why Did I Get a Letter from My Lender?
Federally backed and federally regulated lenders must require flood insurance on properties in Special Flood Hazard Areas. When a remapping places your home inside one of those areas, the lender is obligated to notify you. The letter will typically ask you to show proof of flood coverage within a set period, often 45 days.
Do not ignore it. If you do nothing, the lender can buy force-placed flood insurance on your behalf and add the cost to your escrow. Force-placed coverage is usually more expensive and generally protects the lender's interest in the structure, not your belongings.
Comparing Coverage Levels for Ponchatoula Drivers
Comparing Coverage Levels for Ponchatoula Drivers
Comparing Coverage Levels for Ponchatoula Drivers
The difference between a bare-minimum policy and a well-built one usually shows up only after a crash. This side-by-side view may help you see where the gaps sit..
| Coverage Area | Basic State Requirement | Extended Option |
|---|---|---|
| Bodily injury liability | State minimum limits | Higher limits to protect assets |
| Property damage liability | State minimum limits | Higher limits for multi-car crashes |
| Uninsured/underinsured motorist | Can be rejected in writing | Limits matched to liability |
| Collision | Not required | Pays to repair your vehicle |
| Comprehensive | Not required | Flood, theft, debris, hail |
| Medical payments | Not required | Helps with smaller injury bills |
| Roadside and rental | Not required | Towing and a car while yours is repaired |
| Farm truck use | Not addressed | Farm auto or endorsement may apply |
Comprehensive deserves a mention for south Louisiana specifically. Flooded vehicles after heavy storms are a real risk, and only comprehensive typically covers flood damage to your car. Lenders usually require collision and comprehensive on financed vehicles anyway.
Common Questions About Ponchatoula Auto Insurance
Why do rates in Ponchatoula seem higher than in other states? Louisiana premiums tend to run high because of claim frequency, litigation costs and weather losses. Local factors like interstate commuting and a high uninsured rate can also play a part.
Do I really need uninsured motorist coverage? With nearly one in five drivers in Tangipahoa Parish uninsured, it's one of the most valuable coverages you can carry. It protects you and your passengers when the at-fault driver can't pay.
Can my farm truck go on my regular car policy? It depends on how the truck is used. Light personal use usually fits a personal policy, while regular farm hauling may need a farm auto policy or endorsement.
Does my policy cover flood damage to my car? Flood damage is typically covered only if you carry comprehensive coverage. Liability-only policies won't pay to repair or replace your own vehicle.
Will a long I-55 commute raise my premium? Higher annual mileage can affect your rate. Even so, accurate reporting protects you from claim disputes later.
How often should I review my coverage? Review it once a year and any time you buy a vehicle, change jobs, add a driver or start farming.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Evaluating Wind and Tree Exposure Risks
Pine and oak trees are part of why people love living in the Pearl River area. They're also a leading cause of roof claims after tropical storms and severe thunderstorms. A single limb through a roof can open the house to water damage that runs far beyond the cost of the roof repair.
Carriers have noticed. In 2026, more insurers are making trimming of limbs that touch or hang over a roof a condition of renewal. A drive-by or aerial inspection may flag overhanging branches, and you could receive a notice giving you a deadline to fix it. Ignoring that letter can lead to nonrenewal, which makes finding new coverage harder.
The roof itself is the other half of the wind picture. Louisiana offers incentives for stronger roofs, and the state's wind mitigation program details explain how certain construction features can lower your premium. Beginning January 1, 2027, Louisiana insurers must apply a premium reduction of 16% to 49% to the hurricane portion for homes with a certified FORTIFIED roof. If you're planning a roof replacement anyway, it may make sense to price out FORTIFIED certification at the same time.
Also review your named storm or wind deductible. In this part of Louisiana, it's often a percentage of the dwelling limit rather than a flat dollar amount, so a 5% deductible on a $250,000 home means $12,500 out of pocket.
Your belongings
Personal property covers furniture, clothing, tools and electronics. Jewellery, firearms and silver carry low internal caps, so we schedule those items separately when they are worth more than the cap.
Farm Equipment and Machinery Protection
Tractors, bush hogs, UTVs, and zero-turn mowers are where a lot of Pearl River landowners find gaps. Personal property coverage on a homeowners policy may cover some yard equipment, but it often limits or excludes motorized vehicles and items used for farming or business purposes.
Options depend on how you use the equipment:
- Hobby or property maintenance use: An endorsement or scheduled item on the homeowners policy may work.
- Small-scale farming or hay production: A farm or ranch policy, or an inland marine/equipment floater, typically fits better.
- Off-road vehicles like UTVs: These often need their own policy, especially if driven off your property.
Keep serial numbers and photos of every machine. Theft of tractors and trailers from rural lots is a real claim type, and documentation speeds up recovery.
Seeing the coverages side by side makes the value of extended protection easier to judge.
Why Did I Get a Letter from My Lender?
Federally backed and federally regulated lenders must require flood insurance on properties in Special Flood Hazard Areas. When a remapping places your home inside one of those areas, the lender is obligated to notify you. The letter will typically ask you to show proof of flood coverage within a set period, often 45 days.
Do not ignore it. If you do nothing, the lender can buy force-placed flood insurance on your behalf and add the cost to your escrow. Force-placed coverage is usually more expensive and generally protects the lender's interest in the structure, not your belongings.
Comparing Coverage Levels for Ponchatoula Drivers
Comparing Coverage Levels for Ponchatoula Drivers
Making the Right Choice for Your Vehicle Protection
Driving in Ponchatoula means planning for very different risks in a single week. The Manchac bridge calls for strong liability limits and roadside help. Highway 22 congestion makes your deductible and medical payments coverage worth a second look. Farm trucks need honest classification, and the parish's uninsured driver rate makes UM coverage hard to skip.
No single carrier is the right fit for every household. That's why working with an independent agency makes sense. Aubert Insurance Agency has been insuring what matters most to Louisiana families since 1910, and we compare options from multiple leading carriers in one place. We also take the time to explain how your policy works, including exclusions, so there are no surprises when you file a claim.
The process is simple: start online, we shop for you, and you pick the plan that fits. Whether you commute daily over the swamp or run a working truck through strawberry country, we'll help you build coverage that matches how you actually drive.
Ready to see your options? Start a Quote with Aubert Insurance Agency today and get personalized coverage built for Ponchatoula roads.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.

Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.

Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.

Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.

Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.

Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

Residential General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Trade Contractors
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.
Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.










Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Visit
614 E. Boston St., Covington, LA 70433 — Get Directions
58418 Tyler Drive, Slidell, LA 70461 — Get Directions


