













Covington & Slidell Independent Insurance Agents
Roofing insurance in Louisiana typically requires a combination of General Liability, Workers Compensation, and specific endorsements that address height exposure, heat stress, and weather damage to open roofs. Most roofers also need Commercial Auto, Inland Marine for tools, and a properly sized umbrella, all matched to the 2026 state licensing rules.
Picture a crew in Slidell tearing off a hip roof on a Tuesday afternoon in August. The heat index is climbing past what feels survivable, a thunderstorm is building over the lake, and the tarps are still in the truck. Any one of those details can turn a profitable job into a claim. This is why insurance for Louisiana roofing contractors looks different from coverage for almost any other trade.
The questions roofers ask us usually fall into four buckets. They want to know why their workers comp rate looks so high, what happens when rain gets into a home mid-project, and how to compete with out-of-state crews after a hurricane. More and more, they also ask whether Fortified installation work changes their policy. Each one gets a straight answer below, written for owners in Covington, Slidell, and across St. Tammany Parish who want to understand what they are paying for.
Understanding Louisiana Roofing Contractor Insurance Requirements
Most roofing businesses need four core policies: General Liability, Workers Compensation, Commercial Auto, and Inland Marine for tools and equipment. An umbrella policy sits on top to extend liability limits, which many general contractors and commercial property owners require before they will sign a subcontract.
Licensing now drives a lot of this. Effective January 1, 2026, anyone performing residential roofing work valued at $7,500 or more must hold a Residential Roofing or Residential Construction license from the LSLBC. Proof of insurance is part of staying in good standing, so a lapse in coverage can create licensing problems as well as claim problems.
The state is enforcing it. In June 2026, the board issued "No Contest" pleas and fines against firms operating without the proper residential roofing license, including PNP Roofing LLC and Summit Builders LLC. Carriers notice this too. An unlicensed or improperly licensed roofer may find that a claim gets complicated fast, especially when a homeowner's attorney starts asking questions.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
The Impact of Height and Heat Class Codes on Your Premiums
Workers comp for roofers is priced by classification, and roofing sits in one of the more expensive groups because falls are the main cause of serious injury in the trade. In Louisiana, roofing payroll typically falls under the NCCI roofing classification, and some carriers also look at the type of work you do: steep residential versus low-slope commercial, or new construction versus re-roof.
Here is where owners get burned. If your office manager or estimator gets lumped into the roofing code, you pay roofing rates on a desk job. Clerical and outside sales employees may qualify for separate, lower-rated classes, but only if your payroll records clearly show the split. At audit time, sloppy records almost always land in the most expensive bucket.
Heat matters more now than it used to. OSHA's National Emphasis Program for heat-related hazards is actively enforced through 2031, and it expects contractors to document "water, rest, and shade" protocols. A written heat plan won't lower your class rate directly, but it supports your safety record. Over time, that record shapes your experience modifier, which is the number that really moves your premium year to year.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Managing Risks for Open Roof and Rain Intrusion Claims
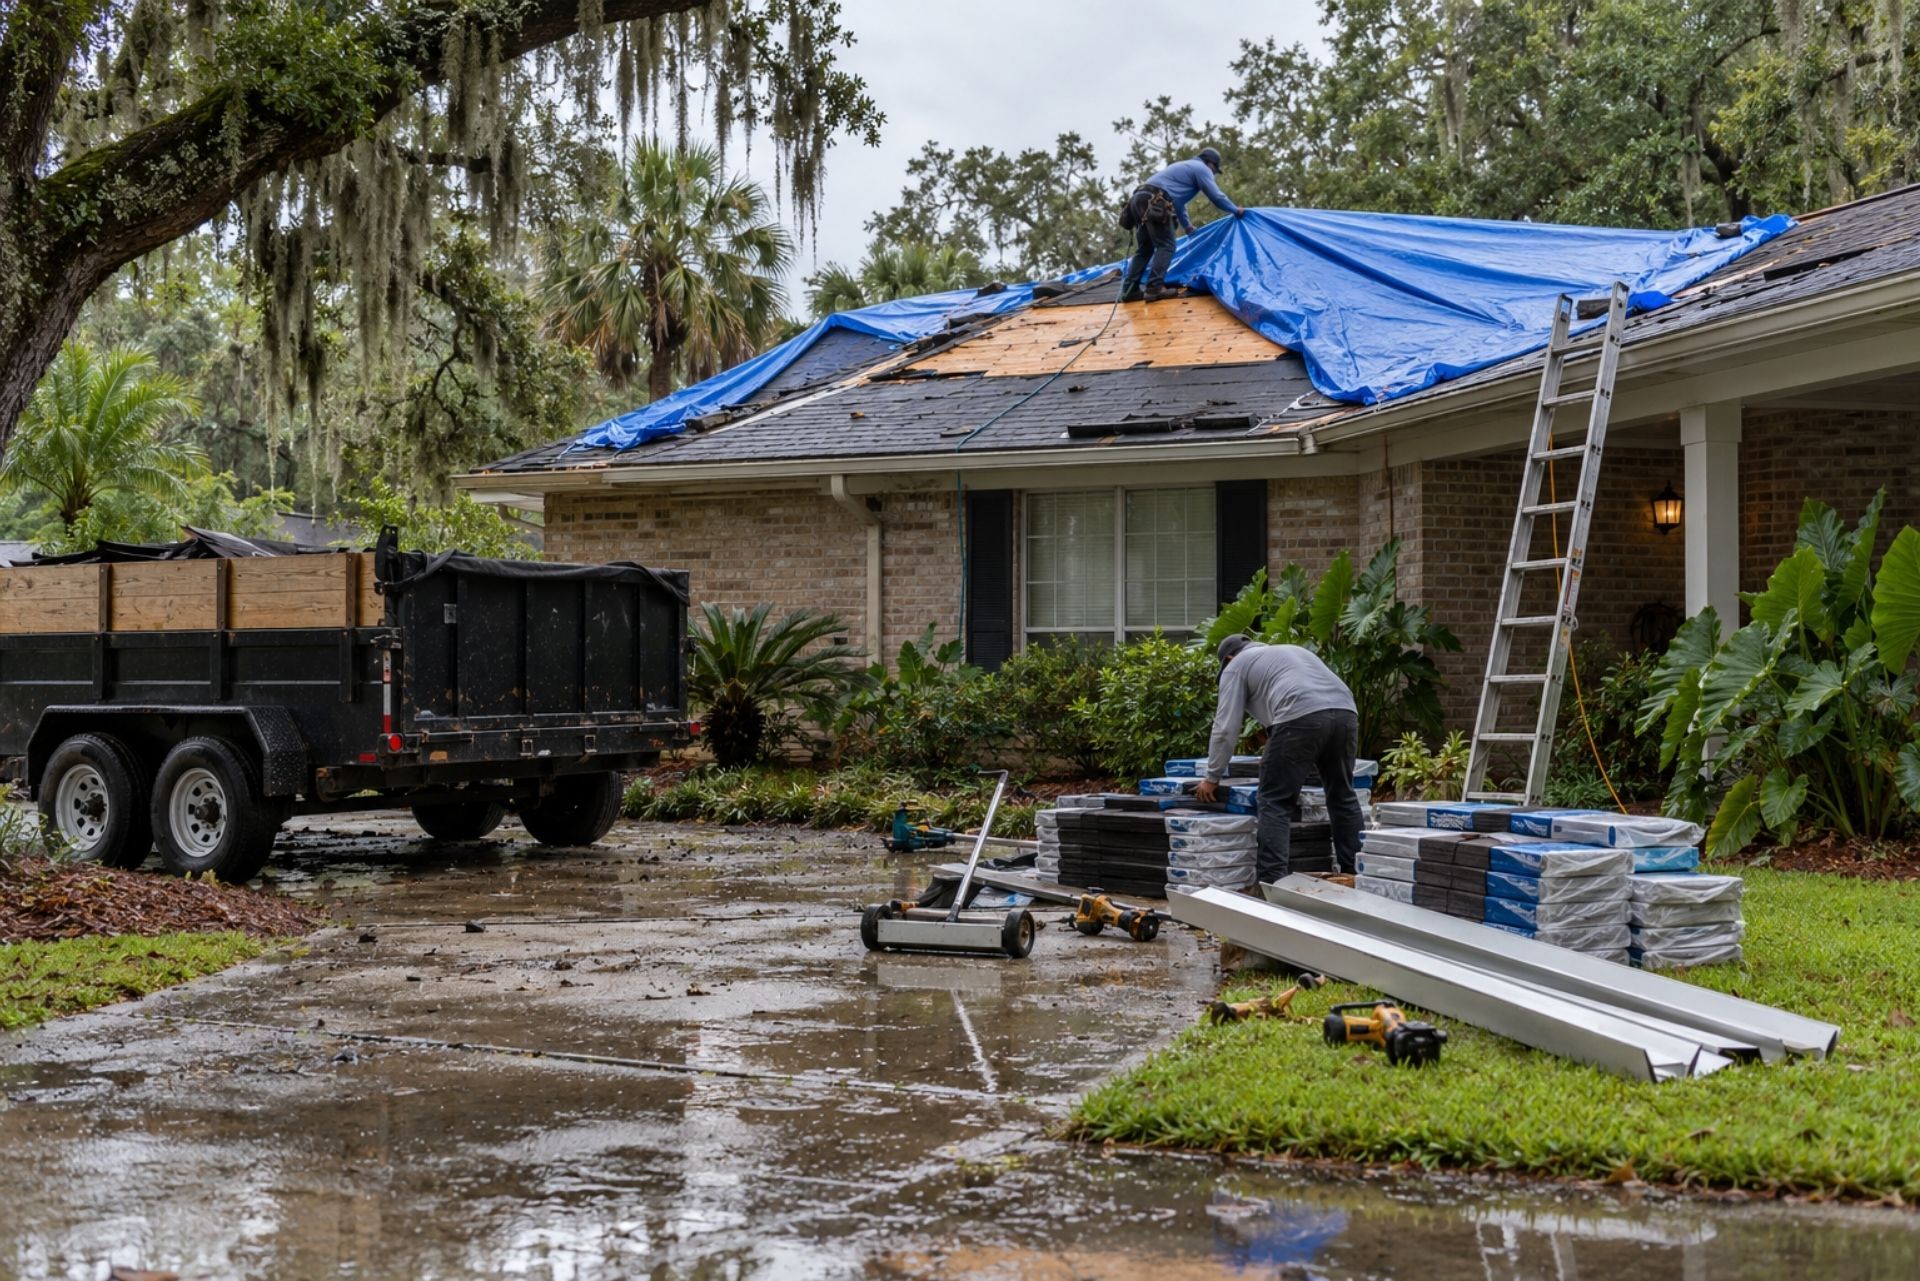
Open roof claims are the claim type we see roofers misunderstand most. The scenario is familiar: the crew strips a section, a pop-up storm rolls in, and water soaks the ceiling drywall, insulation, flooring, and maybe a homeowner's furniture. The homeowner calls you, not their own carrier.
Many General Liability policies may respond to resulting property damage, but some carriers add exclusions or limitations for water damage that occurs while a roof is open. These can show up as an "open roof exclusion" or a requirement that you follow specific tarping procedures. If the endorsement is buried in your policy and you never read it, you find out during the worst possible phone call.
A few habits help protect both the job and the claim:
- Check the forecast each morning and limit tear-off to what the crew can dry-in that day
- Keep tarps and fasteners on the truck, not back at the yard
- Photograph the dry-in before leaving the site each evening
- Ask your agent directly whether your GL policy limits water intrusion during active work
That last item is the one most roofers skip. Get the answer in writing before hurricane season, not after.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Standing Out Against Storm Chaser Competition After Hurricanes
After a named storm, St. Tammany fills up with trucks carrying unfamiliar plates and magnetic door signs. Some of these crews do honest work. Others take deposits and disappear, or install roofs with no real coverage behind them. Local roofers lose bids to them on price, then spend the next two years fixing their mistakes.
Your insurance can be a selling point here. Homeowners and adjusters are getting more cautious, and many now ask for a certificate of insurance before signing anything. A local roofer who can hand over a current certificate showing GL, workers comp, and a valid state license looks very different from someone who can't.
Some practical ways to use this:
- Keep certificates ready to send the same day a homeowner asks
- Mention your LSLBC residential license in estimates and on your trucks
- Explain to homeowners that an uninsured worker's injury on their property could become their problem
One caution: post-storm volume can push your payroll well past what you estimated at renewal. Call your agent when work surges. A large audit bill in the spring can wipe out the profit from a busy fall.
Covington & Slidell Independent Insurance Agents
Insurance Considerations for Fortified Roof Installation Work
Fortified roofs are a big deal in Louisiana right now. The Insurance Commissioner's office has said that "Louisiana is the fastest growing state for Fortified roofs in America", and the state's benchmark premium credits give homeowners a strong reason to ask for one. Homeowners can see a 29% reduction on the hurricane portion of their premium for a Fortified Roof, and up to 49% for a Fortified Gold designation.
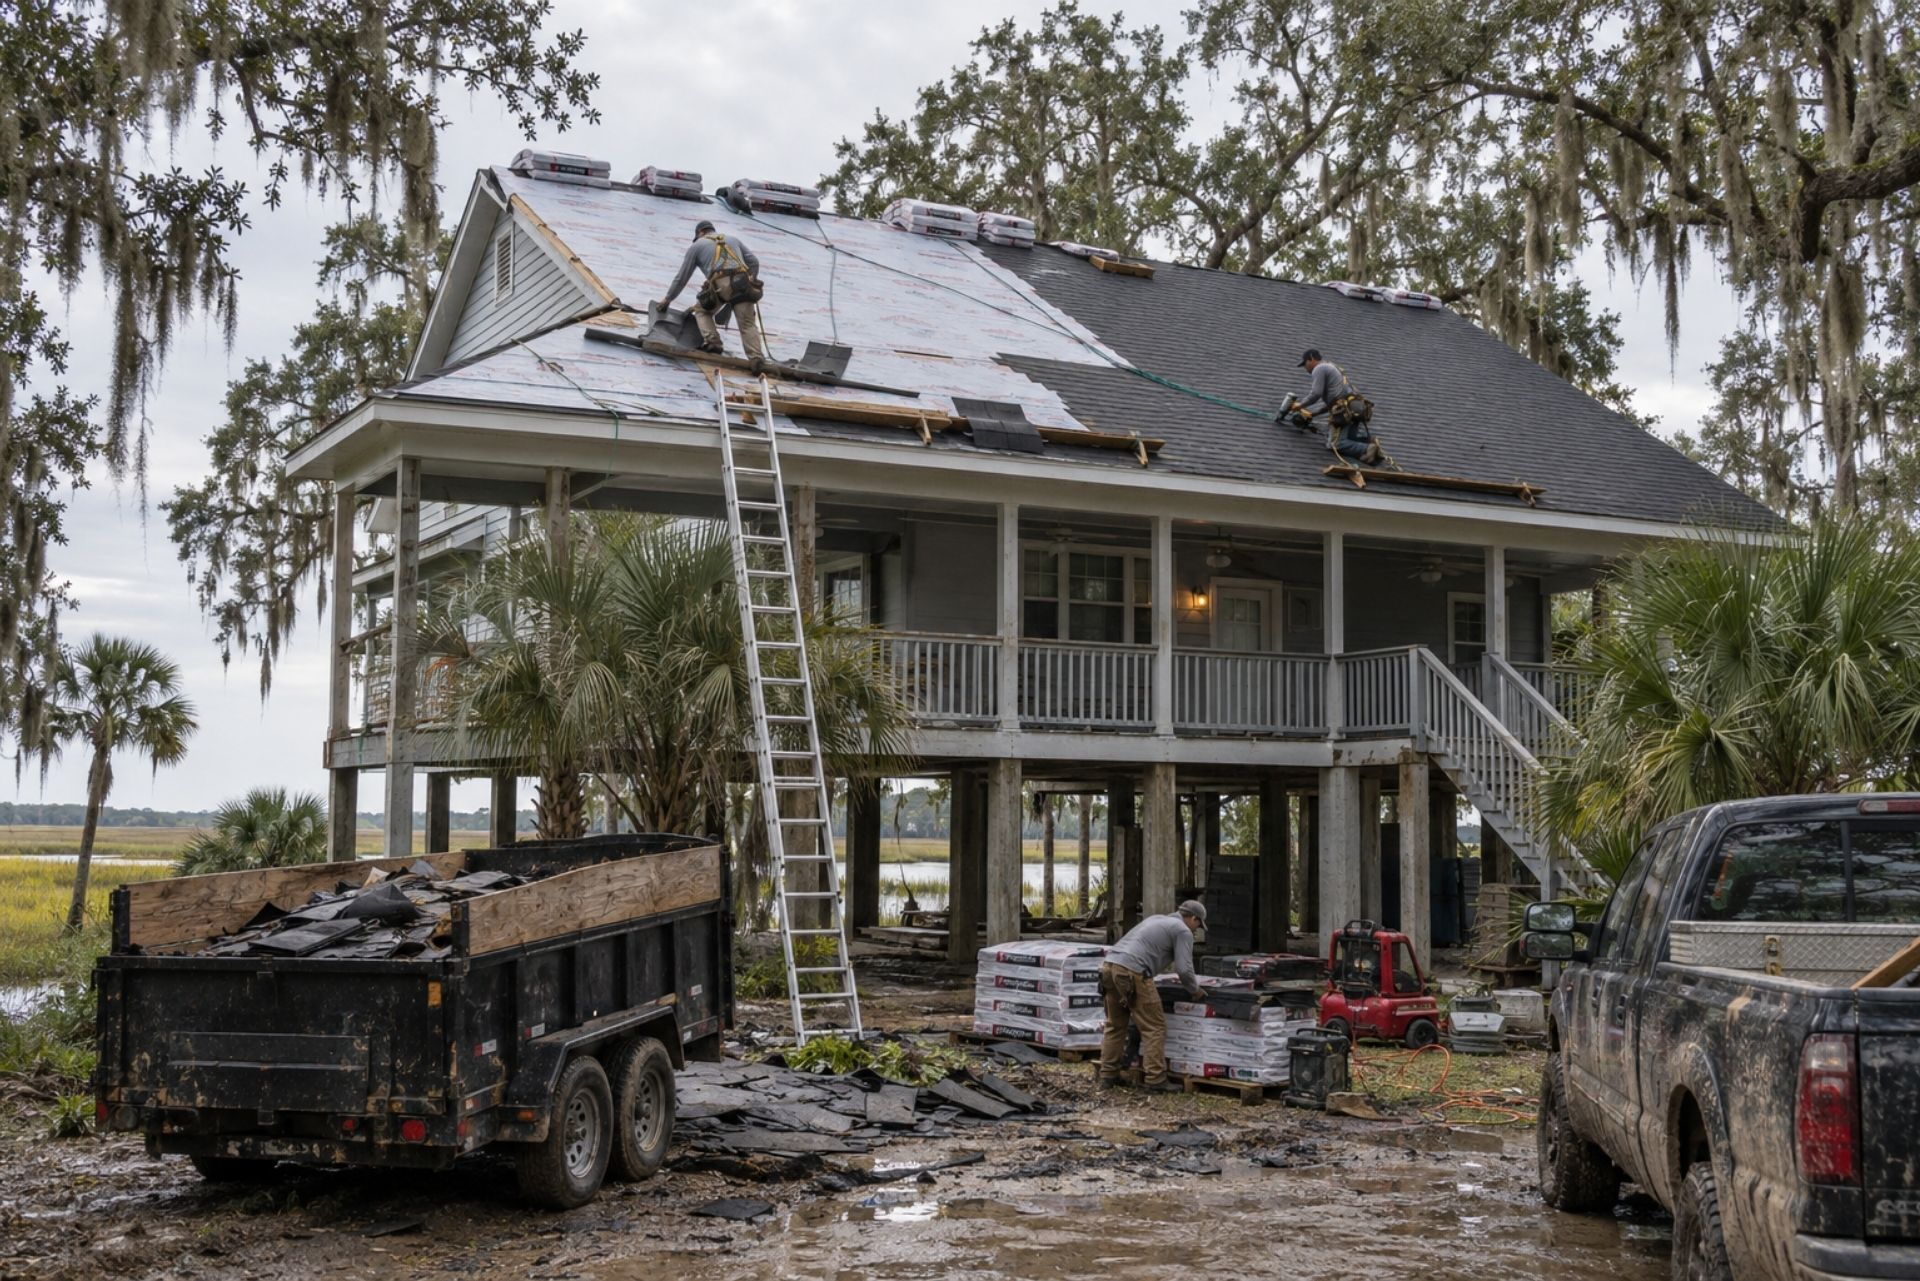
That creates opportunity for roofers, along with new liability. A Fortified roof requires specific installation methods, sealed roof decks, enhanced nailing, and third-party evaluation. If a home fails to receive its designation because of an installation error, the homeowner may lose that premium reduction. They could come back to you for the difference, possibly for years.
That kind of financial loss without physical damage may not fall neatly under General Liability. It looks more like a professional error, and that's a gap many roofers never consider.
Comparing Standard vs. Fortified Project Coverage
On a standard re-roof, your main concerns are bodily injury, property damage, and workmanship issues that cause physical harm. On a Fortified job, you add documentation risk and certification risk. Some carriers may offer contractor's professional liability or errors and omissions coverage that could respond to a failed designation, though terms vary widely. Keep your photo records and evaluator paperwork for every Fortified install, because those records are often your strongest defense.
not, unless you're both named on the policy. Each roommate typically needs their own coverage, and shared policies can get messy when one person files a claim.
Will my renters insurance cover my dog biting someone? Many policies include pet liability under personal liability, but some carriers exclude certain breeds or cap dog bite claims. Tell your agent about your pet upfront so there's no surprise later.
Does my landlord's insurance cover my belongings? No. Your landlord's policy typically covers the building only, so your furniture, clothes and electronics need your own policy.
When should I buy flood insurance before hurricane season? Aim for spring. NFIP contents coverage generally has a 30-day waiting period, so buying in late May means protection by the heart of the season.
What should I do to prepare my rental for a hurricane? Take a video walkthrough of every room, save receipts for big items in the cloud and keep a copy of your policy on your phone. Good documentation is the single biggest factor in how fast a storm claim gets paid.
Will renters insurance pay for a hotel if we evacuate? It depends. Loss of use typically kicks in when your rental is uninhabitable from a covered loss or when a civil authority orders evacuation, but check your policy wording.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Roofing Coverage Comparison Table
| Coverage | What It Typically Covers | Common Gap for Roofers |
|---|---|---|
| General Liability | Third-party injury and property damage | Open roof or water intrusion exclusions |
| Workers Compensation | Employee injuries, including falls and heat illness | Misclassified office staff raising premium |
| Commercial Auto | Trucks, trailers, and crew vehicles | Personal vehicles used for business |
| Inland Marine | Tools, nail guns, and equipment off-site | Theft from unlocked trailers |
| Umbrella | Extra liability limits above GL and auto | Limits too low for commercial contracts |
| Professional Liability | Financial loss from errors, such as a failed Fortified designation | Often not purchased at all |
Frequently Asked Questions About Louisiana Roofing Insurance
Do I need workers comp if I only have two employees? Louisiana generally requires workers comp for employers in construction trades, and roofing is treated as high risk. Talk with your agent about your specific crew setup, including any subcontractors.
Will hiring subcontractors lower my workers comp cost? It may, but only if each sub carries their own valid coverage and you collect certificates. Uninsured subs often get added to your payroll at audit.
Does General Liability cover rain damage during a re-roof? It may, depending on your policy. Some carriers exclude or limit water damage while a roof is open, so read your endorsements carefully.
What license do I need for residential roofing in 2026? For residential jobs of $7,500 or more, you need a Residential Roofing or Residential Construction license from the LSLBC.
Can installing Fortified roofs affect my insurance? Yes. Fortified work adds certification responsibility, and some roofers add professional liability to cover errors that could cost a homeowner their premium reduction.
How can I lower my roofing insurance premium? Keep clean payroll records, document safety and heat protocols, and have an independent agent compare several carriers at renewal.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Before You Buy a Policy
Roofing in Louisiana combines height, heat, sudden storms, and post-hurricane chaos in a way few other trades do. Your coverage should reflect that. Check how your payroll is classified and read the water intrusion language in your GL policy. Keep your license current under the 2026 rules, and if you're moving into Fortified installation work, ask whether a professional liability gap exists in your program.
The roofers who come through storm season in good shape usually aren't the ones with the lowest premium. They're the ones who knew exactly what their policy would and would not do before the first tarp went up.
Aubert Insurance Agency has served Louisiana from Covington and Slidell since 1910. As an independent agency, we compare options from multiple leading carriers and explain the exclusions in plain language, so you understand the contract you're signing. The process is simple: start online, we shop for you, and you pick the plan that fits your crew. Start a Quote today and get your roofing coverage reviewed before the next storm rolls across the lake.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













