













Covington & Slidell Independent Insurance Agents
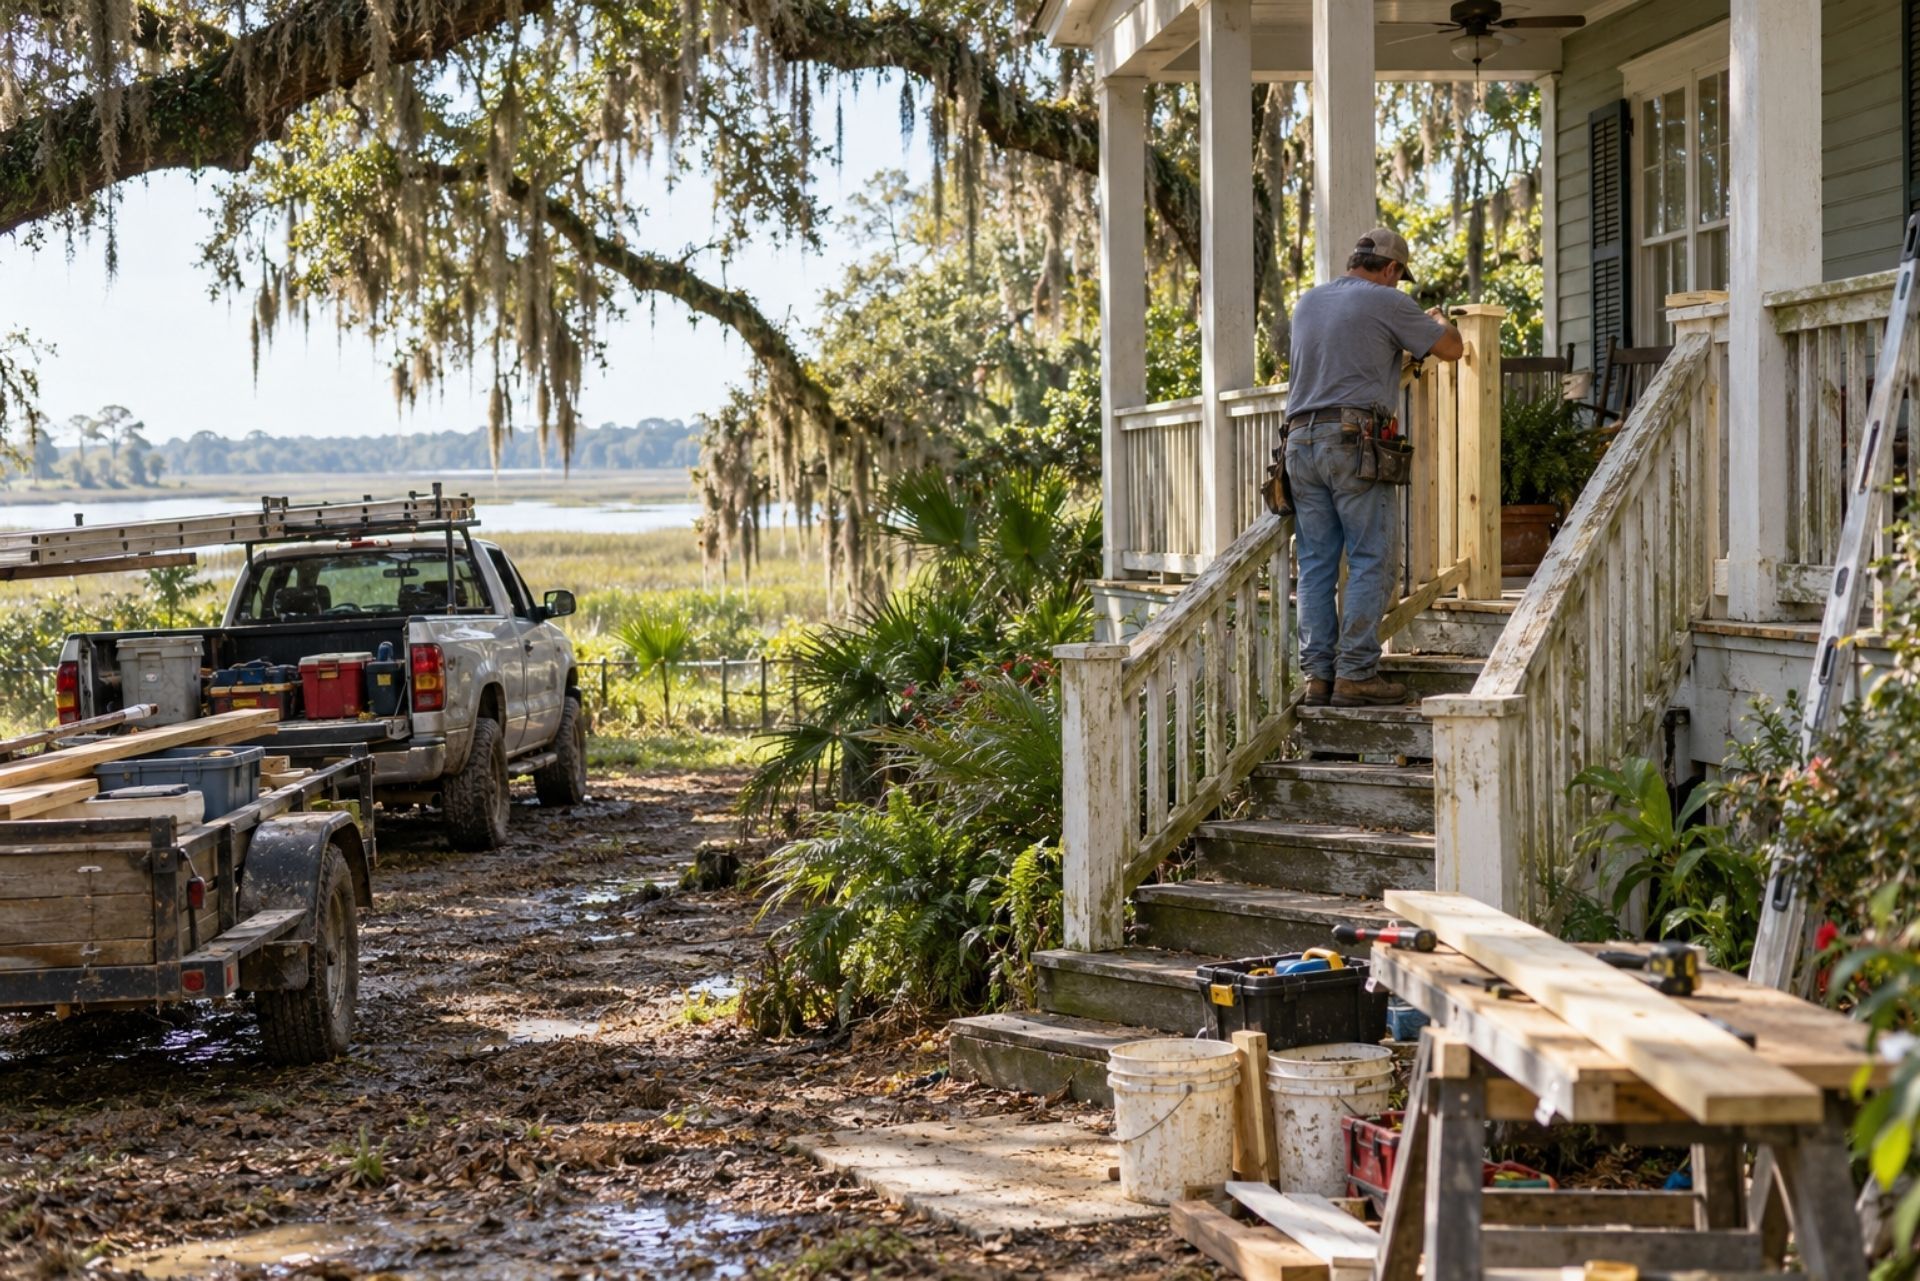
Picture a Saturday call from a homeowner in Madisonville: a leaky faucet, a sticking door, a few rotted fascia boards, and "while you're here, can you move that outlet?" Three of those jobs are routine handyman work. The fourth could cost you your insurance protection. This guide covers how Louisiana handymen stay on the right side of the state's licensing threshold, what work to turn down, and how to protect your tools and truck.
Louisiana Handyman Insurance Requirements and the State Licensing Threshold
Louisiana handymen typically do not need a state contractor license for home improvement projects under $7,500, but they still need general liability insurance to protect against property damage and injury claims. Aubert Insurance Agency has served Covington, Slidell, and St. Tammany Parish since 1910, helping local tradespeople find coverage that fits their actual work.
Even without a license, insurance is often the only thing between one bad afternoon and a lawsuit. Homeowners, property managers, and HOAs around Mandeville and Slidell increasingly ask for a certificate of insurance before you start. A handyman who can produce one on the spot wins more jobs than one who can't.
If you employ anyone, even one part-time helper, the rules change. Louisiana law (La. R.S. 23:1031) requires workers' compensation for any business with one or more employees. Paying a helper cash does not make that requirement go away, and an uninsured injury claim can follow you personally.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Understanding the $7,500 Rule and Staying Under the Threshold
The $7,500 figure trips people up because handymen tend to think in terms of individual tasks, while the state looks at the total contract value. If a homeowner hires you to fix drywall, paint two rooms, replace trim, and install new interior doors, the whole job counts together. Splitting one project into several invoices to stay under the line is exactly the kind of thing that draws attention from regulators.
The stakes are real. Under state law, contracts performed by unlicensed contractors above legal thresholds are "absolute nullities", which means you may not be able to enforce payment if the client refuses to pay. That same statute allows fines of up to $500 per day of violation or up to three months in prison. The state also publishes contractor violation records, so a citation can follow your reputation.
A few habits keep you safe:
- Write a scope for every job. List each task and the total price, including materials.
- Watch scope creep. A $5,000 bathroom refresh can hit $8,000 once the homeowner adds a vanity and tile.
- Track materials honestly. Customer-supplied materials do not erase the value of the work for licensing purposes, so ask before you assume.
- Know when to refer out. Passing a big job to a licensed contractor often earns you the smaller follow-up work.
If you find yourself regularly bumping against the threshold, it may be time to pursue a home improvement registration. Keep in mind that effective August 1, 2026, Act 757 raised minimum general liability for home improvement and residential licensees from $100,000 to $500,000. Plan for that higher limit before you apply.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Work You Should Not Take Without a Trade License
Some work requires a trade license no matter how small the bill. A $150 outlet swap and a $6,000 rewiring job fall under the same rules in many cases, because the concern is safety, not price. Taking these jobs creates legal exposure and gives your insurance carrier a strong reason to deny a claim.
Here is the work to decline or refer:
- Electrical work beyond basic fixture swaps. Adding circuits, moving outlets, panel work, and new wiring belong to licensed electricians. A fire traced to unlicensed wiring is one of the costliest claims a handyman can face.
- Plumbing beyond simple repairs. Running new supply lines, gas lines, water heater installs, and sewer work typically require a licensed plumber. Replacing a faucet cartridge is different from re-piping a bathroom.
- HVAC work. Installing or repairing systems, handling refrigerant, and ductwork modifications require state HVAC credentials, and refrigerant handling carries federal certification rules too.
- Residential roofing. As of January 1, 2026, residential roofing work valued at $7,500 or more without a specific state license is a criminal misdemeanor. After a storm season, this is where most handymen get into trouble.
- Mold remediation. A separate mold remediation license applies when the mold-related portion exceeds $7,500. Louisiana's humidity makes this a common request, and the state's mold statutes set specific requirements for that work.
The insurance angle matters as much as the legal one. General liability policies typically list the classes of work you perform, and many include exclusions for work requiring a license you don't hold. If you tell your agent you do carpentry and painting, then a water heater you installed floods a house, the carrier may decline the claim. That leaves you paying for flooring, drywall, and the homeowner's hotel bill out of pocket.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Small-Job General Liability and Tools and Truck Coverage
Handyman protection usually comes down to three pieces, and each one covers a different kind of loss. Mixing them up is one of the most common mistakes we see.
General liability protects you when your work injures someone else or damages their property. Think of a ladder that slips and cracks a homeowner's granite countertop, or a client who trips over your extension cord. It may also cover completed operations, meaning claims that surface after you leave, like a shelf that falls a week later. For Louisiana handymen, general liability typically runs $700 to $1,300 per year, depending on the trades performed.
Your tools need their own protection. General liability does not cover your own equipment, and many homeowners or renters policies limit or exclude business property. Inland marine coverage (often called tools and equipment coverage) may protect tools stolen from your truck, damaged on a job site, or lost in transit. Theft from trucks parked overnight in apartment lots and job sites is a frequent claim, so ask about scheduling your higher-value items.
Then there's the truck. A personal auto policy may deny a claim if the accident happened while you were driving to a job with a bed full of tools. Commercial auto is built for business use, and in Louisiana the average annual cost for a contractor's work truck or van typically ranges from $2,200 to $3,800 per vehicle. Louisiana's auto rates run high, which makes shopping multiple carriers worth the effort.
Comparing Handyman Coverage Options
| Coverage | What It Protects | Example Claim | Who Typically Needs It |
|---|---|---|---|
| General Liability | Third-party injury and property damage | Client trips over your tools | Every handyman |
| Inland Marine (Tools) | Your tools and equipment | Saws stolen from your truck bed | Anyone with $2,000+ in gear |
| Commercial Auto | Your work vehicle and auto liability | Fender bender driving to a job | Anyone driving for business |
| Workers' Comp | Employee injuries | Helper falls off a ladder | Required with 1+ employees |
Treat this table as a starting point. The right mix for a solo handyman doing small repairs in Covington looks different from a two-person crew taking bigger remodeling jobs in Slidell.
How Jones Act Exposure Differs From State Workers Comp
Common Questions About Handyman Insurance in Louisiana
Do I need insurance if I'm just doing small jobs on the side? Legally, a solo handyman under the threshold may not be required to carry general liability. Practically, one damaged floor or injured guest can cost more than years of premiums, so most side-job handymen carry it.
Can I get handyman insurance without an LLC or a license? Yes. Many carriers write general liability for sole proprietors without a state license, as long as the work described matches what you actually do.
Does my personal auto policy cover my truck when I drive to jobs? It may not. Personal policies typically exclude or limit business use, so a commercial auto policy is usually the safer choice if you haul tools and drive to client homes.
What happens if I take a job over $7,500 without a license? You risk fines, possible jail time, and a contract the courts treat as void, which can leave you unable to collect payment. Your insurer may also refuse a related claim.
Will my general liability cover my own stolen tools? No. General liability covers other people's property and injuries. Your own tools typically need inland marine or tools and equipment coverage.
How much general liability should I carry? Many handymen start with $1 million per occurrence because clients and property managers often ask for it. If you hold a home improvement or residential license, the state minimum is now $500,000.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Your Next Steps for Local Protection
Good Louisiana handyman insurance starts with honesty about the work you do. Keep your contracts under the licensing threshold unless you hold the right registration, turn down electrical, plumbing, HVAC, roofing, and mold jobs that call for a trade license, and match your coverage to your real risks. General liability protects the people you work for, inland marine protects the tools that earn your living, and commercial auto protects the truck that gets you there.
Before you buy a policy, make a short list: the types of jobs you take, your typical contract size, the value of your tools, and how you use your vehicle. That list will help any agent describe your business accurately, which is the single biggest factor in whether a claim gets paid later.
Aubert Insurance Agency has been a fixture in St. Tammany Parish since 1910, and as an independent agency we compare rates across multiple carriers so you can see your options side by side. We'll also walk you through the exclusions in your policy so nothing catches you off guard on a job site.
Ready to protect your tools, truck, and reputation? Start a Quote with our Covington or Slidell office today, and we'll help you build coverage that fits the way you actually work.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













