













Louisiana Auto Repair Shop Insurance

Covington & Slidell Independent Insurance Agents

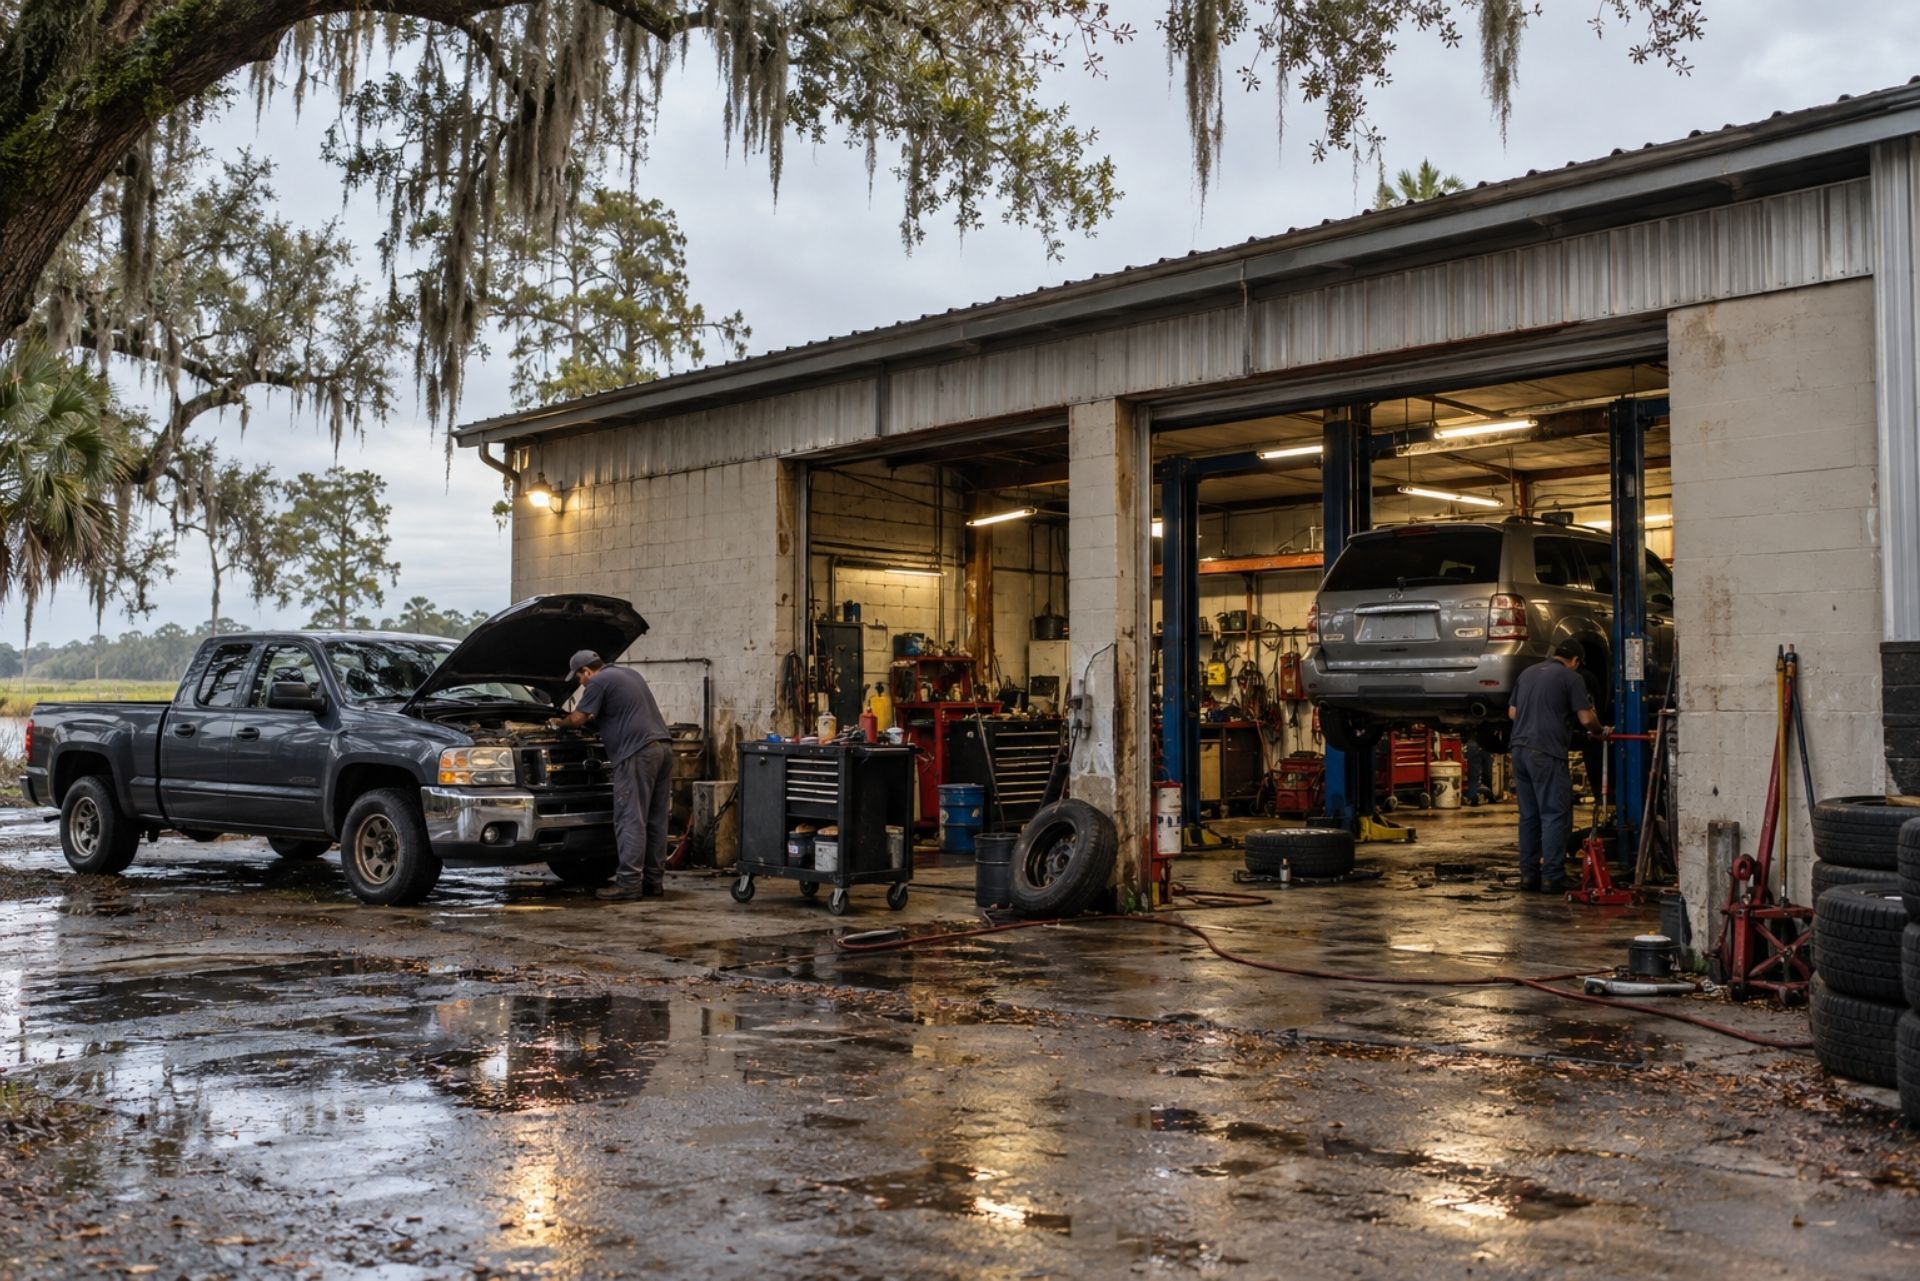
Picture a customer's truck sitting on your lift when the Bogue Falaya rises, or a tech clipping a mailbox on a road test down Highway 190. Those are the moments when the details of an auto shop policy start to matter. Most owners in St. Tammany Parish learn what their coverage actually says only after something goes wrong, and by then the gaps are expensive.

Essential Insurance for Louisiana Auto Repair Shops

Louisiana auto repair shops typically need two core coverages. Garage liability handles injuries and damage your operations cause to others. Garagekeepers protects customer vehicles while they sit in your care, custody and control. Most shops also carry workers' compensation, commercial property and commercial auto. Flood exposure needs its own review.


Aubert Insurance Agency has been writing coverage for Covington and Slidell businesses since 1910. In that time we've learned that shop owners rarely skimp on purpose. More often they buy a "garage package" without knowing which parts protect them and which parts protect the cars in the bay.


As an independent agency, we compare options from several carriers for you. We also walk through the exclusions line by line, because a policy is a legally binding contract. If you understand what it says before a claim, you won't have to argue about what it means afterward.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Understanding the Named Storm Deductible

A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.


There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.

Garage Liability vs Garagekeepers Coverage

People mix these two up constantly, partly because they sound almost identical. The easiest way to keep them straight is to ask whose property or body got hurt.


Garage liability covers your business operations. A customer trips over an air hose in the waiting area. A brake job you did fails three weeks later and causes a crash. A road test damages someone else's car. In each case, a third party claims you're responsible.


Garagekeepers covers the customer's vehicle itself while you have it. Garage liability policies typically exclude damage to property in your care, so without garagekeepers, the Tahoe that gets dented in your bay may not be covered at all.

Protecting Customer Vehicles in the Bay

Garagekeepers usually comes in two main forms. Legal Liability pays only when the shop is negligent. Direct Primary may pay for covered damage to customer vehicles regardless of fault.


That difference shows up in real claims. Say a hailstorm damages six cars parked overnight in your lot. Under Legal Liability, you may owe nothing legally, so the policy may not respond. Your customers will still be upset and may still expect you to fix it. Direct Primary typically costs more, but it lets you take care of people without a fault fight. For shops that care about reviews and repeat business, we usually think it's worth pricing out.

Coverage for Test Drives and Road Risks

Road tests count as operations, so liability for injuring others or damaging their property typically falls under garage liability. Damage to the customer's own car during the drive usually falls under garagekeepers, depending on the form you choose and how "collision" is defined.


A few habits help both your coverage and your defense:


  • Log every test drive with the driver, time, route and mileage.
  • Allow only listed, licensed employees to drive customer vehicles.
  • Don't let employees run personal errands in customer cars, since many carriers won't treat that as covered business use.


Louisiana's legal rules changed this year too. On January 1, 2026, the state moved to modified comparative fault, which bars recovery for any party 51% or more at fault. That may help shops in some disputed accidents, but you shouldn't count on a law change in place of solid limits.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Being named as a certificate holder just means someone receives proof. Being named as an additional insured means your policy may actually defend and pay for that party if they're sued because of your work. General contractors, developers, and property managers ask for this because they get pulled into lawsuits over subcontractor mistakes constantly.


Read the contract language closely. Some agreements require "primary and noncontributory" wording or completed operations coverage for the additional insured, which needs specific endorsements. Many contractors sign a subcontract agreeing to these terms without checking whether their policy includes them. If a claim comes in and the endorsement isn't there, you may be in breach of contract on top of facing the lawsuit.

Comparison of Coverage Scenarios

Here's how the two coverages typically line up. Actual results depend on your carrier, policy form and endorsements.

Scenario Garage Liability Garagekeepers
Lift fails, customer car falls Usually no (car is in your care) Typically yes
Lift fails, injures a visiting customer Typically yes No
Test drive hits another vehicle Typically yes (other car, injuries) May cover customer's car
Customer slips on oil in the bay Typically yes No
Employee injured under a lift No (workers' comp) No
Flood damages stored customer car No May apply, depending on form
Faulty repair causes later crash Typically yes (completed operations) No

The employee row trips up more owners than any other. Your own techs get hurt far more often than customers do, and neither garage coverage pays for those injuries. Workers' compensation does.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Risks of Lift Failures and Shop Injuries

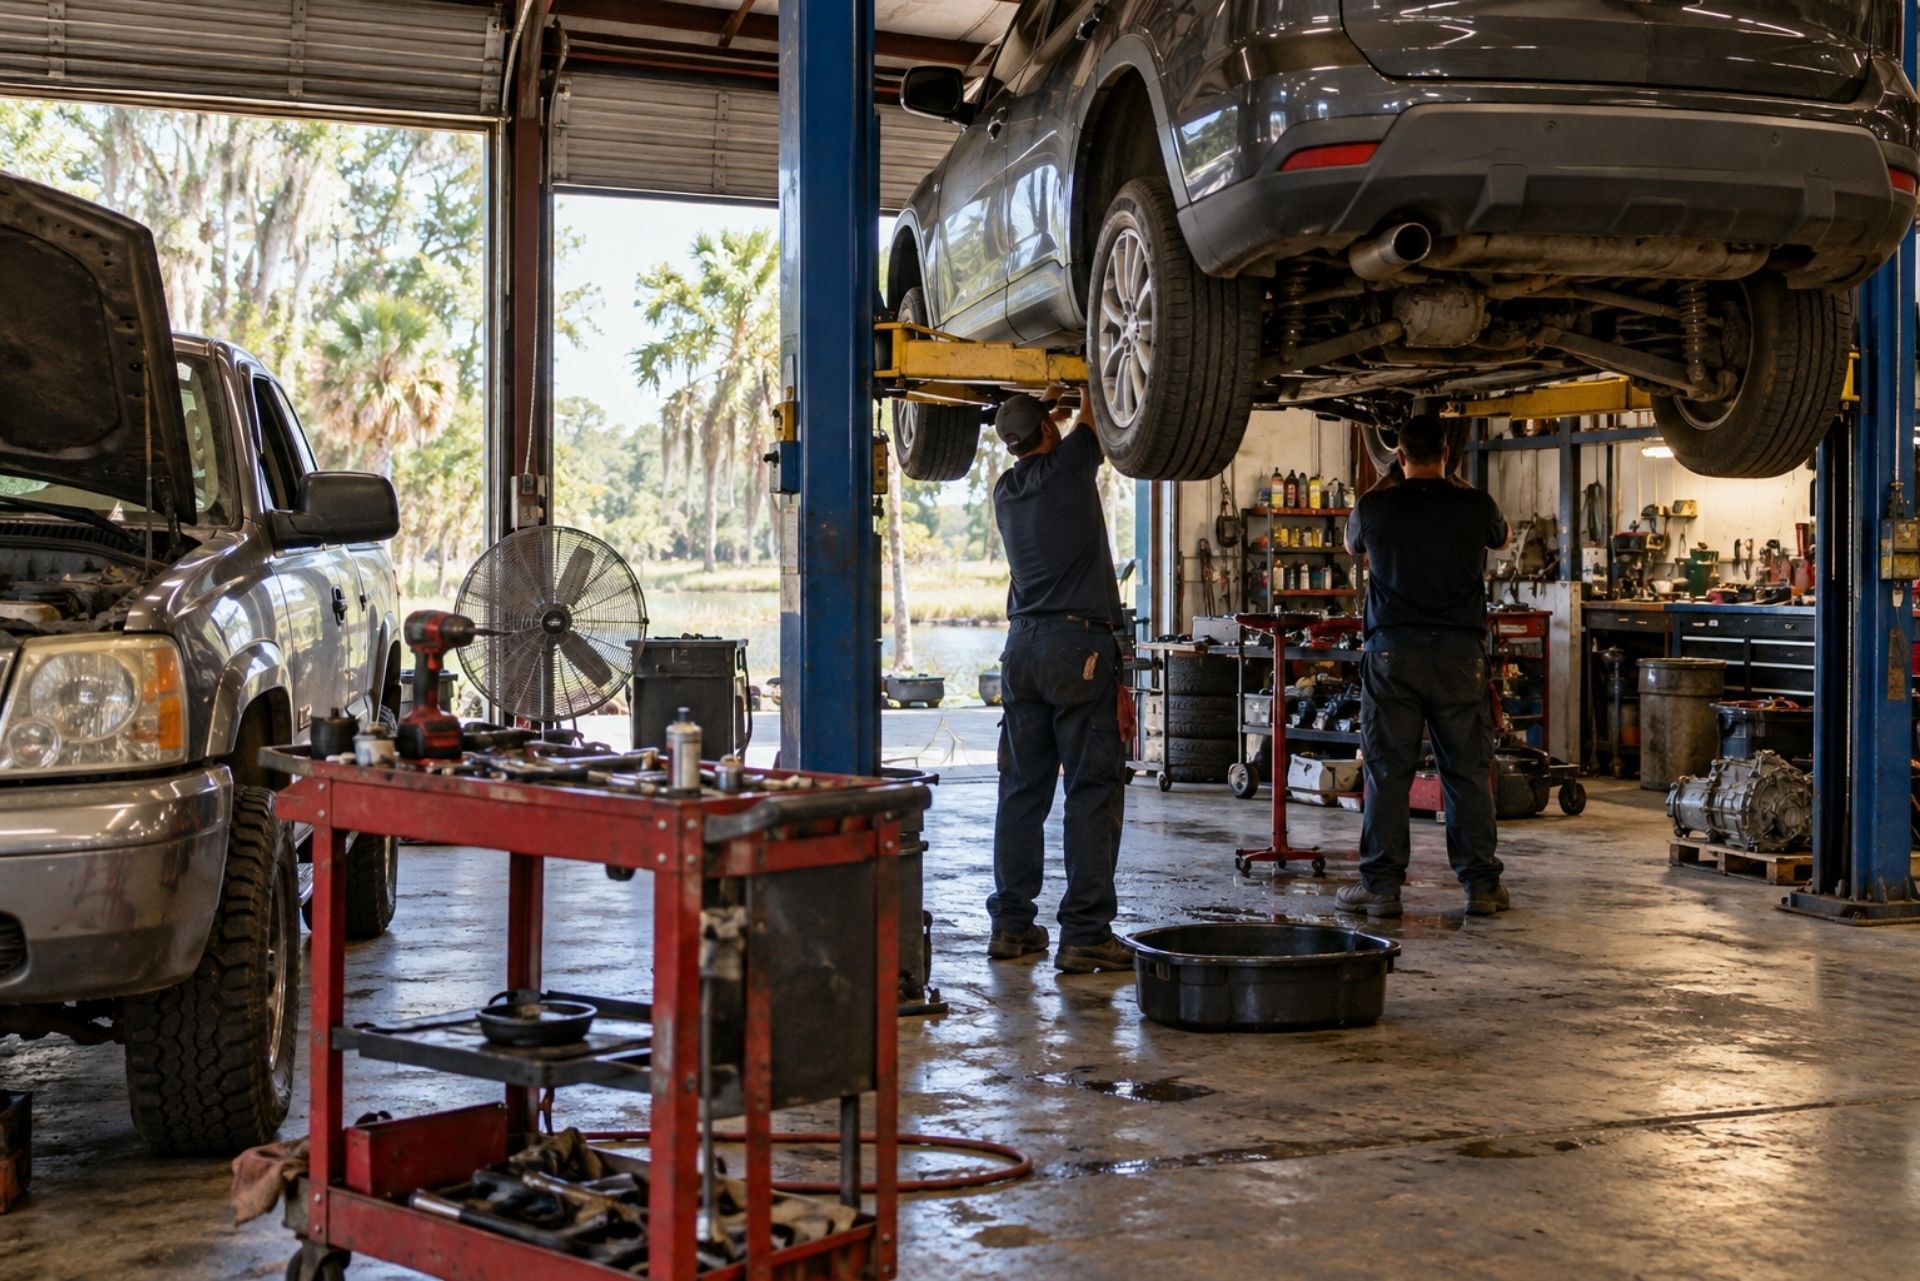
Lift claims are messy because they often involve two or three coverages at the same time. Picture a two-post lift arm slipping. The customer's sedan drops, scrapes the car parked next to it, and pins a tech's hand. The dropped sedan and the neighboring customer car typically go to garagekeepers. The tech's injury goes to workers' comp. Damage to the lift itself falls under your property or equipment coverage, if you scheduled it.


Slip-and-fall claims usually go to garage liability. Oil sheen, coolant puddles and hoses stretched across walkways cause most of them. Many shops let customers wander into the bay to "see the problem," and that is how a routine estimate becomes a bodily injury claim. A rope line and a sign cost very little by comparison.


The 2026 reforms also affect what these claims are worth. Under Act 466, juries may now see the amount actually paid for medical care instead of the original billed price. That could narrow some injury awards. Your carrier will still look closely at your inspection records, so keep annual lift inspection paperwork where you can find it quickly.

Feature Basic Coverage Extended Coverage
Property valuation Actual cash value (depreciated) Replacement cost (new item price)
Liability limit $100,000 $300,000 to $500,000
Valuables (jewelry, guns, art) Low sublimits, often $1,500 or less Scheduled items at appraised value
Water backup from drains Usually excluded May be added by endorsement
Loss of use Limited dollar cap Higher cap or longer timeframe
Flood Not covered Still not covered (needs NFIP or private flood)
Named storm deductible Percentage applies Percentage applies, sometimes lower options

How coverage choices change a Louisiana homeowners premium. Structure only — your rate depends on your property. [CONFIRM figures]

How coverage choices change a Louisiana homeowners premium. Structure only — your rate depends on your property. [CONFIRM figures]

Scenario Dwelling limit All-other-perils deductible Named-storm deductible
Newer build, inland St. Tammany $350,000 $1,000 2%
Newer build, higher wind zone $350,000 $1,000 5%
Older home, updated roof $275,000 $2,500 2%
Older home, original roof $275,000 $2,500 5%
Fortified roof designation $400,000 $1,000 2%
Rebuilt after a prior claim $400,000 $2,500 5%
Bundled with auto $350,000 $1,000 2%

Flooded Vehicles and Louisiana Weather Hazards

In Slidell and along the lake, flooding is a planning issue every season, not a rare event. When water reaches customer vehicles stored at your shop, garagekeepers may be the only coverage that responds. Whether it does depends on the policy details. Legal Liability forms may pay only if you were negligent, for example if you ignored an evacuation order with keys in hand. Direct Primary forms with comprehensive coverage may pay regardless of fault, subject to deductibles and any flood exclusions.


Pay attention to the per-vehicle and per-location limits. A $100,000 per-location limit disappears quickly when twelve cars take on water.


After a flood, Louisiana's titling rules also come into play. A vehicle declared a total loss from water damage must receive a Certificate of Destruction and cannot be rebuilt or resold. Vehicles with water damage to the powertrain or electrical system that aren't totaled must carry a "Water Damage" title brand. Customers will ask you about this, so knowing the rules helps.


Write a storm plan that covers when you'll call customers, where you can move cars to higher ground, and who keeps the keys. Then confirm with your agent how your policy treats vehicles you relocate.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Common Questions About Shop Insurance

Do I really need garagekeepers if I'm careful? Yes. Careful shops still have fires, storms and break-ins, and a regular liability policy typically won't pay for customer cars in your care.


Does my personal auto policy cover test drives? Usually not. Driving a customer's car for business is typically handled by your garage policy, not by an employee's personal coverage.


Are commercial rates going down in Louisiana? Some personal auto lines saw rate decreases of 6% to 7.5% finalized in March 2026. The Commissioner also noted that commercial auto rates remain extremely high, so comparing carriers is still worthwhile.


What if a customer's car floods on my lot? Garagekeepers may cover it, depending on your form and its exclusions. Check this with your agent before hurricane season, not after.


Who pays if my mechanic gets hurt? Workers' compensation does. Garage liability and garagekeepers don't cover your own employees' injuries.


Is the cost of Direct Primary worth it? For many shops, yes. It lets you pay for customer damage without having to prove fault first, which protects your reputation as much as your bank account.

Making the Right Choice for Your Garage

A sound shop program comes down to a few questions. Who's protected if someone gets hurt? Who pays when a customer's car is damaged? And what happens when the water rises? Garage liability, garagekeepers in the right form, workers' comp and a realistic flood plan cover most of what goes wrong in a St. Tammany Parish bay.


You don't need to work out the policy language alone. Our process is simple: start online, we shop several carriers for you, and you pick the plan that fits. We'll also explain the exclusions before you sign, so the policy matches how your shop actually runs, whether that's two bays in Covington or a full-service operation in Slidell.


Ready to see where you stand? Start a Quote with Kyle Beerbohm at Aubert Insurance Agency. Your customers trust you with their vehicles, and your coverage should back that up.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
