













Covington & Slidell Independent Insurance Agents
A single crew injury on a push boat in the Tchefuncte can cost far more than the boat itself. That gap between what most owners insure and what actually drives maritime losses is where coverage decisions in Louisiana matter most.
Understanding Louisiana Ocean Marine Insurance Basics
Ocean marine insurance in Louisiana covers three things: physical damage to your vessel, liability for injuries to crew and third parties, and specialized risks tied to docks, marinas, and cargo. Aubert Insurance Agency has helped owners in Covington and Slidell sort out these exposures since 1910, matching each risk to the right policy form.
The structure is different from a standard business package. A commercial general liability policy usually excludes watercraft. A homeowners policy typically caps or excludes boats used for business. Land-based workers comp may not respond to a deckhand at all. Ocean marine policies fill these gaps, but only when they are written to match how the vessel and facility are actually used.
Most Louisiana marine accounts end up with a combination of coverages. A tug operator may carry hull, P&I, and pollution coverage. A marina owner may carry marine general liability plus marina operators legal liability. A shipper moving goods through the Port of New Orleans may need cargo coverage that follows the freight from warehouse to warehouse. Each section below breaks down one piece.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Hull and Protection and Indemnity for Workboats
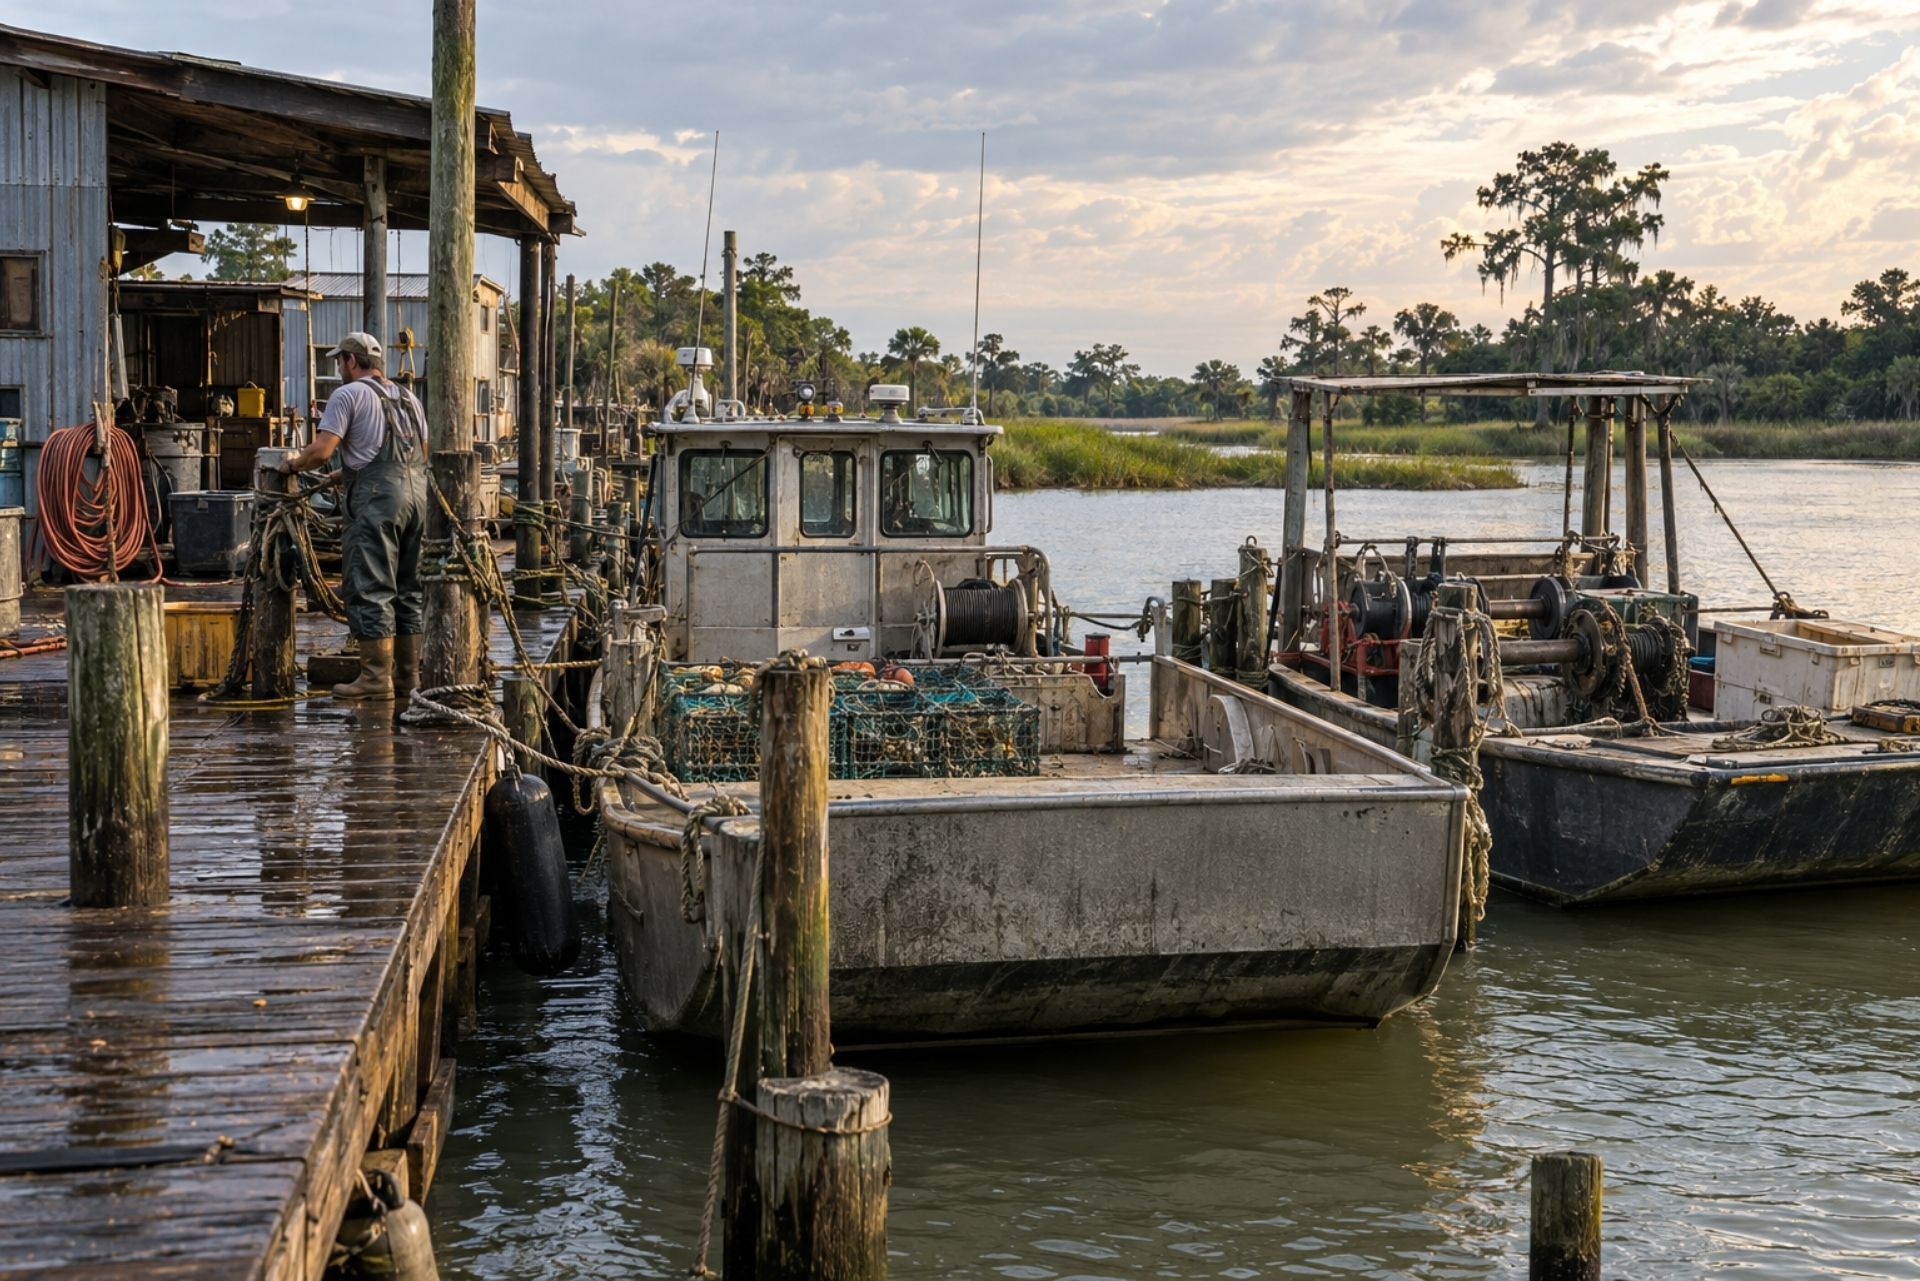
Hull coverage pays for physical loss or damage to the vessel itself: the hull, machinery, and equipment. Think of a crew boat striking a submerged piling near the Rigolets, a fire in the engine room, or a sinking at the dock during a storm. Policies are typically written on an agreed value basis, so the amount you insure the boat for matters. Undervaluing to save premium is one of the most common mistakes we see, and it can leave an owner short when a total loss happens.
Protection and Indemnity (P&I) is the liability side. It may respond to:
- Crew injuries and illness, including Jones Act claims
- Third-party bodily injury, such as a passenger or a worker from another company
- Collision damage to other vessels (sometimes handled by a running down clause in the hull form)
- Wreck removal when a sunken vessel creates a hazard
- Damage to docks, bridges, and other fixed objects
Pollution liability is often written separately. If your workboat carries fuel or works near sensitive marshland, ask about it directly rather than assuming P&I covers a spill.
Timing also matters this year. With Hurricane Isaias approaching the Gulf in October 2026, brokers have warned of a possible acceleration in premium increases if significant losses occur. Reviewing your hurricane plan and named storm deductible before a renewal is a smart move.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Marine General Liability for Docks and Marinas
A standard CGL policy usually carves out watercraft exposures, which leaves dock operators, marinas, boat repair yards, and waterfront contractors with a hole in their protection. Marine general liability is built for businesses operating on or near the water.
Consider a marina in Slidell. A customer slips on a wet fuel dock. A tenant's boat breaks loose during a squall and damages three others. A yard employee drops a vessel while hauling it out. Marine general liability typically handles premises injuries, while a companion coverage called marina operators legal liability may respond to damage to customer boats in your care, custody, or control. That second piece is the one owners forget, and it is often the bigger exposure.
Marinas are also tightening requirements for the people who rent slips. Many Louisiana marinas now require slip tenants to carry minimum liability limits of $300,000 to $500,000. If you own a marina, make sure your lease language and certificate tracking actually enforce this. If you rent a slip, check your boat policy before your lease renews.
One more Louisiana-specific detail: effective January 1, 2026, Louisiana adopted a modified comparative fault rule with a 51% bar for state tort claims. For land-based premises claims, an injured person found more than half at fault may recover nothing, which can shift how some dock injury claims are defended.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Protecting Assets with Marine Cargo Coverage
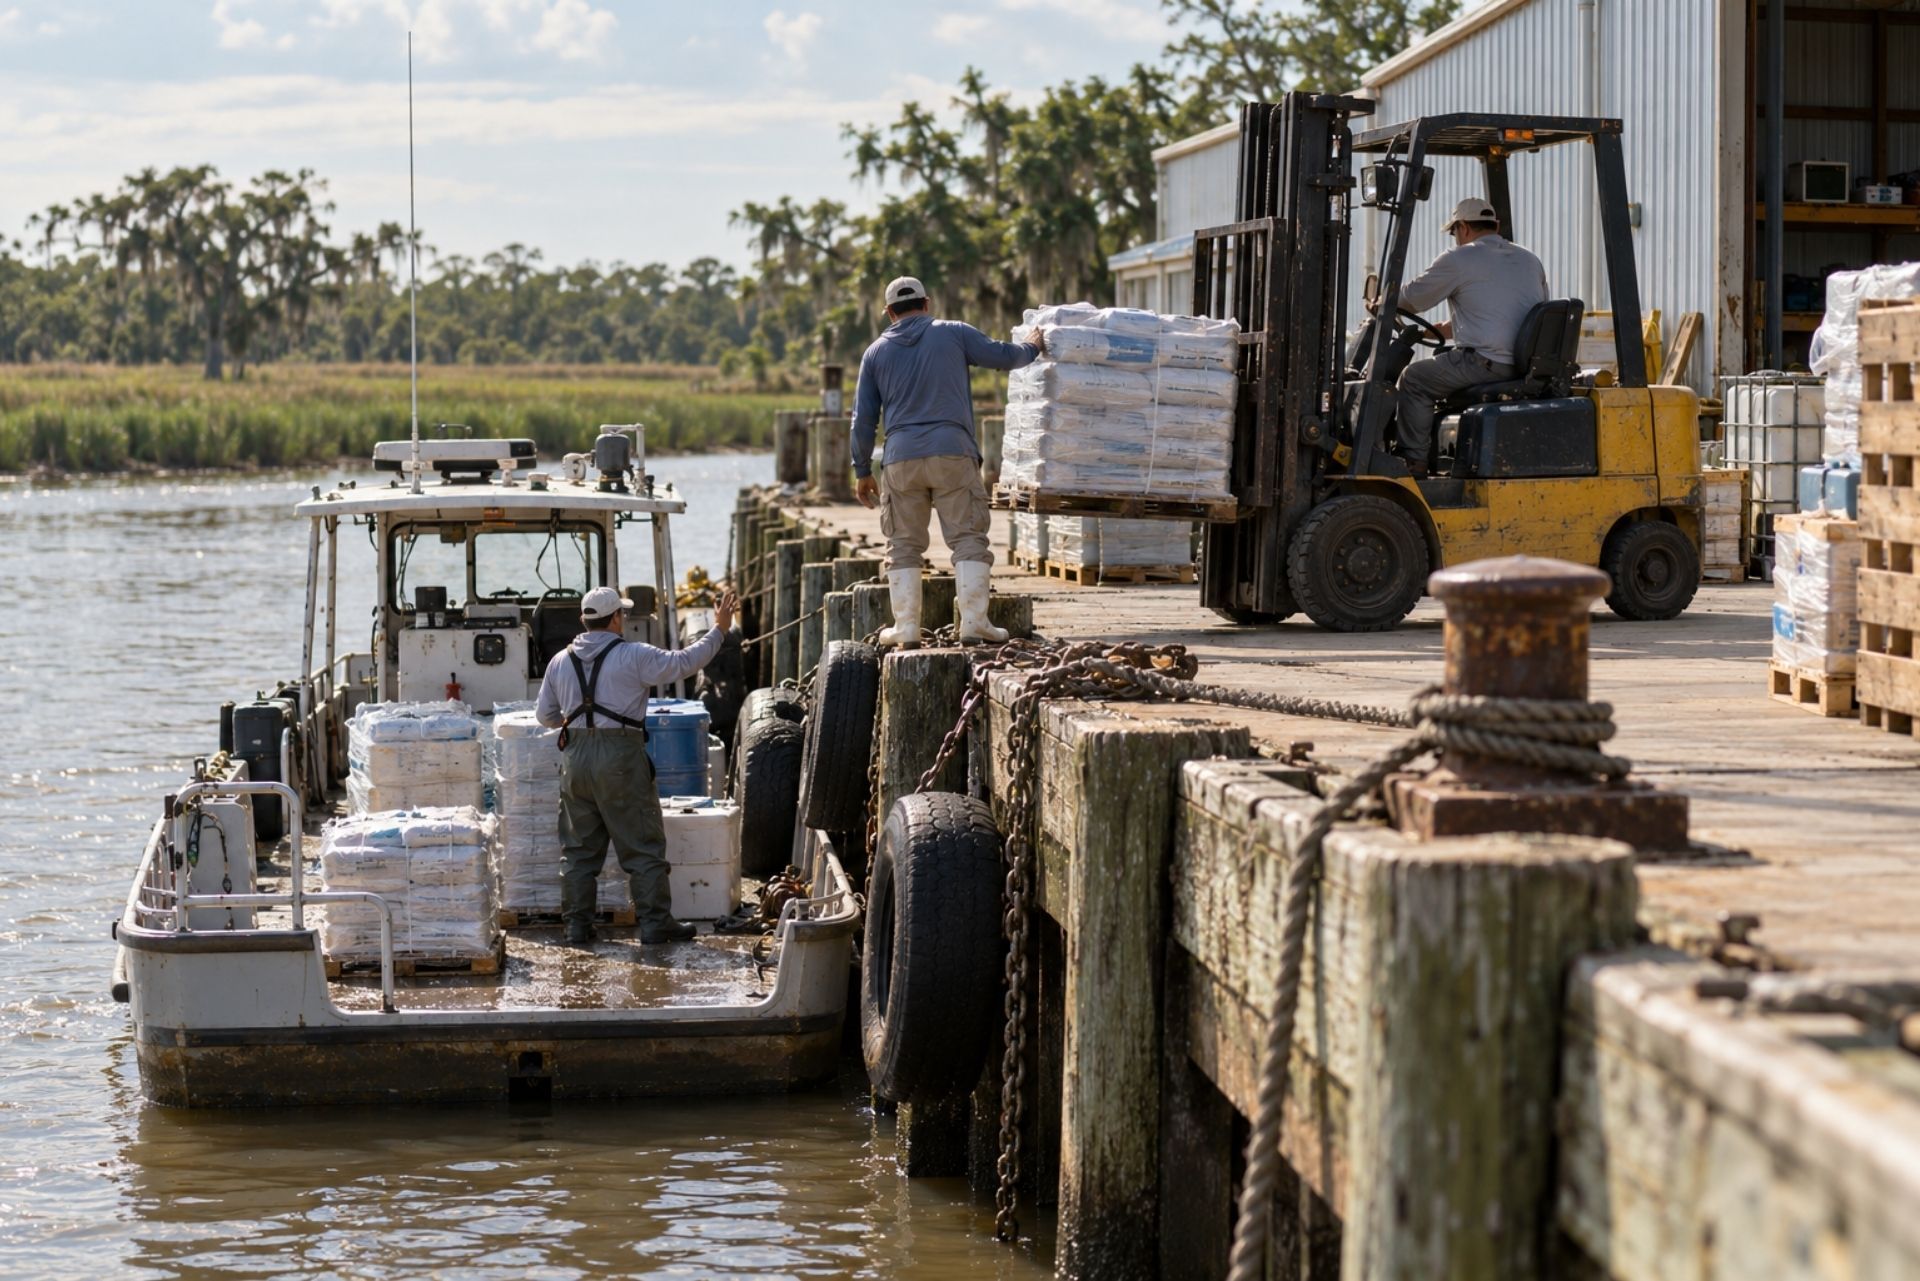
Carriers moving your goods rarely pay full value when something goes wrong. Ocean carriers often limit their liability by law or contract, and a general average declaration after a casualty can leave cargo owners contributing to salvage costs even when their own freight arrived intact. Cargo insurance protects the value of the goods themselves.
Louisiana businesses moving freight through the river system have plenty of reasons to pay attention. Port NOLA applied a 2.92% tariff increase in 2026, including bulk cargo terminal use fees of $0.153 per ton, so the cost of moving goods is climbing. Expansion is coming too: the Army Corps of Engineers granted the federal permit for the Louisiana International Terminal in August 2026, which points to more container traffic in the years ahead.
A few policy points to review:
- Warehouse to warehouse wording, which may extend coverage from origin through final delivery
- Valuation clauses, often invoice value plus freight and a percentage markup
- Open cargo policies for businesses shipping regularly, versus single trip certificates
- Exclusions for improper packing, delay, and inherent vice
A seafood distributor shipping frozen product, for example, may need refrigeration breakdown coverage that a basic form does not include.
How Jones Act Exposure Differs From State Workers Comp
This is where Louisiana marine owners make their most expensive assumptions. Under the Jones Act, a seaman injured on the job can sue the employer for negligence. A seaman may also bring an unseaworthiness claim against the vessel owner, which requires no proof of negligence at all, only that the vessel, its equipment, or its crew was not reasonably fit for the job.
Louisiana workers comp works on a different model. It is a no-fault system: the injured worker receives benefits regardless of who caused the accident, but the benefits are set by statute and capped. In exchange, the employee generally cannot sue the employer. Jones Act claims carry no such caps, and verdicts can include lost future earnings and pain and suffering.
Jones Act coverage is typically provided through the P&I policy, not through a workers comp policy. Some carriers may offer a maritime employers liability endorsement on a workers comp form, but that is a different product with its own wording. A Covington contractor who runs a small crew boat for a few jobs a year and only carries state comp may have no coverage for a deckhand's lawsuit. Dock workers who are not seamen may fall under federal longshore rules instead, which brings its own coverage requirements.
Comparing Maritime Remedies and State Benefits
| Feature | Jones Act (Seamen) | Louisiana Workers Comp |
|---|---|---|
| Who qualifies | Seamen who contribute to a vessel's mission and have substantial connection to a vessel in navigation | Most land-based employees |
| Fault requirement | Must prove employer negligence or unseaworthiness | No fault required |
| Right to sue employer | Yes | Generally no |
| Benefit limits | No statutory caps on damages | Statutory schedules and maximums |
| Maintenance and Cure | Yes: daily living costs plus medical care until maximum improvement | Not applicable |
| Pain and suffering | Recoverable | Not recoverable |
| Typical coverage source | P&I policy | Workers comp policy |
Maintenance and Cure deserves attention because it applies even without fault. Maintenance rates for Louisiana maritime workers in 2026 typically range from $30 to $65 per day to reflect actual living expenses, and cure covers medical treatment. Those payments can run for months, so your P&I limits and deductibles need to account for them.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Frequently Asked Questions About Marine Insurance
Does my commercial general liability policy cover my workboat? Usually not. Most CGL forms exclude watercraft above a certain size or used for business, so you typically need P&I or marine general liability.
Is my deckhand covered by Louisiana workers comp? If the deckhand qualifies as a seaman, state comp generally will not be the remedy. Jones Act exposure is typically insured through your P&I policy.
What is Maintenance and Cure? It is a daily living allowance plus medical care owed to an injured seaman regardless of fault, paid until the worker reaches maximum medical improvement.
Do I need cargo insurance if the shipping company has insurance? Yes, in most cases. Carrier liability is often limited, and it may not cover the full value of your goods or general average contributions.
Will hurricane season change my marine premiums? It may. Brokers have warned that significant storm losses in 2026 could speed up premium increases, so review deductibles and storm plans early.
My marina wants proof of liability coverage. How much do I need? Many Louisiana marinas now ask for $300,000 to $500,000 in liability limits. Check your lease and confirm your boat policy meets it.
Making the Right Choice for Your Vessel
Marine coverage in Louisiana rarely fits into one policy. Hull protects the boat, P&I protects you from crew and third-party claims, marine general liability covers what happens at the dock, and cargo coverage protects the goods moving through our ports. The Jones Act piece is the one that catches owners off guard, because the instinct to rely on state workers comp can leave a seaman's lawsuit completely uninsured.
As an independent agency, Aubert Insurance compares options from multiple carriers and explains how each policy form works, including the exclusions that matter most on the water. That matters when one wording difference can decide whether a claim gets paid.
If you own a workboat, run a marina, or ship freight through the river, Start a Quote with Kyle Beerbohm at Aubert Insurance Agency. Kyle can review your operations and make sure your specific Louisiana maritime exposures are addressed correctly before the next storm or the next claim.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













