













Covington & Slidell Independent Insurance Agents
Picture a three-person CPA firm in a leased suite off Highway 190 in Covington. The work is tidy, the clients are loyal, and then the landlord sends a lease renewal demanding $1 million in liability limits plus proof of contents coverage. Suddenly insurance becomes a deadline instead of an afterthought.
That scenario plays out constantly across St. Tammany Parish. Accountants, marketing and insurance agencies, and independent consultants all run lean offices, but their risks are not small. A single phishing email, a disgruntled former employee, or a hurricane that shreds a window wall can stall a firm for weeks.
The good news is that the market is friendlier than it was a few years ago. Louisiana's property market has stabilized in 2026, with average small commercial rate changes dropping to 0.1% compared to 14% in 2023. More carriers are competing for your business, which gives office-based firms real options.
What follows covers how professional office insurance in Louisiana typically comes together, from the base policy to the add-ons, lease clauses, and wind questions that trip people up.
Understanding Business Owners Policies for Louisiana Professionals
A Business Owners Policy (BOP) typically bundles general liability and commercial property coverage into one package for accountants, agencies, and consultants in Louisiana. It usually costs less than buying each piece separately. Aubert Insurance Agency has helped businesses in Covington and Slidell compare these policies since 1910.
The appeal is simplicity. Instead of juggling a liability policy from one carrier and a property policy from another, a BOP puts both under one contract with one renewal date. Many carriers also fold in business income coverage, which may replace lost revenue if a covered event forces your office to close temporarily.
Costs are often modest for low-risk office operations. Roughly 42% of small businesses in the professional office sector pay less than $50 per month for a standard BOP in 2026. Your price depends on square footage, payroll, location, building construction, and claims history, so your quote may land above or below that figure.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Core Coverage for Accountants, Agencies, and Consultants
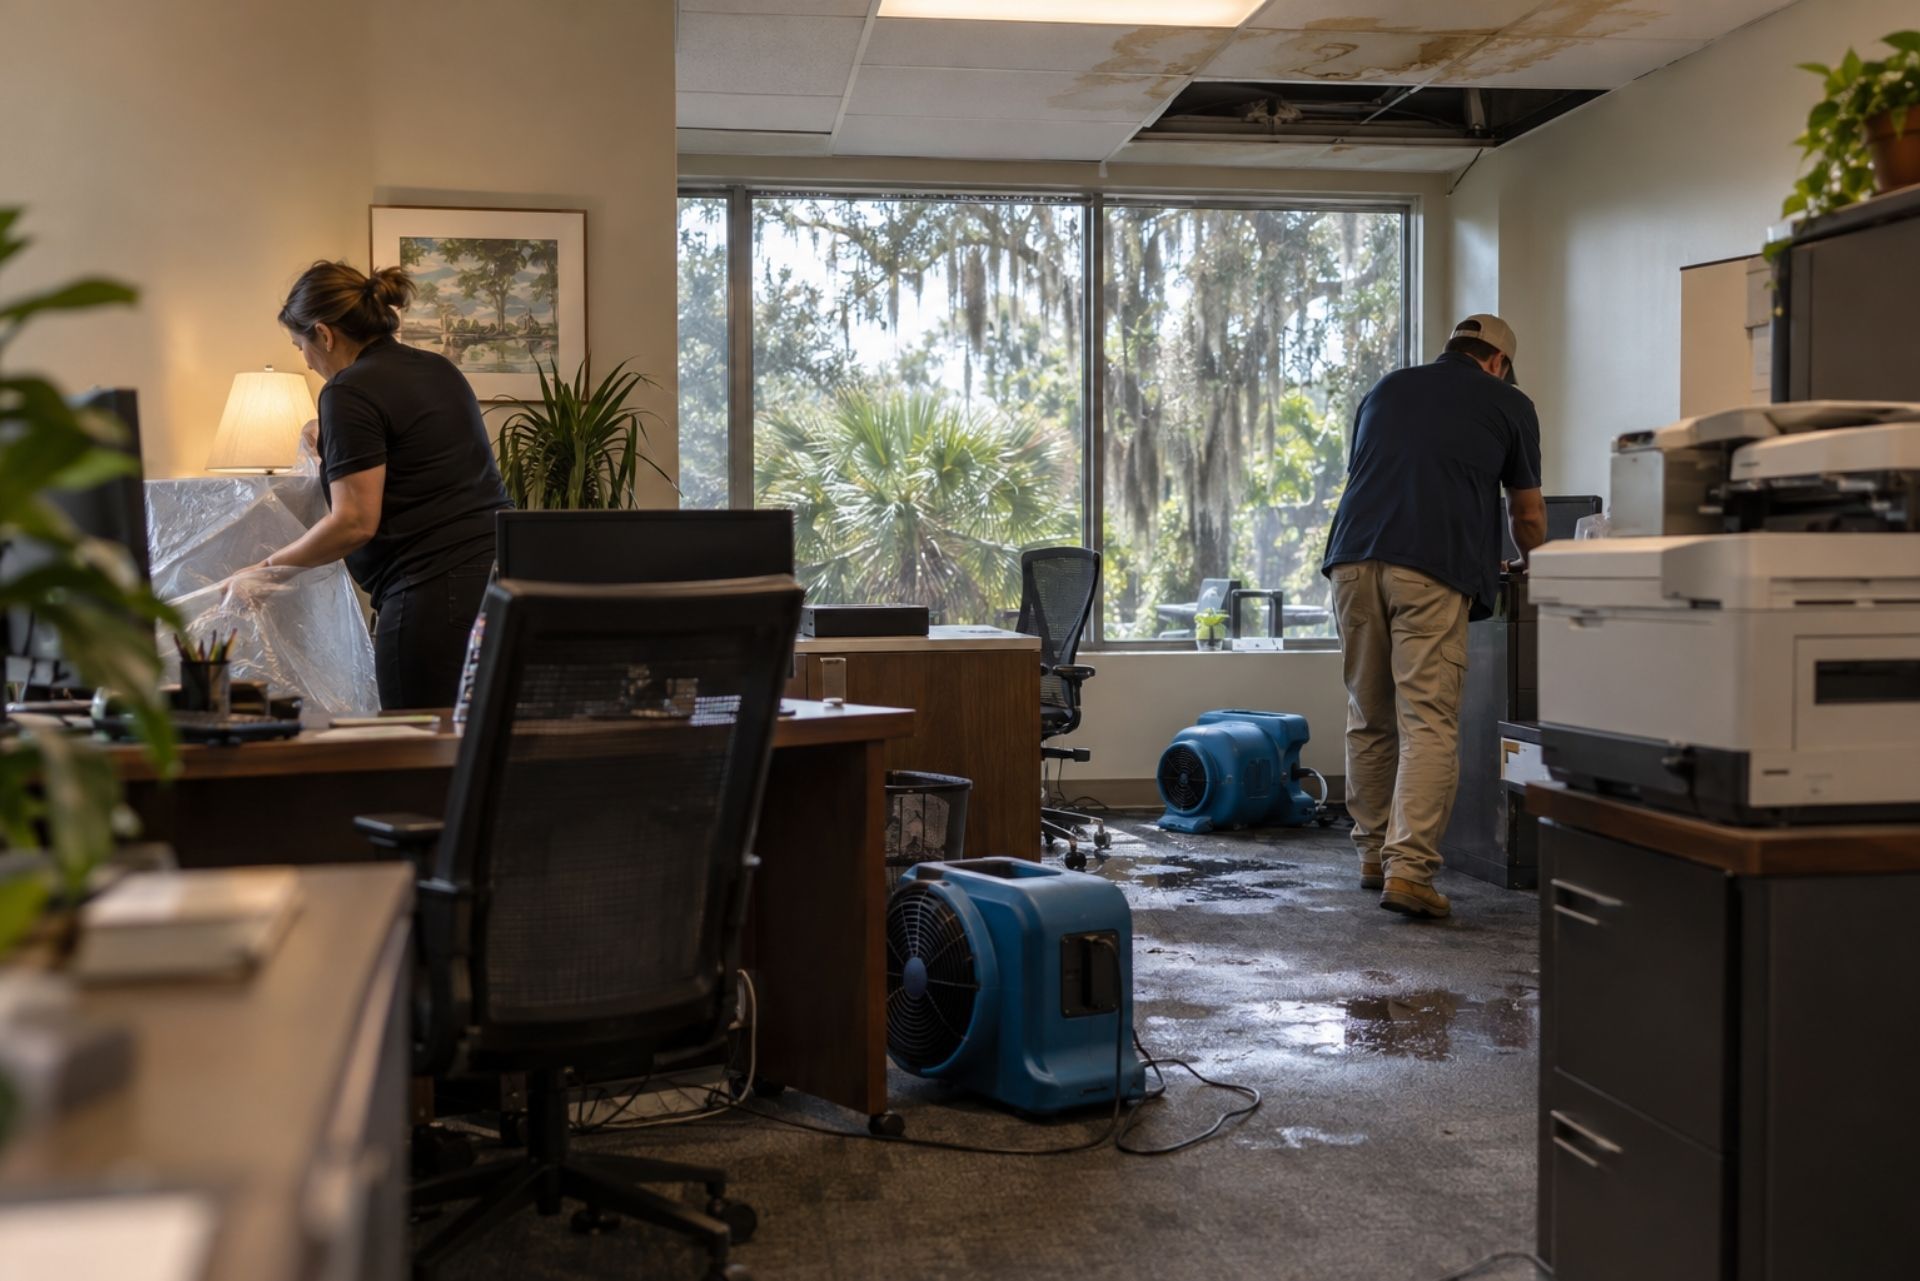
Office work feels safe, but claims come from ordinary moments. A client trips over a laptop cord in your reception area. A pipe bursts overnight and soaks your servers and filing cabinets. A delivery driver slips on a freshly mopped floor.
Here is what a professional office BOP may protect against, depending on the carrier and form:
- General liability: Bodily injury and property damage claims from visitors, plus some advertising injury claims.
- Business personal property: Computers, furniture, printers, and other contents you own, even in a leased space.
- Business income: Lost earnings and ongoing expenses after a covered property loss.
- Valuable papers and records: Costs to recreate damaged client files, which matters a lot for tax preparers.
- Electronic data: Some policies typically include limited coverage to restore data lost in a covered physical event.
One common mistake: assuming "data loss" coverage in a BOP handles a hack. It usually does not. That limited data coverage typically responds to physical causes like fire or water, not cyberattacks. If you want to see what your firm would pay, Start a Quote and we will compare forms side by side.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Critical Add-Ons: Cyber Liability and Employment Practices
The two gaps we see most often in professional offices are cyber and employment-related claims. Neither is typically covered by a standard BOP.
Cyber Liability
Accounting firms hold Social Security numbers, bank details, and tax records, which makes them prime targets. One industry observer put it bluntly: for most CPA firms, cyber insurance is no longer optional, and failing to meet MFA and EDR requirements can result in denied claims or total exclusion from the market. Translation: carriers now want multi-factor authentication and endpoint detection software in place before they will write you, and they may check after a claim. A cyber policy may cover breach notification, forensic investigation, ransomware response, and lawsuits from affected clients.
Employment Practices Liability (EPLI)
Even a firm with four employees can face a wrongful termination, discrimination, or harassment claim. Defense costs alone can run high before anyone reaches a courtroom. EPLI may cover legal defense and settlements for these workplace disputes. Some carriers offer it as a BOP endorsement, while others require a standalone policy with broader terms. Ask whether your EPLI includes third-party coverage, which can matter for agencies whose staff deal heavily with outside clients.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Meeting Tenant Lease Requirements in Louisiana
Most professional offices in Covington and Slidell lease their space, and commercial leases almost always include an insurance section. Landlords want to make sure that if your client gets hurt in your suite, or your space catches fire, their building and their own policy are not the first line of defense.
Typical lease requirements include:
- General liability limits, often $1 million per occurrence and $2 million aggregate
- The landlord named as an additional insured on your liability policy
- Coverage for your contents and any tenant improvements you paid for
- A waiver of subrogation, which prevents your insurer from suing the landlord after a claim
- Advance notice if your policy is canceled
The detail people miss is tenant improvements. If you paid to build out conference rooms or install custom cabinetry, the lease may make you responsible for insuring those upgrades. Read the insurance clause before you sign, not when the property manager emails asking for a certificate. We review lease language regularly and can tell you whether a quoted BOP actually satisfies it.
How Jones Act Exposure Differs From State Workers Comp
Managing Wind and Hail Coverage Challenges
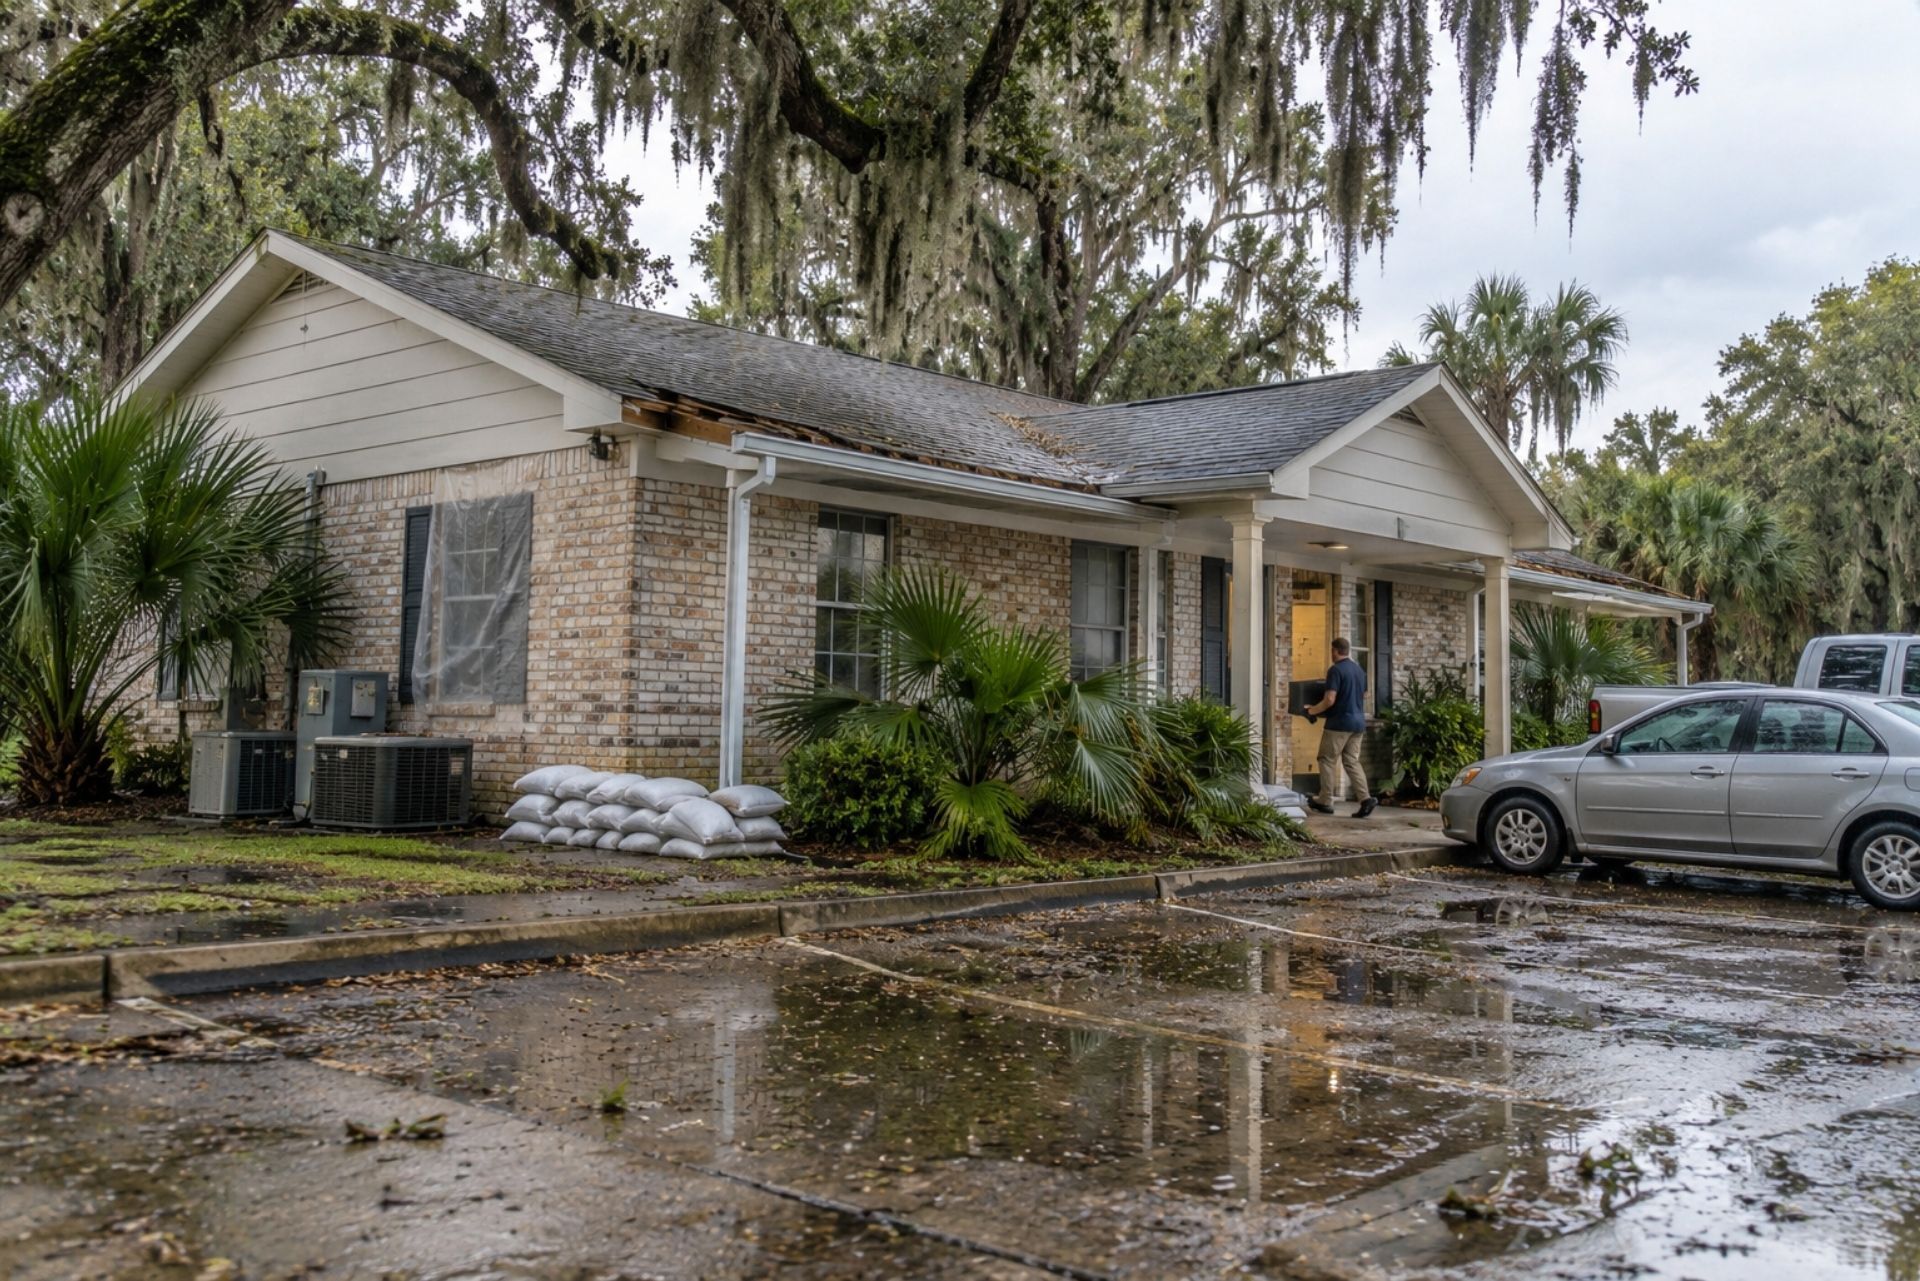
Wind is the issue that makes Louisiana coverage different. Many policies in coastal parishes either exclude wind and hail, carry a separate percentage deductible for named storms, or require a separate wind policy entirely. For a tenant, that usually comes down to your contents: computers, furniture, records, and equipment.
Check the wind deductible carefully. A 2% or 5% named storm deductible is calculated on your insured value, not a flat dollar amount, so a higher contents limit means a higher out-of-pocket hit after a hurricane.
For firms that end up in the state's insurer of last resort, there are new developments. Louisiana Citizens has
raised commercial limits to $10 million for a single building and $3.2 million for contents. The Property Insurance Company of America is also slated to
take over commercial policies from Louisiana Citizens in 2026, with officials saying policyholders may see premium reductions of 15% to 40%. Since 2024, more than 20 new insurers have been licensed in Louisiana, so shopping your wind coverage is worth the effort.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Comparing Professional Liability vs. General Liability
New business owners often think general liability covers mistakes in their work. It typically does not. Professional liability, also called errors and omissions (E&O), is a separate policy and usually sits outside a BOP.
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| What it covers | Physical injuries and property damage | Mistakes, oversights, bad advice |
| Example claim | Client slips in your lobby | Missed tax deadline costs a client penalties |
| Included in a BOP? | Usually yes | Usually no |
| Who needs it | Nearly every office with visitors | Accountants, consultants, agencies giving advice |
| Policy trigger | Usually occurrence-based | Usually claims-made |
That last row matters. With a claims-made policy, coverage typically depends on the policy being active when the claim is filed, not just when the work happened. Switching carriers without arranging prior acts coverage can leave years of past work uninsured.
How Jones Act Exposure Differs From State Workers Comp
Frequently Asked Questions About Office Insurance
Do I need insurance if I work from home? Probably. Homeowners policies typically limit or exclude business property and business liability, so a home-based consultant may need a BOP or a home business endorsement.
What does a BOP cover? A BOP usually combines general liability, business property, and business income coverage. Cyber, EPLI, and professional liability are typically separate.
Is wind automatically included in my office policy? Not always. In many Louisiana parishes, wind may be excluded, carry a separate deductible, or require its own policy.
How much liability coverage does my landlord want? Many commercial leases ask for $1 million per occurrence and $2 million aggregate, but your lease controls. Check the insurance clause before signing.
Are rates going down in Louisiana? For many businesses, things are leveling off. The insurance commissioner noted the state is seeing fewer requests for rate increases and more requests for rate decreases as the 2024 reforms take hold.
Can I add cyber coverage to my BOP? Some carriers offer a limited cyber endorsement. Firms holding sensitive financial data typically need a standalone policy with higher limits.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Making the Right Choice for Your Firm
A solid setup for a Louisiana professional office usually starts with a BOP, then layers on cyber, EPLI, and professional liability based on what you actually do. From there, you match the policy to your lease and make sure wind coverage on your contents carries a deductible you can live with.
The firms that get burned are rarely the ones who skipped insurance altogether. They are the ones who bought a policy without reading the exclusions, assumed the BOP covered a hack, or found out after a storm that their wind deductible was a percentage instead of a flat amount.
As an independent agency, Aubert Insurance Agency compares coverage across multiple carriers and walks you through how each contract works before you commit. Sit down with Kyle Beerbohm to review your lease, your data risks, and your office contents. When you are ready, Start a Quote and let us do the shopping.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













