













Bogalusa LA Flood Insurance

Covington & Slidell Independent Insurance Agents

A standard homeowners policy in Bogalusa typically excludes damage from rising water, so protecting your home from Bogue Lusa Creek or Pearl River flooding requires a separate flood policy. Coverage may come from the National Flood Insurance Program or a private carrier, and even lower-risk properties outside mapped flood zones can qualify for affordable options.


Most people in Washington Parish don't think about flood coverage until the Pearl River climbs toward its banks or a slow-moving storm stalls over town and Bogue Lusa Creek starts backing up into yards. By then, it's usually too late to buy protection that will help. This guide covers what drives flood risk in Bogalusa, why the old mill neighborhoods deserve a closer look, how lower-risk homes can find reasonable rates, and why counting on federal aid is a gamble.

Understanding Bogalusa Flood Risks and Insurance Options

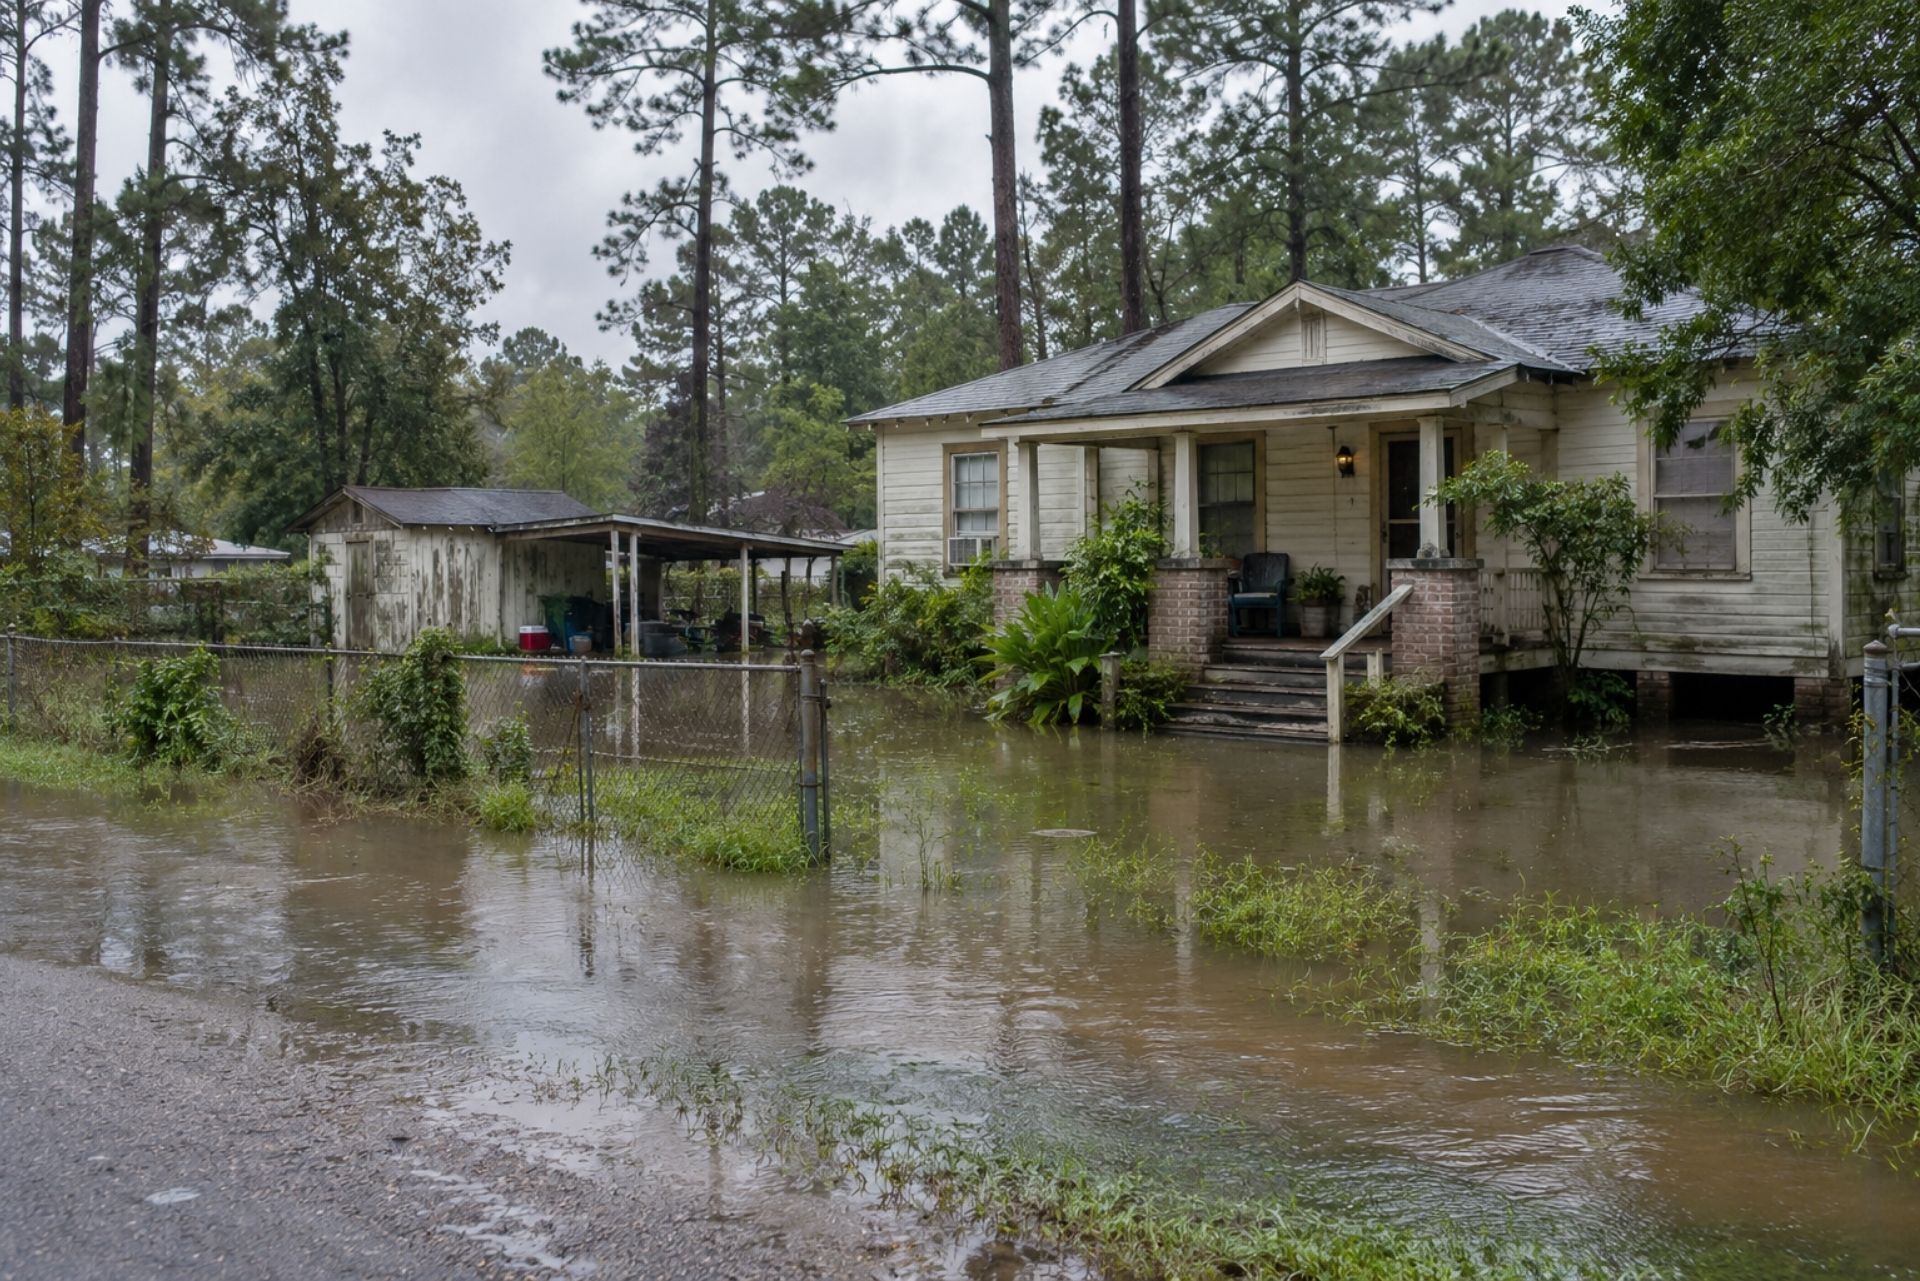
Bogalusa sits between two flood sources: Bogue Lusa Creek running through town and the Pearl River along its eastern edge. Homeowners insurance typically does not cover rising water from either one. That means residents who want protection need a separate flood policy, purchased through the NFIP or the private market.


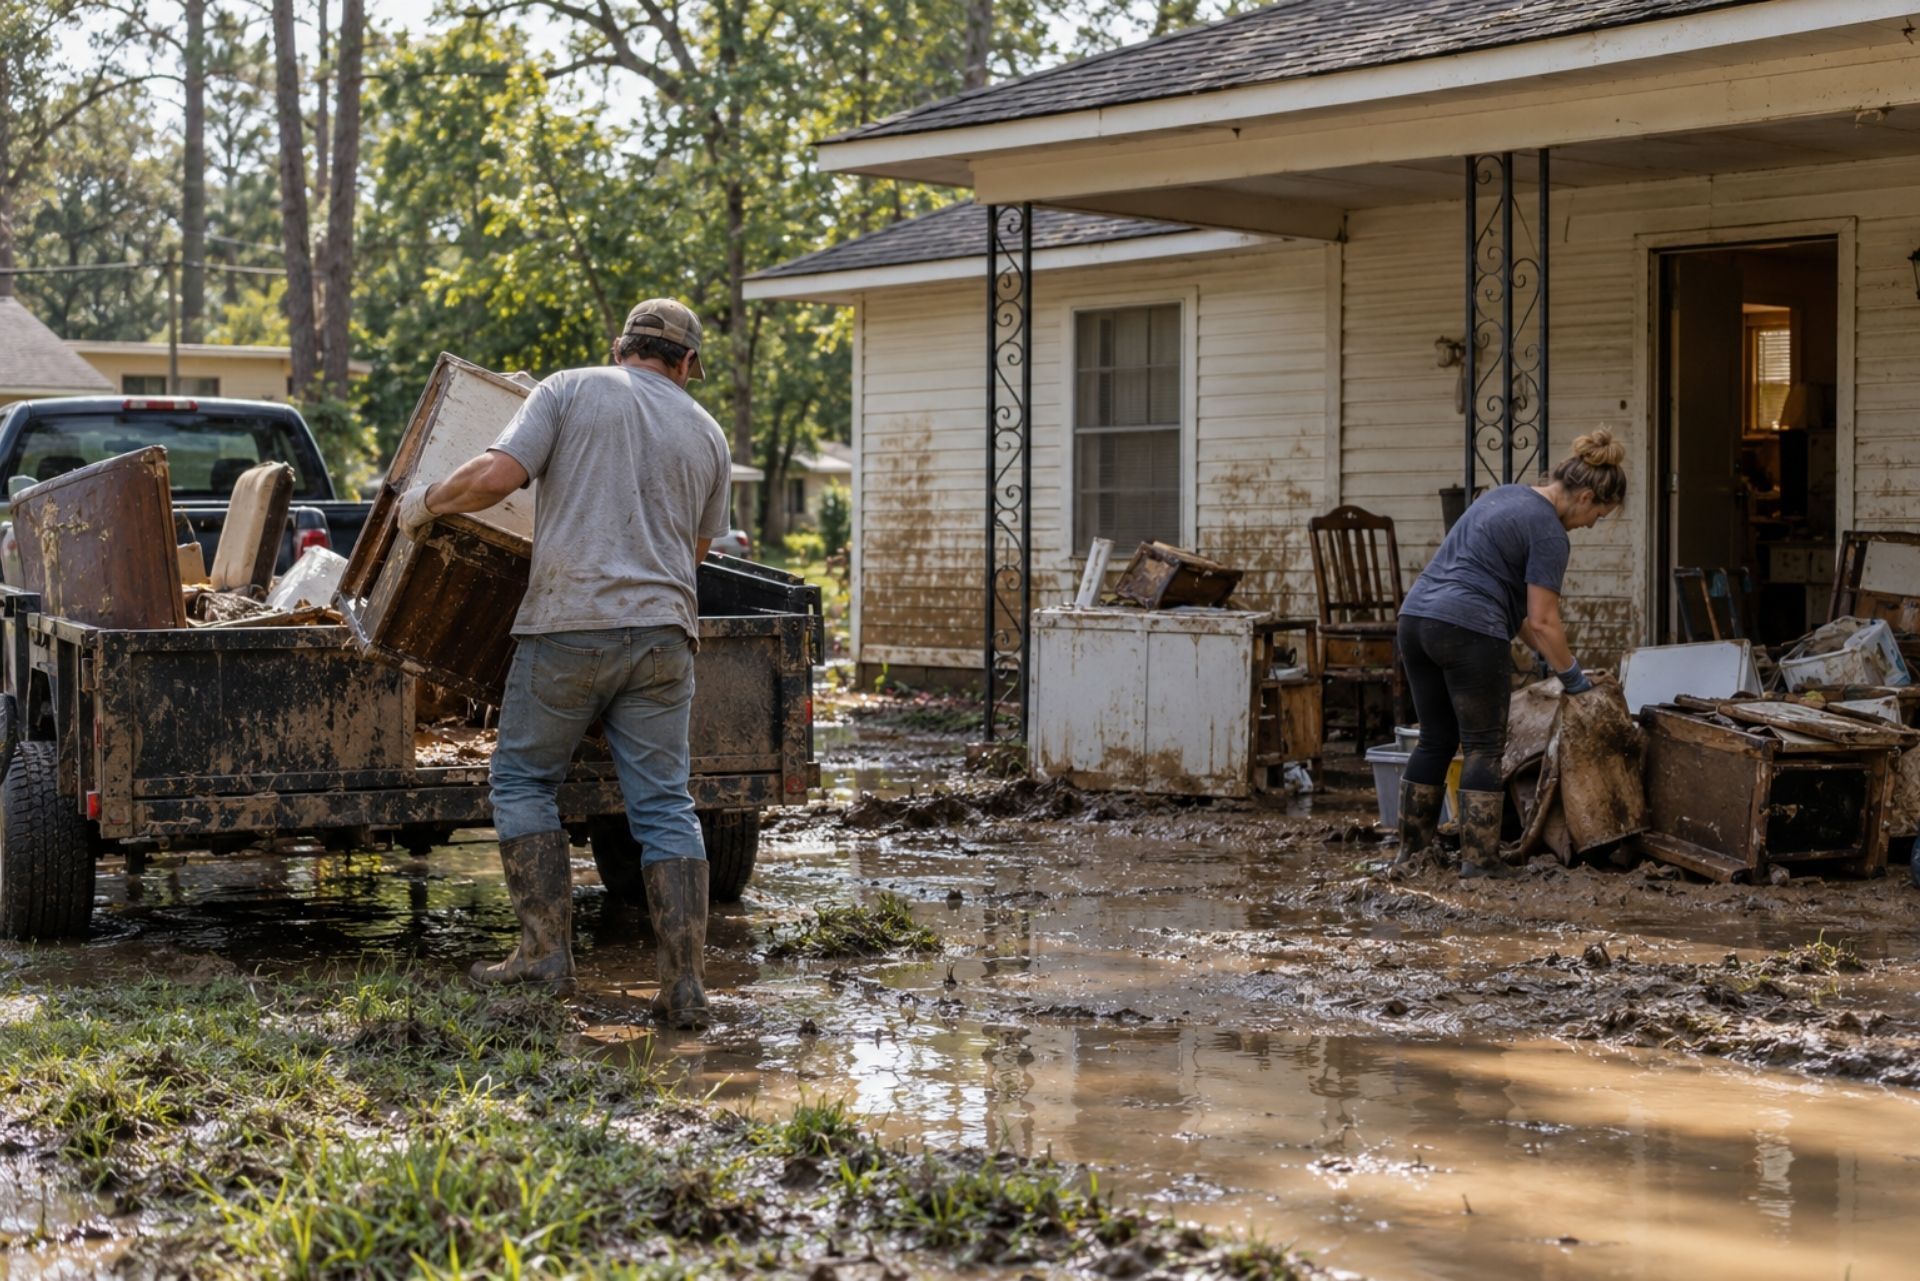
This catches a lot of homeowners off guard. A wind-driven roof leak during a storm may be covered under your homeowners policy, but water that enters your home from the ground up is a different claim entirely. We've seen families assume their mortgage-required coverage handled everything, only to learn after a heavy rain that the flood exclusion applied to their entire loss.


The cost of guessing wrong is steep. The average NFIP flood claim payout in Louisiana between 2020 and 2024 was roughly $82,614, which is far more than most families can absorb out of savings. Meanwhile, the average annual NFIP premium in Louisiana under FEMA's Risk Rating 2.0 sits around $1,420 for 2026.


One more detail matters here: the NFIP has a standard 30-day waiting period before a new policy takes effect. If you wait until the river gauge starts rising, you've waited too long.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

Here's a common scenario: you misjudge a curve and clip a late-model pickup, injuring the driver. A single ambulance ride, ER visit, and follow-up imaging can eat through $15,000 quickly. Anything above your limit can become your personal responsibility, which may put your savings, wages, or home at risk.

Scenario Dwelling limit All-other-perils deductible Named-storm deductible
Newer build, inland St. Tammany $350,000 $1,000 2%
Newer build, higher wind zone $350,000 $1,000 5%
Older home, updated roof $275,000 $2,500 2%
Older home, original roof $275,000 $2,500 5%
Fortified roof designation $400,000 $1,000 2%
Rebuilt after a prior claim $400,000 $2,500 5%
Bundled with auto $350,000 $1,000 2%

Living Near the Bogue Lusa Creek and Pearl River

The Pearl River has well-defined warning levels at Bogalusa. The National Weather Service sets flood stage at 18.0 feet, and on October 12, 2026, the river was reading about 6.15 feet. That calm reading is exactly the time to think about coverage, since a quiet river doesn't stay quiet for long during a wet spring.


Here's how the categories break down at the Bogalusa gauge, based on official Pearl River flood categories:


  • Action Stage (16 feet): Time to prepare and watch forecasts closely
  • Minor Flooding (18 feet): Low-lying areas near the river start taking water
  • Moderate Flooding (21 feet): Broader impacts to roads and nearby properties
  • Major Flooding (23 feet): Serious, widespread flooding


Bogue Lusa Creek behaves differently. It reacts quickly to intense local rainfall, so flooding can show up in a matter of hours rather than days. A neighborhood that never sees river water can still get creek overflow or drainage backup after several inches of rain in one afternoon. That's why flood zone maps tell only part of the story.

The Impact of Mill-District Low Ground

Bogalusa grew up around its paper mill, and many of the older homes built for mill workers sit on lower ground close to the creek and drainage channels. Plenty of these houses are on slab or low pier foundations built decades before modern elevation standards. When water has nowhere to go, these streets often feel it first.


For homeowners in these areas, the elevation of your lowest floor typically has a big effect on your premium. An elevation certificate may help, especially if your home sits higher than surrounding lots suggest. We also see buyers of older mill-area homes skip flood coverage because the lender didn't require it, which leaves a serious gap if the property sits just outside a mapped high-risk zone.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Coverage Area State Minimum Common Higher Option Stronger Option
Injury, one person $15,000 $50,000 $100,000
Injury, per accident $30,000 $100,000 $300,000
Property damage $25,000 $50,000 $100,000
Who it fits Legal compliance only Riders with modest assets Homeowners, families, higher earners

Here's a common scenario: you misjudge a curve and clip a late-model pickup, injuring the driver. A single ambulance ride, ER visit, and follow-up imaging can eat through $15,000 quickly. Anything above your limit can become your personal responsibility, which may put your savings, wages, or home at risk.

Minimum Coverage vs. Actual Protection Needs

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

Affordable Preferred-Zone Options for Bogalusa Homes

Not every Bogalusa home sits in a high-risk area. Plenty of properties on higher ground fall into moderate- or low-risk zones, often labeled Zone X on flood maps. These homes typically qualify for noticeably lower premiums than homes in Special Flood Hazard Areas.


The NFIP once sold a separate "Preferred Risk Policy" for these lower-risk homes. Under Risk Rating 2.0, that product name went away, and pricing now reflects each property's individual characteristics: distance to water, elevation, foundation type, and rebuilding cost. In practice, many lower-risk homeowners still pay modest premiums, and some saw rates fall under the new system.


Private flood carriers add another option. Data from 2026 shows that for about 65% of properties, private flood quotes come in at a median of 28% below NFIP rates. That won't apply to every house, but it's a strong reason to compare both before you sign anything.


A few ways lower-risk homeowners may keep costs reasonable:


  • Request a quote even if your lender doesn't require flood coverage
  • Ask about higher deductibles if you have emergency savings
  • Provide an elevation certificate if you have one
  • Compare NFIP and private quotes side by side


Lower risk is not no risk. Roughly a quarter of NFIP claims nationally have historically come from outside high-risk zones, and creek flooding in town doesn't respect map lines.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.

Feature Commercial Property Inland Marine (Tool Floater)
Where it applies Your fixed shop location Jobsites, truck, in transit
Typical items Stationary machines, inventory, building Portable saws, nailers, hand tools
Theft from vehicle Usually not covered Often covered, with conditions
Fire or storm at shop Typically covered May be covered if tools are there
Who needs it Carpenters with a shop Nearly every working carpenter

How Deductible Types Compare

Comparison of NFIP vs. Excess Flood Coverage

Feature NFIP Policy Excess Flood Policy
Building limit Up to $250,000 Typically adds coverage above $250,000
Who issues it Federal program, sold through agents Private carriers
Waiting period Generally 30 days May be shorter, varies by carrier
Additional living expenses Not included May be included, depending on policy
Basement coverage Very limited May be broader on some policies
CRS premium credit Applies in Mandeville Typically does not apply
Best fit for Base layer for most homes Higher-value or lakefront homes

Disaster Aid Versus a Policy

This is the conversation we have more than any other with homeowners who are on the fence. Many people assume the federal government will step in after a flood. Sometimes it does, but the help usually looks very different from what they expect.


First, federal disaster aid depends on a declaration. Disaster assistance becomes available only when the President issues a Major Disaster Declaration. A localized creek flood that swamps a few Bogalusa neighborhoods may never reach that threshold. A flood policy, on the other hand, pays for covered losses whether or not anyone in Washington declares a disaster.


Second, a large share of federal help comes as a loan. SBA Disaster Loans must be repaid with interest, so you could end up with a second mortgage-style payment on top of the one you already have.


Third, grants are limited. For disasters declared on or after October 1, 2025, the maximum FEMA Individual Assistance grant is capped at $44,800 for Housing Assistance, with a separate $44,800 cap for Other Needs Assistance. Most households receive far less than the maximum. Compare that to Louisiana's average flood claim of around $82,614, and the gap gets obvious fast.

General liability covers physical harm: fires, shocks, and property damage from your work. Professional liability, sometimes called errors and omissions, may cover financial loss from design mistakes or bad advice, such as an undersized service you specified on a load calculation. Electricians who do design-build work, panel sizing for solar, or consulting often need both, because a general liability policy typically will not respond to a pure financial loss.

The most common mistake is buying limits sized for the center you opened, not the center you run now. Enrollment grows, a second van shows up, an after-school program starts, and the policy stays the same. A yearly review against your actual operations catches that drift before a claim exposes it.

General Liability vs. Workers Compensation

Comparing NFIP and Private Flood Insurance Coverage

Both NFIP and private policies cover direct physical flood damage, but they differ in limits, extras, and flexibility. The NFIP sets fixed federal caps on building and contents coverage for homes. Private carriers write their own terms, which may allow higher limits for larger or more expensive homes.

Feature NFIP Typical Private Market
Building Coverage Fixed federal maximum for homes May offer higher limits, set by carrier
Contents Coverage Fixed federal maximum, sold separately Often higher; may include replacement cost
Waiting Period Standard 30 days Often shorter; varies by carrier
Additional Living Expenses Not included May be included
Basement Coverage Limited Varies; sometimes broader
Rate Stability Federally backed, gradual increases Carrier can adjust or exit the market

The NFIP's biggest strength is stability. It isn't going to pull out of Louisiana, and its policies typically transfer to a new buyer when you sell, which can help with resale. Private policies may offer more coverage for the money, especially for homes that would exceed federal limits or families who would need hotel costs paid during repairs.


One common mistake: buying building coverage and skipping contents. If your furniture, appliances, and clothes are ruined, building coverage alone won't replace them. Ask for both.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.

Feature Commercial Property Inland Marine (Tool Floater)
Where it applies Your fixed shop location Jobsites, truck, in transit
Typical items Stationary machines, inventory, building Portable saws, nailers, hand tools
Theft from vehicle Usually not covered Often covered, with conditions
Fire or storm at shop Typically covered May be covered if tools are there
Who needs it Carpenters with a shop Nearly every working carpenter

Frequently Asked Questions About Bogalusa Flood Insurance

Does my homeowners insurance cover flooding in Bogalusa? Typically no. Standard homeowners policies exclude rising water, so you need a separate flood policy.


Do I need flood insurance if I'm not in a high-risk zone? Your lender may not require it, but creek overflow and heavy rain can flood homes outside mapped zones. Lower-risk homes often qualify for lower premiums, so it's usually worth a quote.


How long before my flood policy kicks in? NFIP policies generally carry a 30-day waiting period. Some private policies may have a shorter wait, depending on the carrier.


Is private flood insurance cheaper than the NFIP? It can be. In 2026 data, about 65% of properties received private quotes that came in at a median of 28% below NFIP rates, but results vary by home.


Can't I just rely on FEMA after a flood? Federal aid requires a presidential disaster declaration, and much of it comes as loans you repay with interest. Grants are capped and often fall well short of actual damage.


Does renters coverage include flooding? No. Renters can buy contents-only flood coverage to protect their belongings.

General liability covers physical harm: fires, shocks, and property damage from your work. Professional liability, sometimes called errors and omissions, may cover financial loss from design mistakes or bad advice, such as an undersized service you specified on a load calculation. Electricians who do design-build work, panel sizing for solar, or consulting often need both, because a general liability policy typically will not respond to a pure financial loss.

The most common mistake is buying limits sized for the center you opened, not the center you run now. Enrollment grows, a second van shows up, an after-school program starts, and the policy stays the same. A yearly review against your actual operations catches that drift before a claim exposes it.

General Liability vs. Workers Compensation

Your Next Steps for Local Protection

Flood risk in Bogalusa comes from two directions: the Pearl River's slow, predictable rises and Bogue Lusa Creek's fast reaction to heavy rain. Older homes on mill-district low ground often carry the most exposure, while homes on higher ground may find surprisingly reasonable rates. Either way, a policy pays when federal aid doesn't show up, and it won't hand you a loan to repay.


Here's a simple plan:


  1. Check your flood zone and find your elevation certificate if you have one
  2. Get quotes from both the NFIP and private carriers
  3. Buy building and contents coverage
  4. Do it now, well ahead of the 30-day waiting period


Aubert Insurance Agency has been helping Louisiana families protect their homes since 1910. From our offices in Covington and Slidell, we compare options from multiple carriers and walk you through what your policy covers and excludes. Start a Quote today, and let us find the right flood protection for your Bogalusa home before the next high-water forecast.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
