













Covington & Slidell Independent Insurance Agents
Insuring a home in Madisonville means planning for three things: riverfront flood and wind exposure along the Tchefuncte, the rating advantages that newer construction in Bedico Creek and Guste Island may earn, and the details standard policies often miss, like docks, boathouses, and percentage-based wind deductibles that can shift thousands of dollars onto you.
Madisonville is a small town with an outsized amount of water. A lot of homeowners here bought for the river views, the boat launch down the street, or the quiet streets of a newer subdivision off Highway 1085. Then the renewal arrives, and the questions start: why is the wind deductible a percentage, why does the dock appear nowhere on the declarations page, and why does a neighbor's brand-new house cost less to insure than an older raised cottage closer to the water?
The market itself has calmed down somewhat. The average Louisiana homeowners rate change fell to just 0.1% as of August 2026, down from a 14% average increase in 2023. More options are arriving, too, with three new carriers entering Louisiana in the first four months of 2026: Progressive Paloverde, Continental Indemnity, and GuardianPointe. Stable rates are not the same as low rates, though, and the structure of your policy matters more than ever.
Insuring Raised Homes and Riverfront Property Along the Tchefuncte
The first thing to understand about riverfront living is that your homeowners policy and your flood policy are two separate contracts. Standard homeowners forms typically exclude rising water, whether it comes from the Tchefuncte, Lake Pontchartrain storm surge, or heavy rain backing up through low streets. Roughly 85.8% of properties in Madisonville carry some level of flood risk, so this is not a box to skip because you're "not in the bad zone."
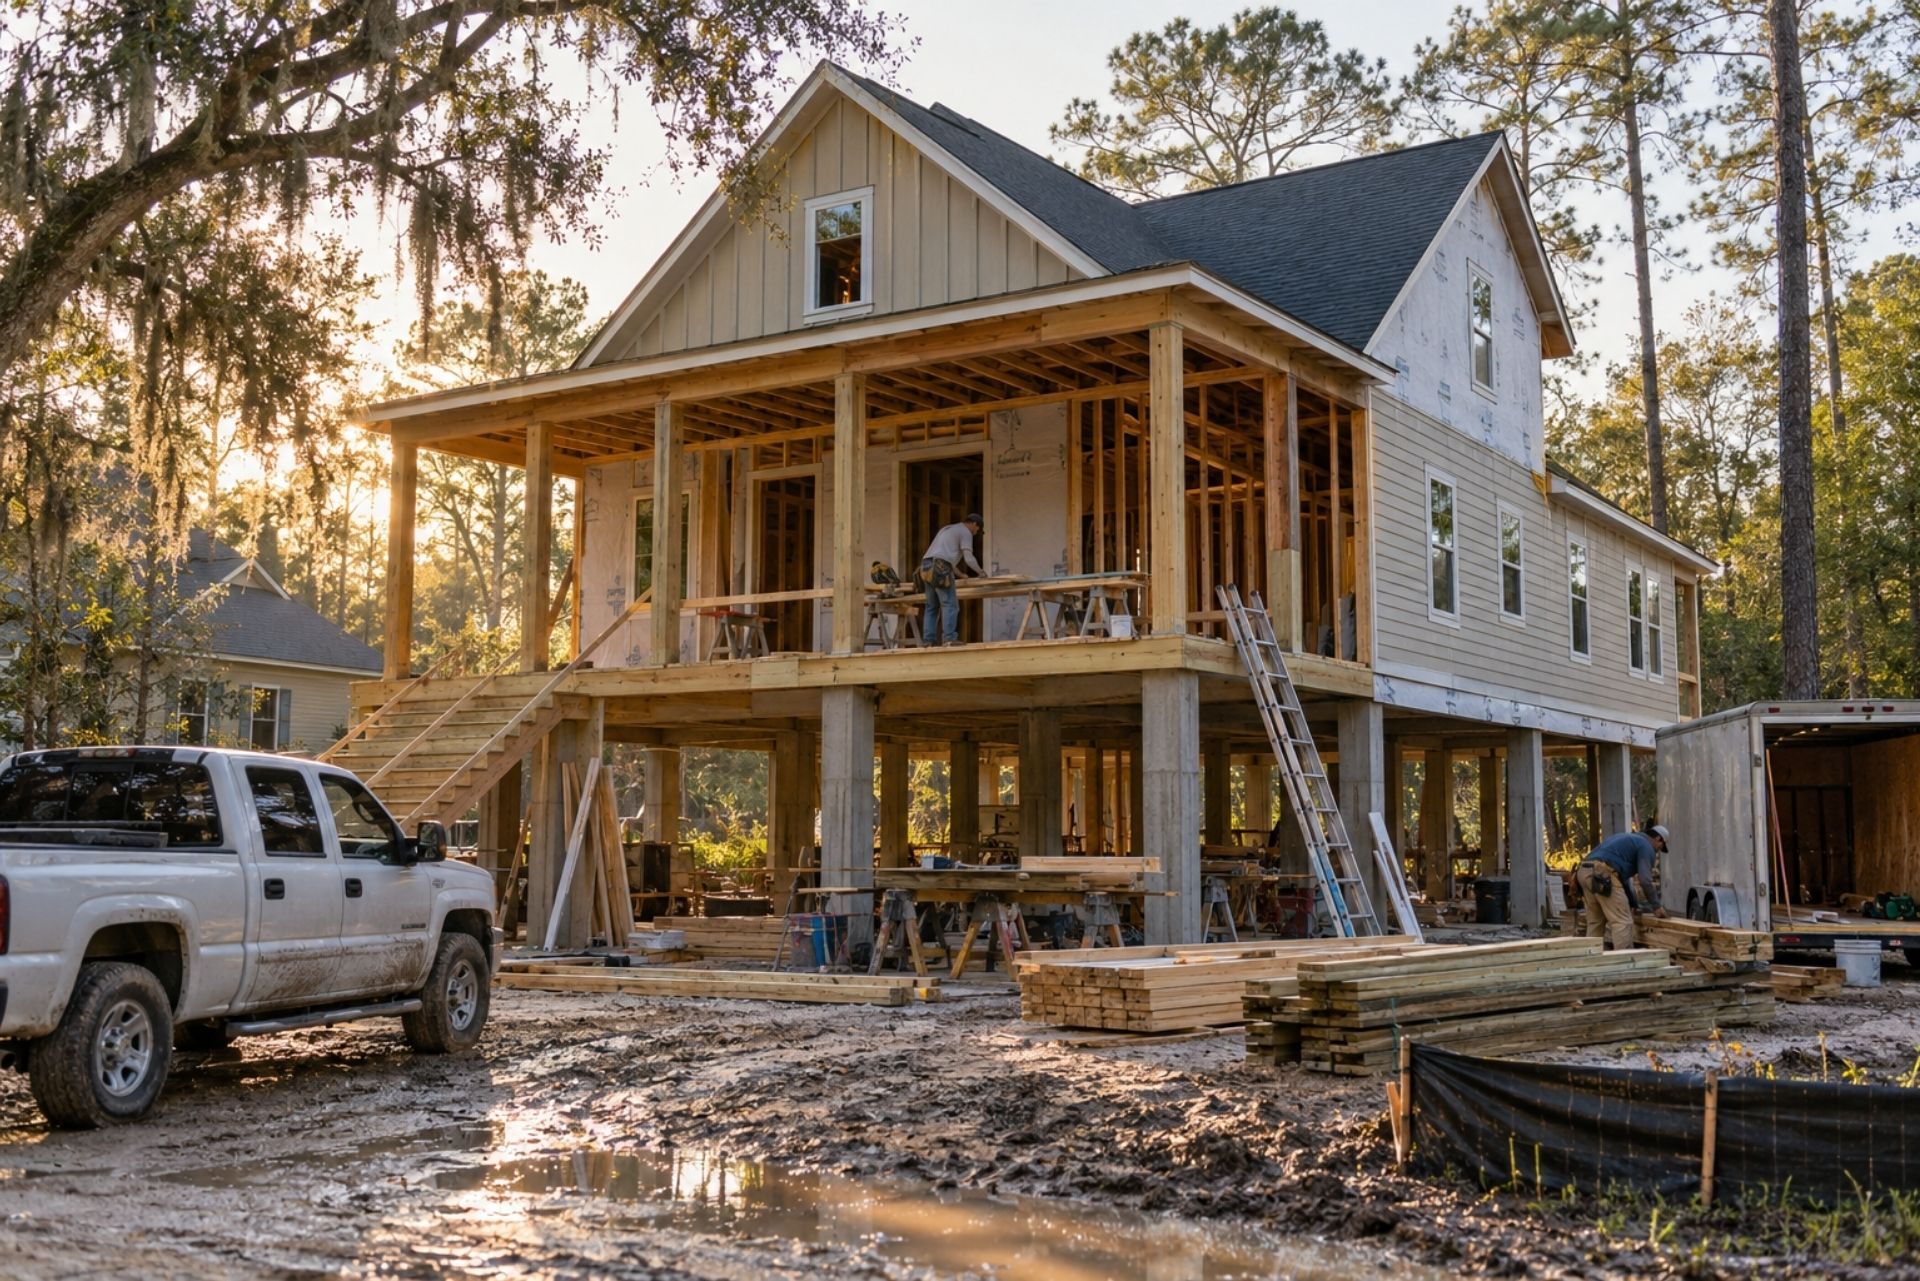
Elevation helps on both sides of the ledger. A home raised on piers or pilings sits farther above potential water, which may lower flood premiums depending on your elevation certificate. On the homeowners side, carriers typically look at the age of the roof, how the structure is anchored, and the condition of the space underneath.
That space underneath is where we see a lot of surprises. Owners finish part of the ground level, store a golf cart and freezers there, or add an enclosed workshop. Flood policies typically limit coverage for contents and finishes below the lowest elevated floor, so a renovated downstairs den may be largely uninsured against water. Tell your agent exactly how that level is used before a claim forces the conversation.
One newer option to know about: under Act 480, Louisiana homeowners can choose stated value policies that insure a home for a declared amount, such as the mortgage balance, rather than full replacement cost. That can make premiums more manageable on an older riverfront home, but it also means you may not be able to rebuild the same house after a total loss. Weigh it carefully.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Many St. Tammany families end up with both: standalone coverage for the land, plus an umbrella over the home and vehicles.
Comparison: Standalone Liability vs. Umbrella Coverage
Understanding the Named Storm Deductible
A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.
There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.
| Factor | Standalone Liability | Umbrella Policy |
|---|---|---|
| Underlying policy required | No | Yes, home and auto typically |
| When it pays | First dollar of a covered claim | After underlying limits run out |
| Typical use | Vacant land, hunting tracts, specific risks | Broad extra protection across policies |
| Cost structure | Priced by acreage, use, and limit | Priced by number of homes, cars, drivers |
| Scope | Narrow, tied to named property or risk | Wide, follows underlying coverage |
| Common limits | $300,000 to $1 million | $1 million and up |
People use the two terms as if they mean the same thing. They do not.
A true umbrella policy may provide broader coverage than the policies below it. In some cases it can "drop down" to cover a claim the primary policy excludes, usually subject to a self-insured retention, often $10,000 or $25,000. An excess policy is typically "follow form," which means it copies the terms and exclusions of the underlying policy and simply adds more limit.
Here is why that matters. If your general liability policy excludes a certain type of claim, a follow-form excess policy will generally exclude it as well. Higher limits do not repair a weak foundation. We go through the endorsements on each layer with clients before binding, because the wording on page 14 of the policy is what decides whether a claim gets paid.
New Construction Benefits in Bedico Creek and Guste Island
If you're building or buying new in Bedico Creek or Guste Island, you may have an edge when quoting coverage. Carriers tend to price newer homes favorably because modern building codes require stronger roof attachment, better window ratings, and updated electrical and plumbing systems. A 2024 or 2025 build simply has fewer of the aging-system problems that drive water damage and fire claims in older housing stock.
Many insurers apply credits for homes built to current wind codes, and some use the year built as a major factor in setting base rates. Compared with a 1970s ranch in old town Madisonville, a new home in one of these master-planned communities may start from a lower base before any other credits are applied.
Roof construction is the biggest lever. Homes built with a Fortified Roof are increasingly common in Louisiana and can qualify for meaningful insurance savings. If your builder offered the upgrade, get the Fortified certificate in hand and send it to your agent; without the paperwork, the credit typically isn't applied. Owners who upgraded in 2025 should also know that the application window for the state's 100% income tax credit closed on June 30, 2026.
A practical tip for new builds: confirm your dwelling limit reflects actual construction cost, not the sales price, which includes land. Overinsuring the lot wastes premium, and underinsuring a custom finish package leaves gaps.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
How Sublimits Affect Overtime and Minimum Wage Disputes
Auto Liability vs. General Liability for Mobile Equipment
Peak Season Endorsements
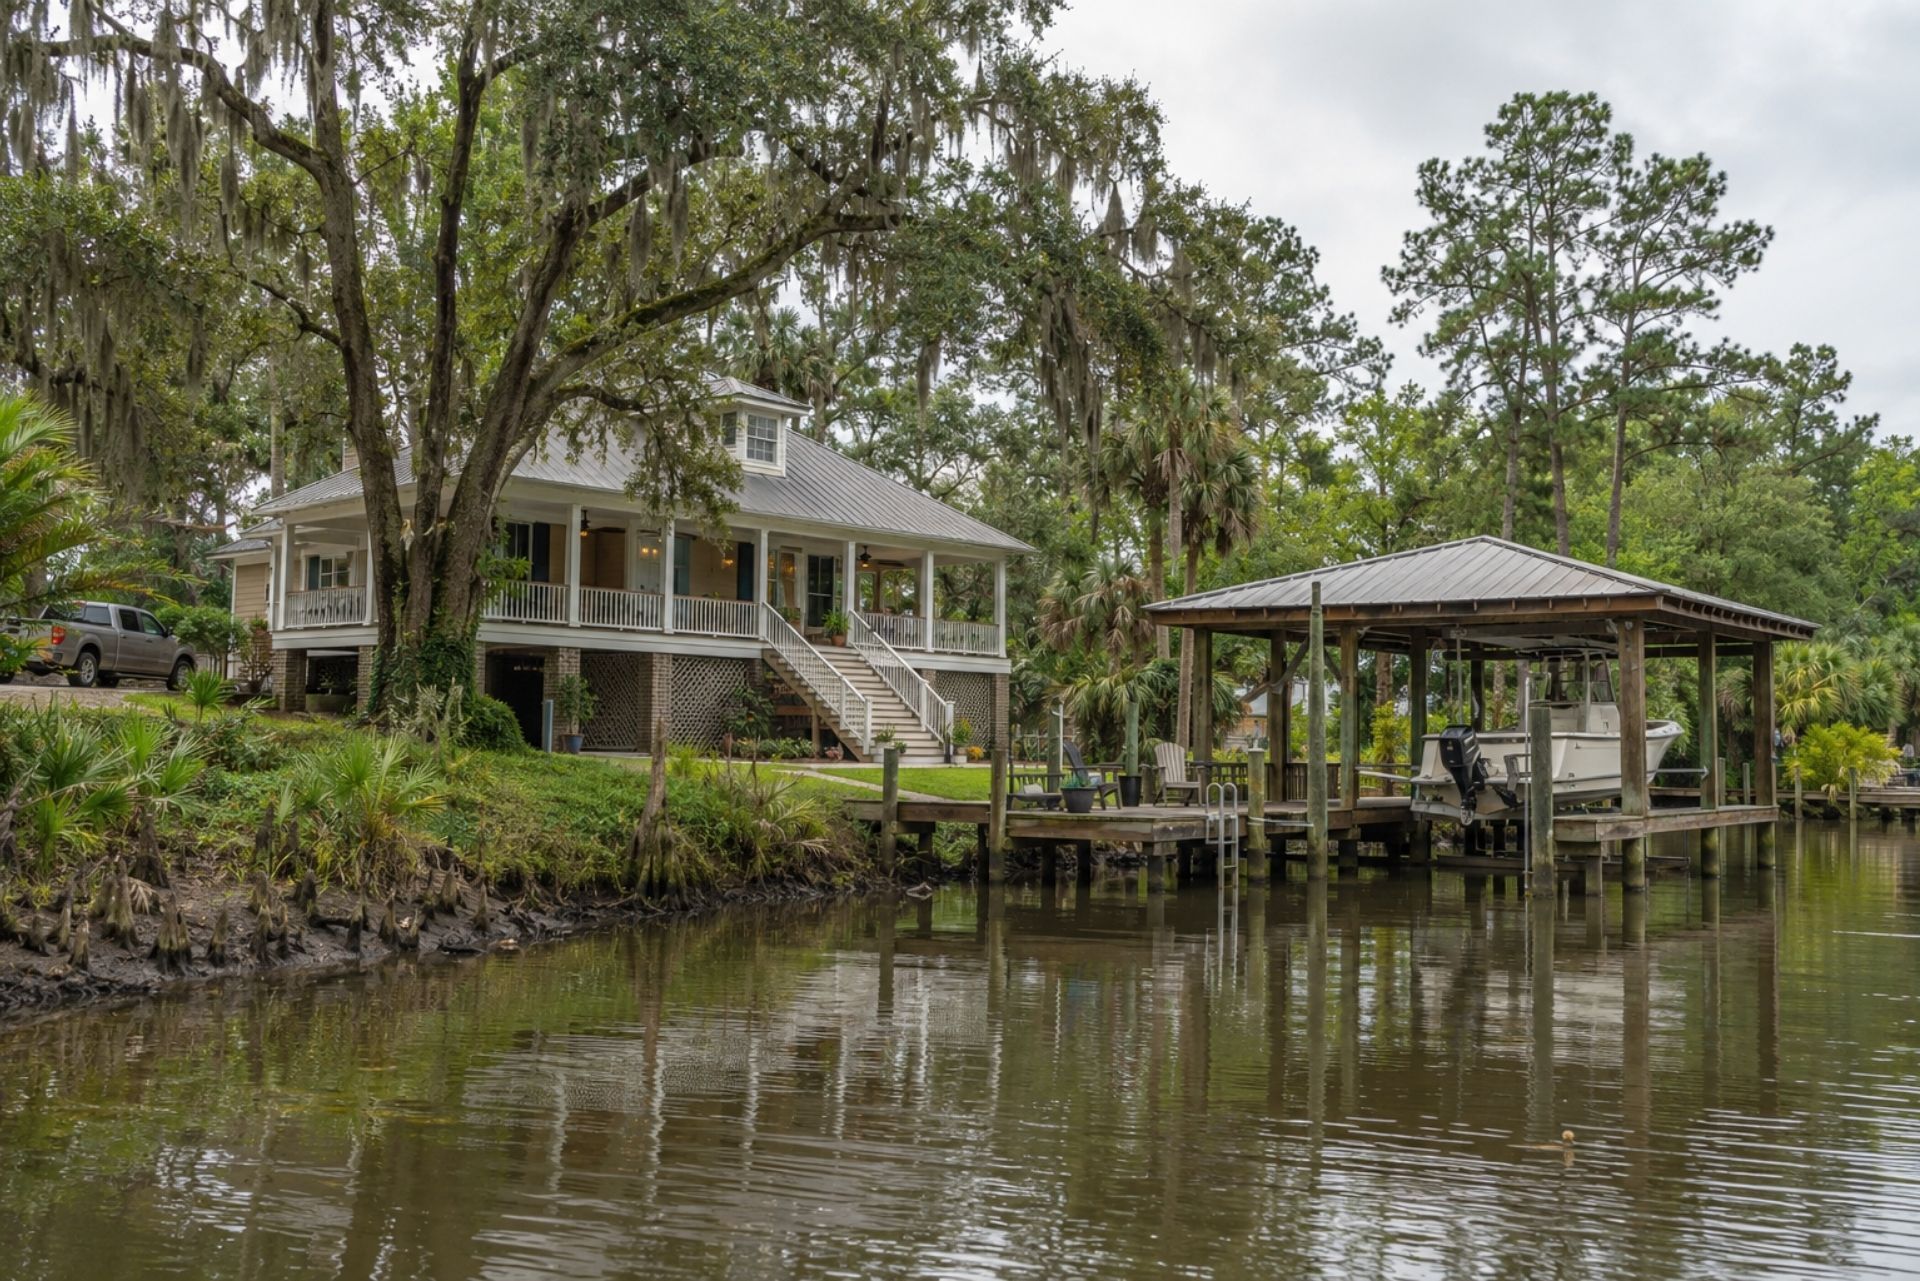
Protecting Your Waterfront Assets: Dock and Boathouse Coverage
Here's the gap that catches riverfront owners most often. Standard homeowners forms typically restrict coverage for structures built over or in water, and windstorm damage to docks, piers, and wharves is frequently limited or excluded outright. A boathouse may fall under "other structures" coverage, but that category is usually capped as a percentage of your dwelling limit and may still carry the same over-water restrictions.
Picture a common claim: a tropical storm pushes debris down the Tchefuncte and tears apart a 60-foot dock and boat lift. The owner assumes the homeowners policy will respond. Instead, the adjuster points to the exclusion for wind damage to wharves, and the rebuild comes entirely out of pocket.
Ways to close the gap may include:
- Dock or pier endorsement: Some carriers offer an add-on that restores coverage for over-water structures, often with its own limit and deductible.
- Separate policy: For larger docks or boathouses, a standalone policy may provide broader protection.
- Boat lift and equipment: Lifts, electrical pedestals, and lighting may need to be scheduled specifically.
- Watercraft liability: Your boat itself typically needs its own policy, especially for liability when guests are aboard.
Ask for the dock coverage in writing and read the exclusions. If the answer is "it should be covered," keep asking.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
| Scenario | Dwelling limit | All-other-perils deductible | Named-storm deductible |
|---|---|---|---|
| Newer build, inland St. Tammany | $350,000 | $1,000 | 2% |
| Newer build, higher wind zone | $350,000 | $1,000 | 5% |
| Older home, updated roof | $275,000 | $2,500 | 2% |
| Older home, original roof | $275,000 | $2,500 | 5% |
| Fortified roof designation | $400,000 | $1,000 | 2% |
| Rebuilt after a prior claim | $400,000 | $2,500 | 5% |
| Bundled with auto | $350,000 | $1,000 | 2% |
Exact terms vary by carrier, so treat this as a starting point for comparing quotes.
Understanding Wind and Named Storm Deductibles
Most St. Tammany Parish policies carry two different deductibles, and many homeowners only know about one. The All Other Peril (AOP) deductible is a flat dollar amount, often $1,000 or $2,500, and applies to things like fire, theft, or a burst pipe.
The second is a wind/hail or named storm deductible, which is typically a percentage of your dwelling coverage (Coverage A), not of the damage. A named storm deductible usually kicks in only when the National Hurricane Center has named the system, while a wind/hail deductible may apply to any wind event, including a spring thunderstorm. Your declarations page should show which type you have.
The percentage feels small until you do the math. On a home insured for $400,000, a 2% deductible is $8,000 before the carrier pays a dollar. Choosing a higher percentage can lower your premium, but only if you could realistically cover that amount after a storm.
Deductible Comparison: Flat vs. Percentage
Assumes a dwelling limit (Coverage A) of $400,000.
| Deductible Type | Applies To | Your Out-of-Pocket |
|---|---|---|
| $1,000 AOP | Fire, theft, water leak | $1,000 |
| $2,500 AOP | Fire, theft, water leak | $2,500 |
| 2% Wind/Named Storm | Hurricane or wind damage | $8,000 |
| 5% Wind/Named Storm | Hurricane or wind damage | $20,000 |
The gap between $2,500 and $20,000 is where people get hurt. If storm damage totals $15,000 and you carry a 5% deductible, the policy may pay nothing at all. Set aside savings that match your wind deductible, or consider a lower percentage if the premium difference is modest.
Working capital matters more than almost anything else. Underwriters look at current assets minus current liabilities, because cash and receivables are what keep a job moving when a payment runs late. Equity in equipment or real estate helps, but it doesn't pay a subcontractor on Friday.
Expect requests for CPA-prepared financial statements once you seek larger limits. Personal credit counts heavily for smaller firms, since owners typically sign personal indemnity. Clean books, a solid bank line of credit, and low debt can raise your capacity faster than any sales pitch.
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| Coverage trigger | Typically occurrence-based: injury or damage during the policy period | Typically claims-made: claim first made and reported during the policy period |
| What it addresses | Bodily injury and physical property damage from operations | Financial loss from errors, omissions or negligent professional services |
| Example claim | A visitor trips over equipment at your site visit | Undersized HVAC design forces a costly retrofit |
| Typical exclusions | Professional services, design errors | Bodily injury or property damage unrelated to services (varies), contractual liability, fraud, cost estimate guarantees |
| Defense costs | Usually outside limits | Often inside limits |
Common Questions About Madisonville Home Insurance
Does my home insurance cover flood damage from the river? Typically no. Standard homeowners policies exclude flood, so you'll need a separate flood policy through the NFIP or a private flood carrier.
How does a raised foundation affect my premium? Elevation may lower flood premiums, especially with a favorable elevation certificate. On the homeowners side, carriers typically weigh roof condition, age, and construction more heavily.
Is my dock covered if a hurricane destroys it? Often not under a standard form, since wind damage to docks and piers is commonly limited or excluded. An endorsement or separate policy may restore that protection.
Will a new home in Bedico Creek or Guste Island cost less to insure? It may, because newer construction often qualifies for building code credits and lower base rates. A Fortified Roof certificate can add further savings.
What's the difference between my hurricane deductible and my regular deductible? Your regular AOP deductible is a flat dollar amount, while a hurricane or named storm deductible is usually a percentage of your dwelling limit. That percentage can mean several thousand dollars out of pocket.
What is a stated value policy? Under Act 480, you can insure your home for a declared amount, like your mortgage balance, instead of full replacement cost. It may lower premiums but could leave you short if you need to rebuild.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
| Feature | General Liability | Business Personal Property |
|---|---|---|
| Protects against | Claims from others | Damage to your own stuff |
| Slip and fall injuries | Yes, typically | No |
| Inventory damaged by fire | No | Yes, typically |
| Legal defense costs | Usually included | Not applicable |
| Seasonal stock increases | Not applicable | May need peak season endorsement |
| Employee theft | No | Usually excluded |
| Named storm deductible | Not applicable | Often applies |
Making the Right Choice for Your Madisonville Property
A Madisonville policy that fits well accounts for the river, the age and elevation of the house, anything you've built over the water, and a wind deductible you can actually afford. Get those four pieces right and most of the nasty claim-day surprises disappear. Get one wrong, and a single storm can expose the gap.
That's where an independent agency earns its keep. Aubert Insurance Agency has insured homes and families across St. Tammany Parish from offices in Covington and Slidell since 1910, comparing coverage from multiple carriers instead of steering you toward one. With new companies entering Louisiana this year, shopping your coverage now may turn up options that didn't exist at your last renewal.
We'll also walk you through what your policy says, including the exclusions for docks, flood, and wind that most people never read until they have to. Ready to see how your riverfront home, new build, or boathouse stacks up? Start a Quote with Kyle Beerbohm today and get coverage built around how you actually live on the Tchefuncte.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













