













Covington & Slidell Independent Insurance Agents
Louisiana personal liability insurance provides financial protection if someone sues you over bodily injury or property damage that happens on your premises or results from your actions. It typically pays for legal defense, settlements, and judgments up to your policy limit. For owners of vacant acreage, hunting leases, or homes with dogs, it closes gaps that other policies may leave open.
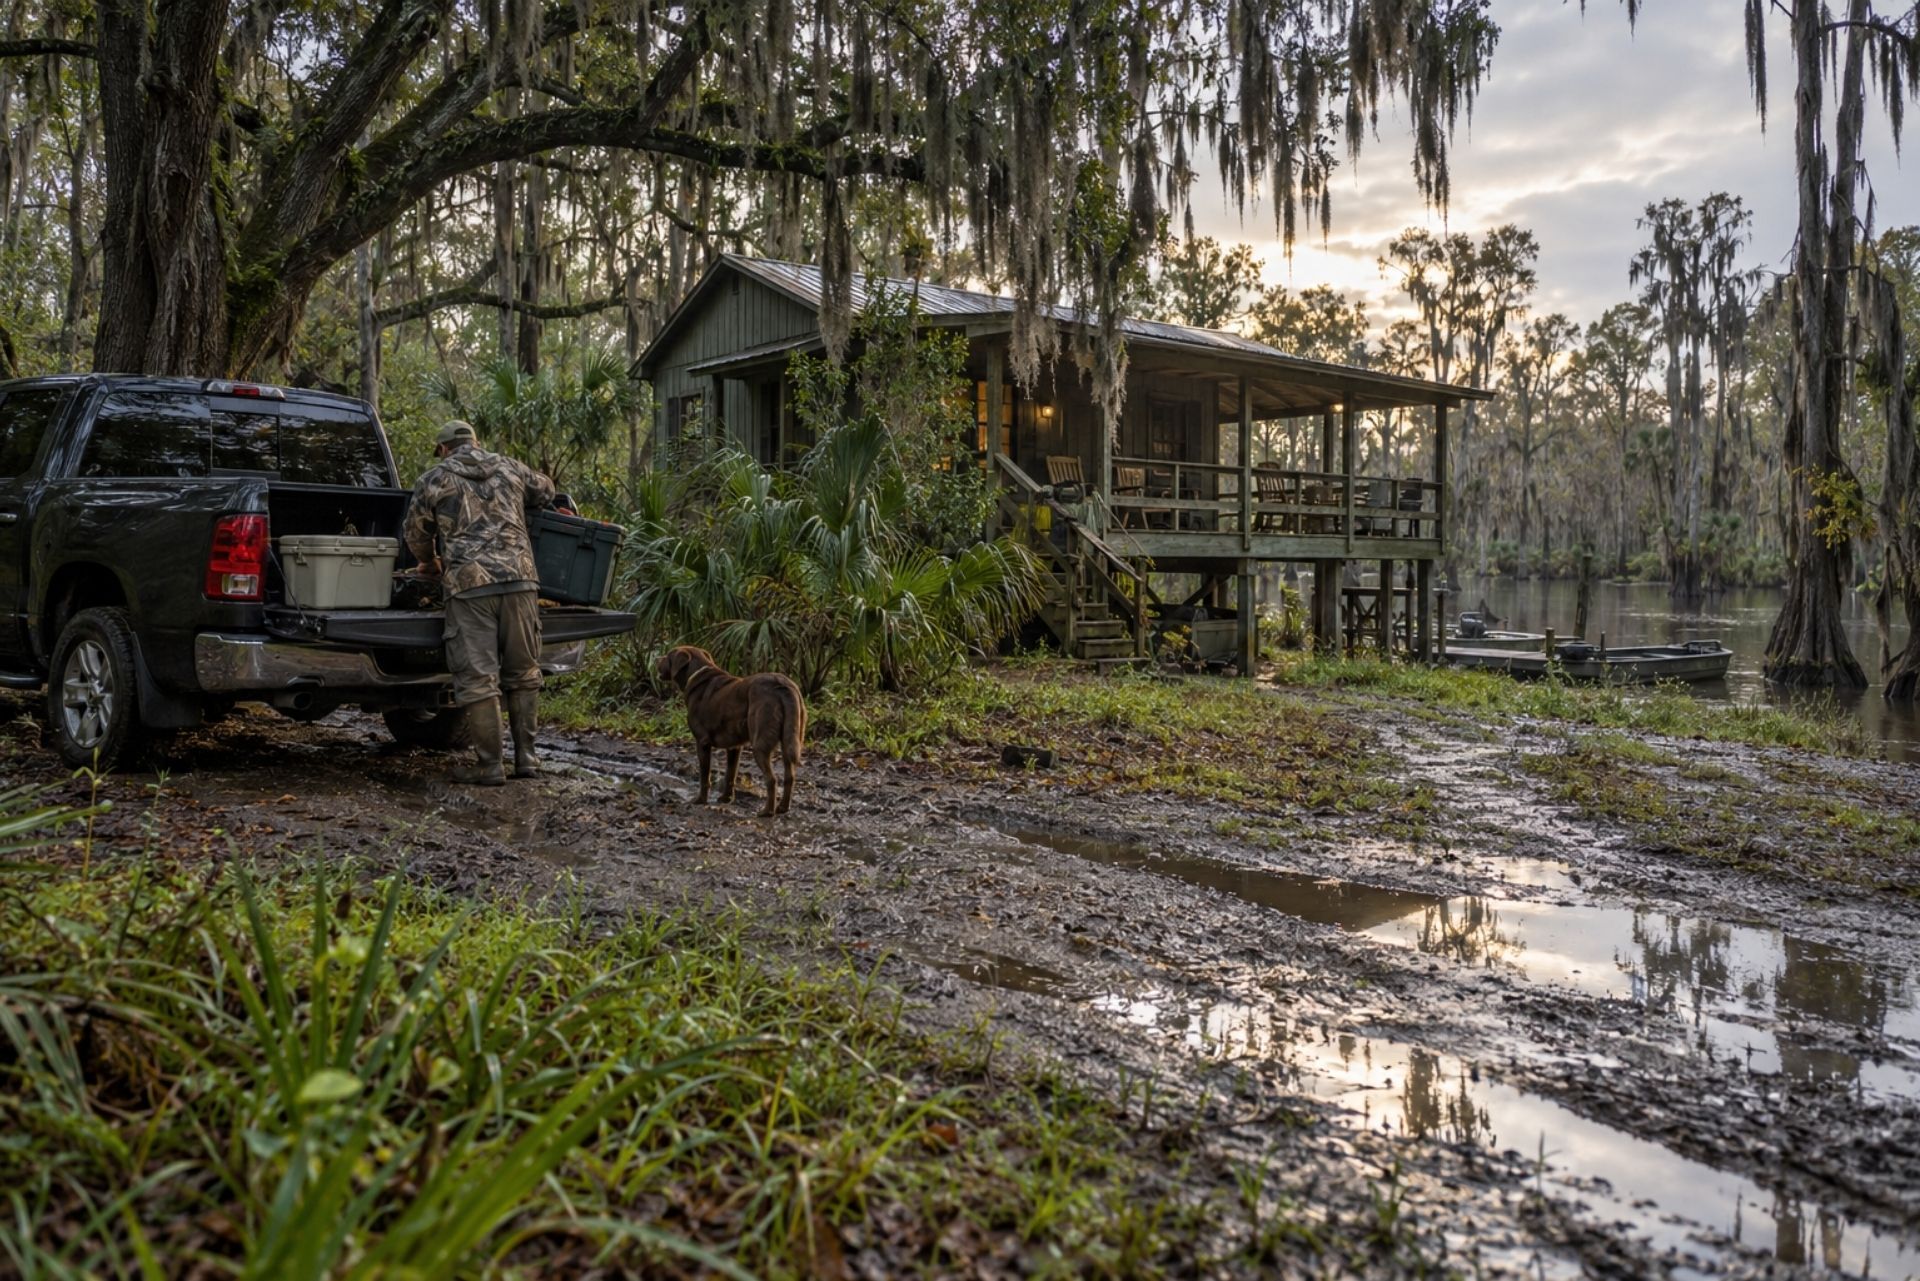
Picture a 40-acre tract outside Folsom that you visit four times a year during deer season. A neighbor's teenager cuts through on an ATV, hits a washout, and breaks a collarbone. Your homeowners policy covers your house in Covington, but does it reach that land? Many St. Tammany owners only find out after a claim lands on their desk.
Protecting Louisiana Land and Lifestyles with Personal Liability Insurance
Aubert Insurance Agency has insured families in Covington and Slidell since 1910. Over that time, one pattern keeps showing up: people insure what they can see, like the house, the truck, and the boat. They rarely think about the liability that follows them onto every property they own and through every visitor who walks onto it.
Personal liability coverage is about other people's injuries and other people's property. If a guest trips on your porch steps, a hunter falls from a stand on your lease, or your dog nips a delivery driver, the claim is about what you owe them. Your own losses fall under different coverage.
Louisiana adds its own wrinkles. State law treats recreational land, dog bites, and medical damages in specific ways, and those rules shape how claims play out here. Knowing them helps you decide whether your current setup holds up or whether you need a separate policy for land you own away from home.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Many St. Tammany families end up with both: standalone coverage for the land, plus an umbrella over the home and vehicles.
Comparison: Standalone Liability vs. Umbrella Coverage
Understanding the Named Storm Deductible
A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.
There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.
| Factor | Standalone Liability | Umbrella Policy |
|---|---|---|
| Underlying policy required | No | Yes, home and auto typically |
| When it pays | First dollar of a covered claim | After underlying limits run out |
| Typical use | Vacant land, hunting tracts, specific risks | Broad extra protection across policies |
| Cost structure | Priced by acreage, use, and limit | Priced by number of homes, cars, drivers |
| Scope | Narrow, tied to named property or risk | Wide, follows underlying coverage |
| Common limits | $300,000 to $1 million | $1 million and up |
Standalone Liability for Vacant Land and Hunting Property
The most common gap appears with land that has no house on it. A homeowners policy may extend liability to some vacant lots you own, but carriers often limit acreage or exclude land used for hunting, timber, or leasing. If you rent hunting rights to a club, that commercial use can void coverage you assumed you had.
Louisiana does offer some protection. State law gives owners of undeveloped recreational land a shield, meaning they generally owe no duty to keep premises safe unless a failure to warn is willful or malicious. Courts also continue to dismiss premises claims where the hazard was open and obvious to a reasonable person.
The catch: a strong defense still costs money. Even a claim you win requires attorneys, depositions, and months of back-and-forth. Market data from 2014 to 2018 put the average vacant land liability claim near $26,870, and that figure doesn't include legal defense costs.
A standalone vacant land or hunting property policy typically covers:
- Defense costs for claims tied to the property, often in addition to the limit
- Injuries to visitors such as hunters, trespassers, or invited guests
- Property damage to neighboring land, like a fire that spreads during burning
- Leased hunting use, if disclosed and accepted by the carrier
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
How It Differs From an Umbrella Policy
People often ask whether an umbrella will handle the land. Sometimes it can, but an umbrella sits on top of other policies. You must carry underlying homeowners and auto insurance, usually at limits the carrier specifies, before an umbrella will be written. It then adds an extra layer of protection once those underlying limits are exhausted.
Standalone personal liability works differently. You can buy it independently for a specific risk, like 80 acres of pine timber in Washington Parish or a camp lot with no structure. It responds from the first dollar of a covered claim rather than waiting for another policy to pay out first.
One common mistake: buying an umbrella and assuming it covers everything. If the underlying policy excludes your hunting land, the umbrella may exclude it too. Some umbrellas do provide drop-down coverage for certain gaps, but that feature varies by carrier and should be confirmed in writing.
Comparison: Standalone Liability vs. Umbrella Coverage
| Factor | Standalone Liability | Umbrella Policy |
|---|---|---|
| Underlying policy required | No | Yes, home and auto typically |
| When it pays | First dollar of a covered claim | After underlying limits run out |
| Typical use | Vacant land, hunting tracts, specific risks | Broad extra protection across policies |
| Cost structure | Priced by acreage, use, and limit | Priced by number of homes, cars, drivers |
| Scope | Narrow, tied to named property or risk | Wide, follows underlying coverage |
| Common limits | $300,000 to $1 million | $1 million and up |
Many St. Tammany families end up with both: standalone coverage for the land, plus an umbrella over the home and vehicles.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Managing Risks for Dog Bites and Premises Claims
Dog bites are among the most frequent liability claims we see on homeowners policies. Louisiana remains a strict liability state for dog owners, meaning the owner is liable if they could have prevented the injury and the victim did not provoke the dog. "He's never bitten anyone before" isn't much of a defense here.
Coverage gaps hide in the fine print. Some carriers exclude certain breeds, cap dog bite payouts at a lower sublimit, or exclude a specific dog after a prior incident. If your policy carries an animal liability exclusion, a standalone canine liability policy may fill that hole.
Premises claims at home follow a different standard than recreational land. A guest who slips on a wet pool deck in Slidell or falls through a rotten dock board on the Tchefuncte can claim you knew or should have known about the hazard. Some practical steps help:
- Walk your property each spring and fix loose steps, railings, and dock boards.
- Keep dogs secured when contractors, delivery drivers, or children visit.
- Post clear signs at gates and around ponds on rural land.
- Tell your agent about pools, trampolines, and every dog in the household.
That last one matters most. Undisclosed risks are a frequent reason claims get disputed.
Liability Limits Worth Carrying in Louisiana
Many homeowners policies start at $100,000 in liability, which rarely holds up after a serious injury. We typically treat $300,000 as a minimum starting point. For most families with home equity, savings, or land holdings, $500,000 or more is often the more realistic number.
The math adds up fast. A broken leg from a fall on hunting land can mean surgery, physical therapy, and lost wages. Then add defense attorneys, expert witnesses, and possibly a trial in front of a jury. Defense alone can consume a meaningful portion of a lower limit, depending on how your policy treats legal costs.
Recent law changes help a bit. Louisiana now restricts recoverable medical damages to amounts actually paid by insurers or the plaintiff rather than higher billed amounts. That may reduce some settlement values, but it doesn't touch pain and suffering, lost income, or defense costs.
A simple test: add up your home equity, land value, retirement accounts outside protected plans, and savings. If that total exceeds your liability limit, you have exposure. Raising a limit from $300,000 to $500,000 often costs less than people expect, which makes the decision easier.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Common Questions About Personal Liability Coverage
Does my homeowners insurance cover land I own somewhere else? It may cover a small vacant lot, but many policies limit acreage or exclude hunting and leased land. Check your declarations page or ask your agent to confirm in writing.
Do I need liability insurance if I let friends hunt my land for free? Louisiana's recreational use law offers protection, but it doesn't stop someone from filing a suit. A policy pays for your defense even when the claim fails.
What happens if my dog bites someone and my policy excludes the breed? You could be personally responsible for the full claim. A standalone canine liability policy may cover the gap, depending on the carrier and the dog's history.
Is an umbrella policy the same as personal liability insurance? Not quite. An umbrella adds extra limits on top of home and auto policies, while standalone liability can be bought on its own for a specific property or risk.
How much does standalone liability cost for vacant land? Pricing typically depends on acreage, how the land is used, and the limit you choose. Hunting leases and ponds usually affect the rate more than plain timberland.
Does leasing my land to a hunting club change my coverage? Often, yes. Leasing is usually considered a commercial use, so you'll want coverage that specifically names and accepts the lease arrangement.
Making the Right Choice for Your Property
The right coverage depends on how you actually use your land and what's at stake if something goes wrong. A family with a single home and a well-behaved lab has different needs than someone with a hunting camp in Tangipahoa Parish, a leased tract, and a boat dock. Louisiana's recreational land protections and strict dog bite rule both shape that picture, but neither replaces having a policy that pays for your defense.
Start by listing every property you own, every animal in the household, and every way people come onto your land. Then compare that list to your current policies and look for the gaps. As an independent agency, Aubert Insurance Agency can compare options from multiple carriers and walk you through what each policy covers and excludes, so nothing surprises you after a claim.
Ready to see where you stand? Start a Quote today, and we'll help you match your limits to the land and life you're protecting.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













