Louisiana Framing Contractor Insurance

Most policies split protection into three core pieces:


  • Building: The structure itself, plus permanently attached fixtures. This may include signage, parking lot lighting, and fencing if they are listed or covered by endorsement.
  • Contents (Business Personal Property): Equipment, inventory, computers, and furniture. Contents matter most for businesses whose expensive equipment sits close to the ground. A car wash is a good example: its high-value machinery is often at ground level, which makes it more exposed to wind-driven damage and flooding.
  • Business Income: Replaces lost profits and pays continuing expenses like payroll and rent while you are shut down for repairs.


One common mistake is setting the business income limit too low. Rebuilding after a major Louisiana hurricane can take far longer than owners expect, because contractors and materials are stretched thin across the region.

Covington & Slidell Independent Insurance Agents

Buildings, Contents, and Business Income
A Louisiana framing contractor typically needs general liability, workers compensation, commercial auto, and builder's risk coverage that includes wind. Framers here face elevated fall exposure on raised and two-story homes, some of the highest comp class rates in construction, audit charges for uninsured subs, and hurricane damage to open frames before dry-in.


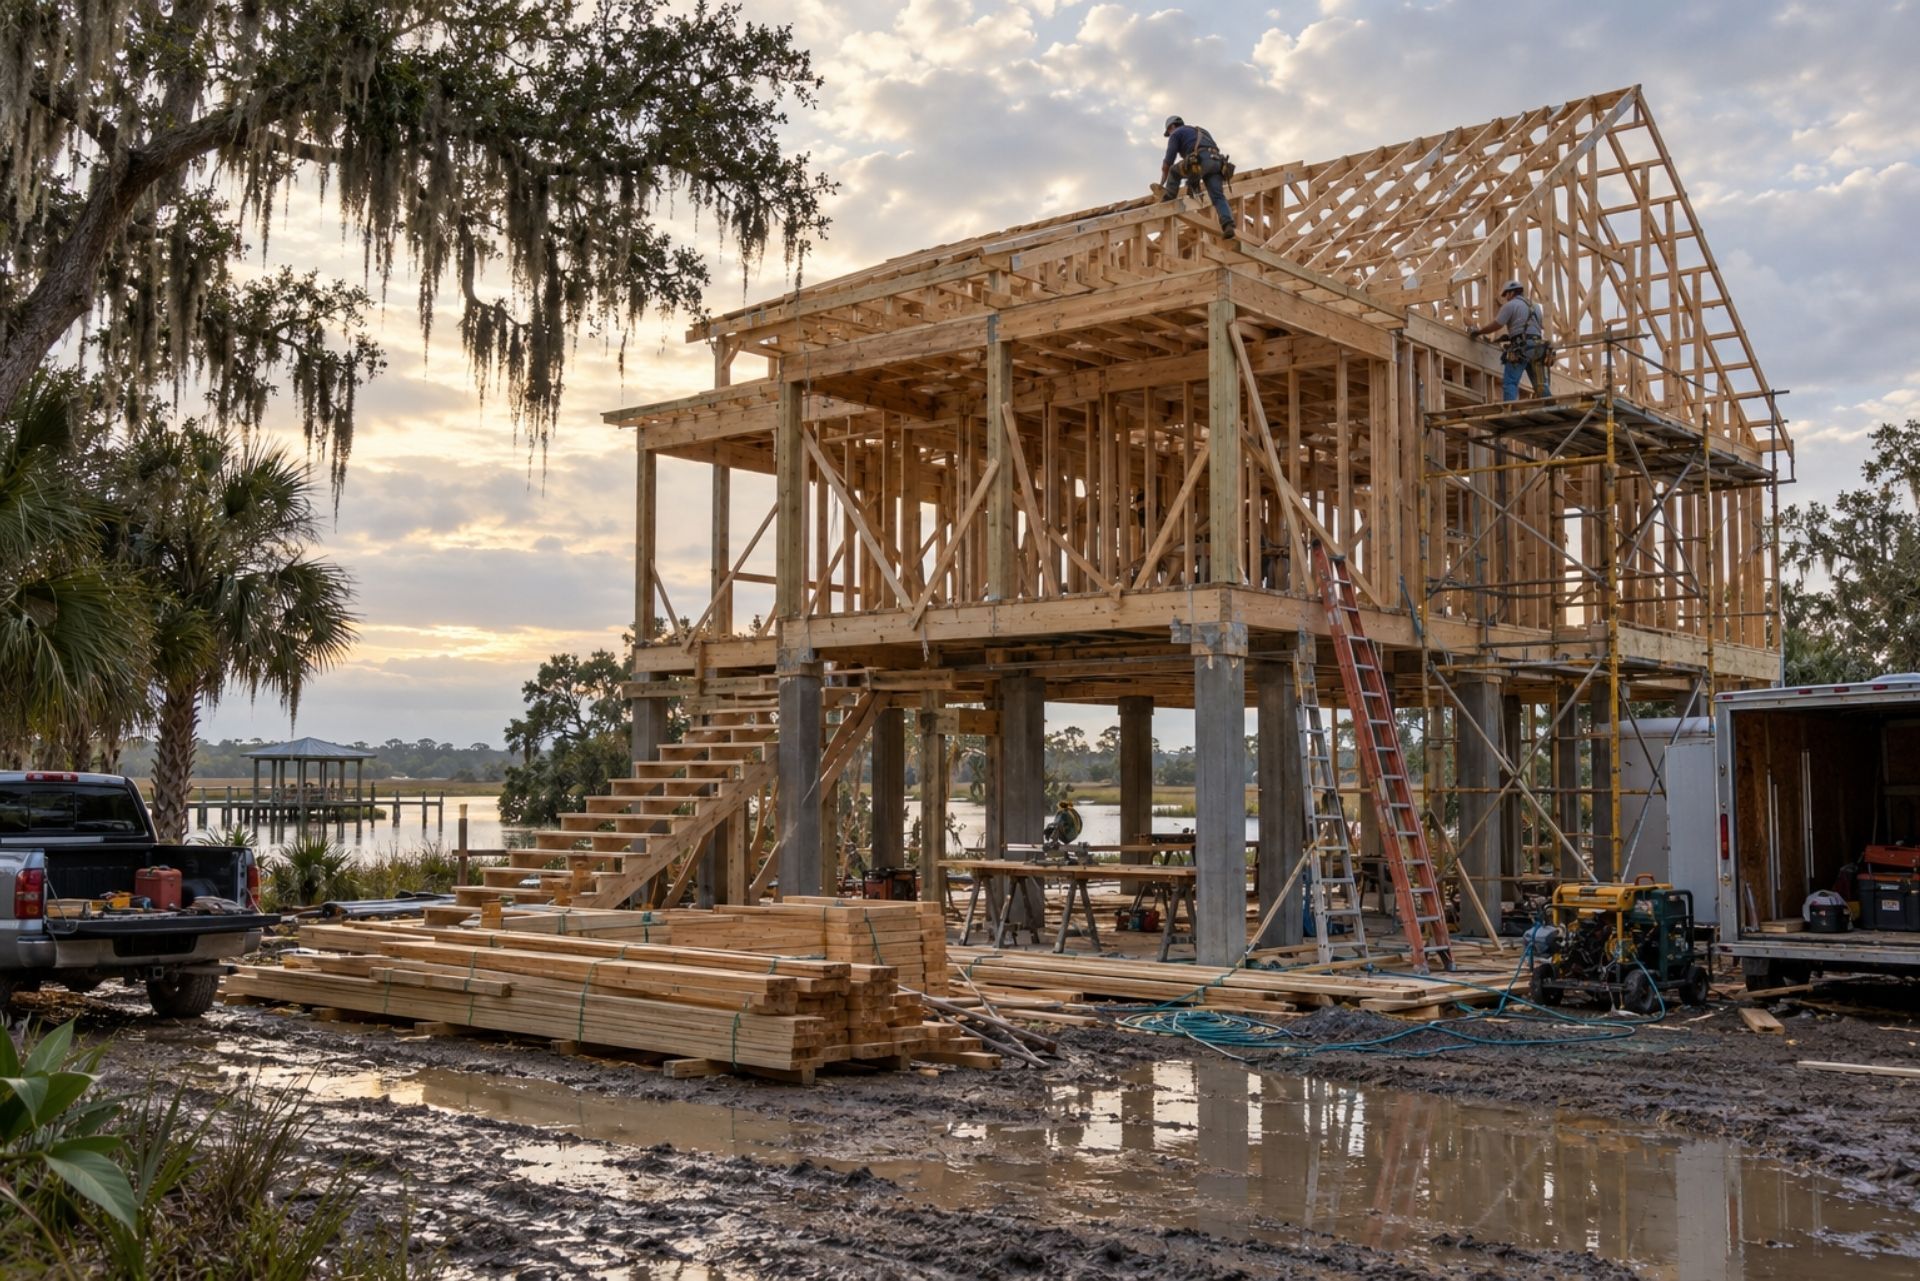
Picture a crew standing up walls on a pier-and-beam house in Slidell, with the deck sitting nine feet off the ground before the first stud goes in. That job carries more risk than a slab-on-grade ranch in most of the country, and carriers price it that way. If you frame in St. Tammany Parish, your insurance program has to account for height, payroll, subcontractors, and weather all at once. The rest of this page breaks down where those costs come from and what you can do about each one.

Louisiana Framing Contractor Insurance Essentials

Most framing businesses on the Northshore carry a core group of policies. Each one covers a different piece of the risk, and gaps between them are where contractors usually get hurt.


  • General liability: Covers third-party bodily injury and property damage, like a falling header damaging a neighbor's truck. Most general contractors require proof before you set foot on site.
  • Workers compensation: Pays medical bills and lost wages for injured employees. Louisiana requires it for most employers, and general contractors will ask for your certificate.
  • Commercial auto: Your personal auto policy typically won't respond to a crash in a truck hauling lumber for business.
  • Inland marine or tool coverage: Nail guns, compressors, and saws stolen from a jobsite may not be covered under general liability.
  • Builder's risk: Protects the structure itself while it's under construction. Who buys it depends on your contract.


A common mistake we see: a framer assumes the GC's builder's risk covers everything, then learns the policy excludes wind or was never purchased. Read your subcontract agreement and confirm in writing who insures the building during framing.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

How Do Fall Risks on Raised and Two-Story Homes Impact Your Rates?

South Louisiana's geography shapes how houses get built. Flood zones, base flood elevation requirements, and storm surge history push many homes in Slidell, Mandeville, and along the lake up on piers or pilings. Others go to two stories to fit more living space on a narrow lot. Either way, your crew works higher off the ground than framers in many other states.


Height changes claim severity. A fall from a six-foot wall plate might mean a sprained wrist. A fall from a second-story top plate on a raised home can mean spinal injuries, surgeries, and months of lost wages. Underwriters know this, and a single serious fall claim can follow your loss history for years.


Carriers respond in a few ways. Some may decline framers who do mostly elevated work, while others typically ask detailed questions about maximum working heights, fall protection plans, and harness use before quoting. Expect higher premiums or stricter conditions if you can't document a written fall protection program.


What helps at renewal: written safety rules, documented toolbox talks, guardrail or harness requirements above six feet, and photos of protection in use on real jobs. These details give your agent something concrete to show an underwriter.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Managing High Workers Comp Class Rates for Framers

Framing sits near the top of the construction rate chart. Market data shows class code 5403 (carpentry framing) often runs significantly higher than clerical roles, with some carriers charging over $5.00 per $100 of payroll. Residential carpentry under class code 5645 in Louisiana ranges from roughly $7.00 to $12.15 per $100 of payroll. On a $400,000 payroll, that difference alone can swing your premium by tens of thousands of dollars.


Benefit levels are climbing too. As of September 1, 2026, Louisiana raised the maximum weekly compensation rate to $903.00, based on a statewide average weekly wage of $1,204.02. Higher benefits typically put upward pressure on what carriers charge employers over time.


Classification matters more than most framers realize. If your office manager's payroll gets lumped into a framing code, you're paying framing rates for desk work. Ask your agent to review every employee's code at each renewal.


Your experience modifier (MOD) is the other lever. Formal safety programs and return-to-work policies, such as light duty for an injured carpenter, can improve your MOD and lower future premiums.

Louisiana Workers Comp Comparison Table

Factor Framing / Carpentry Clerical Office
Typical class code 5403 or 5645 8810
Rate per $100 payroll Over $5.00 (5403); $7.00 to $12.15 (5645) Far lower
Main injury types Falls, nail gun wounds, back strains Repetitive strain
Claim severity High, especially at height Low
Ways to lower cost Safety program, return-to-work, accurate codes Accurate codes

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Why Are Uninsured Labor Crews a Liability for Your Business?

Here's the scenario that wrecks budgets. You hire a four-man crew for the busy season, pay them by the job, and never collect a certificate of insurance. Six months later, your carrier's auditor shows up, sees $150,000 in payments to that crew, and adds it all to your payroll at the framing rate.


That's how audits work. If a subcontractor can't prove they carried their own workers comp, the carrier typically treats those workers as your employees and charges full premium for them. Many framers get an audit bill larger than their original annual premium and have 30 days to pay it.


Louisiana law raised the stakes in 2026. Effective August 1, House Bill 185 expanded the manual labor exception, allowing employees of independent contractors to recover workers compensation benefits from the principal contractor if they're substantially engaged in manual labor. Legal analysts describe it as closing a loophole used by uninsured labor crews. Framing is manual labor by definition.


Protect yourself with a simple habit:


  1. Collect a current certificate of insurance before any sub starts work.
  2. Verify the policy dates cover the full job.
  3. Keep copies organized by job for audit time.
  4. Re-check certificates at least every renewal cycle.

Protecting Against Wind Damage to Frames Before Dry-In

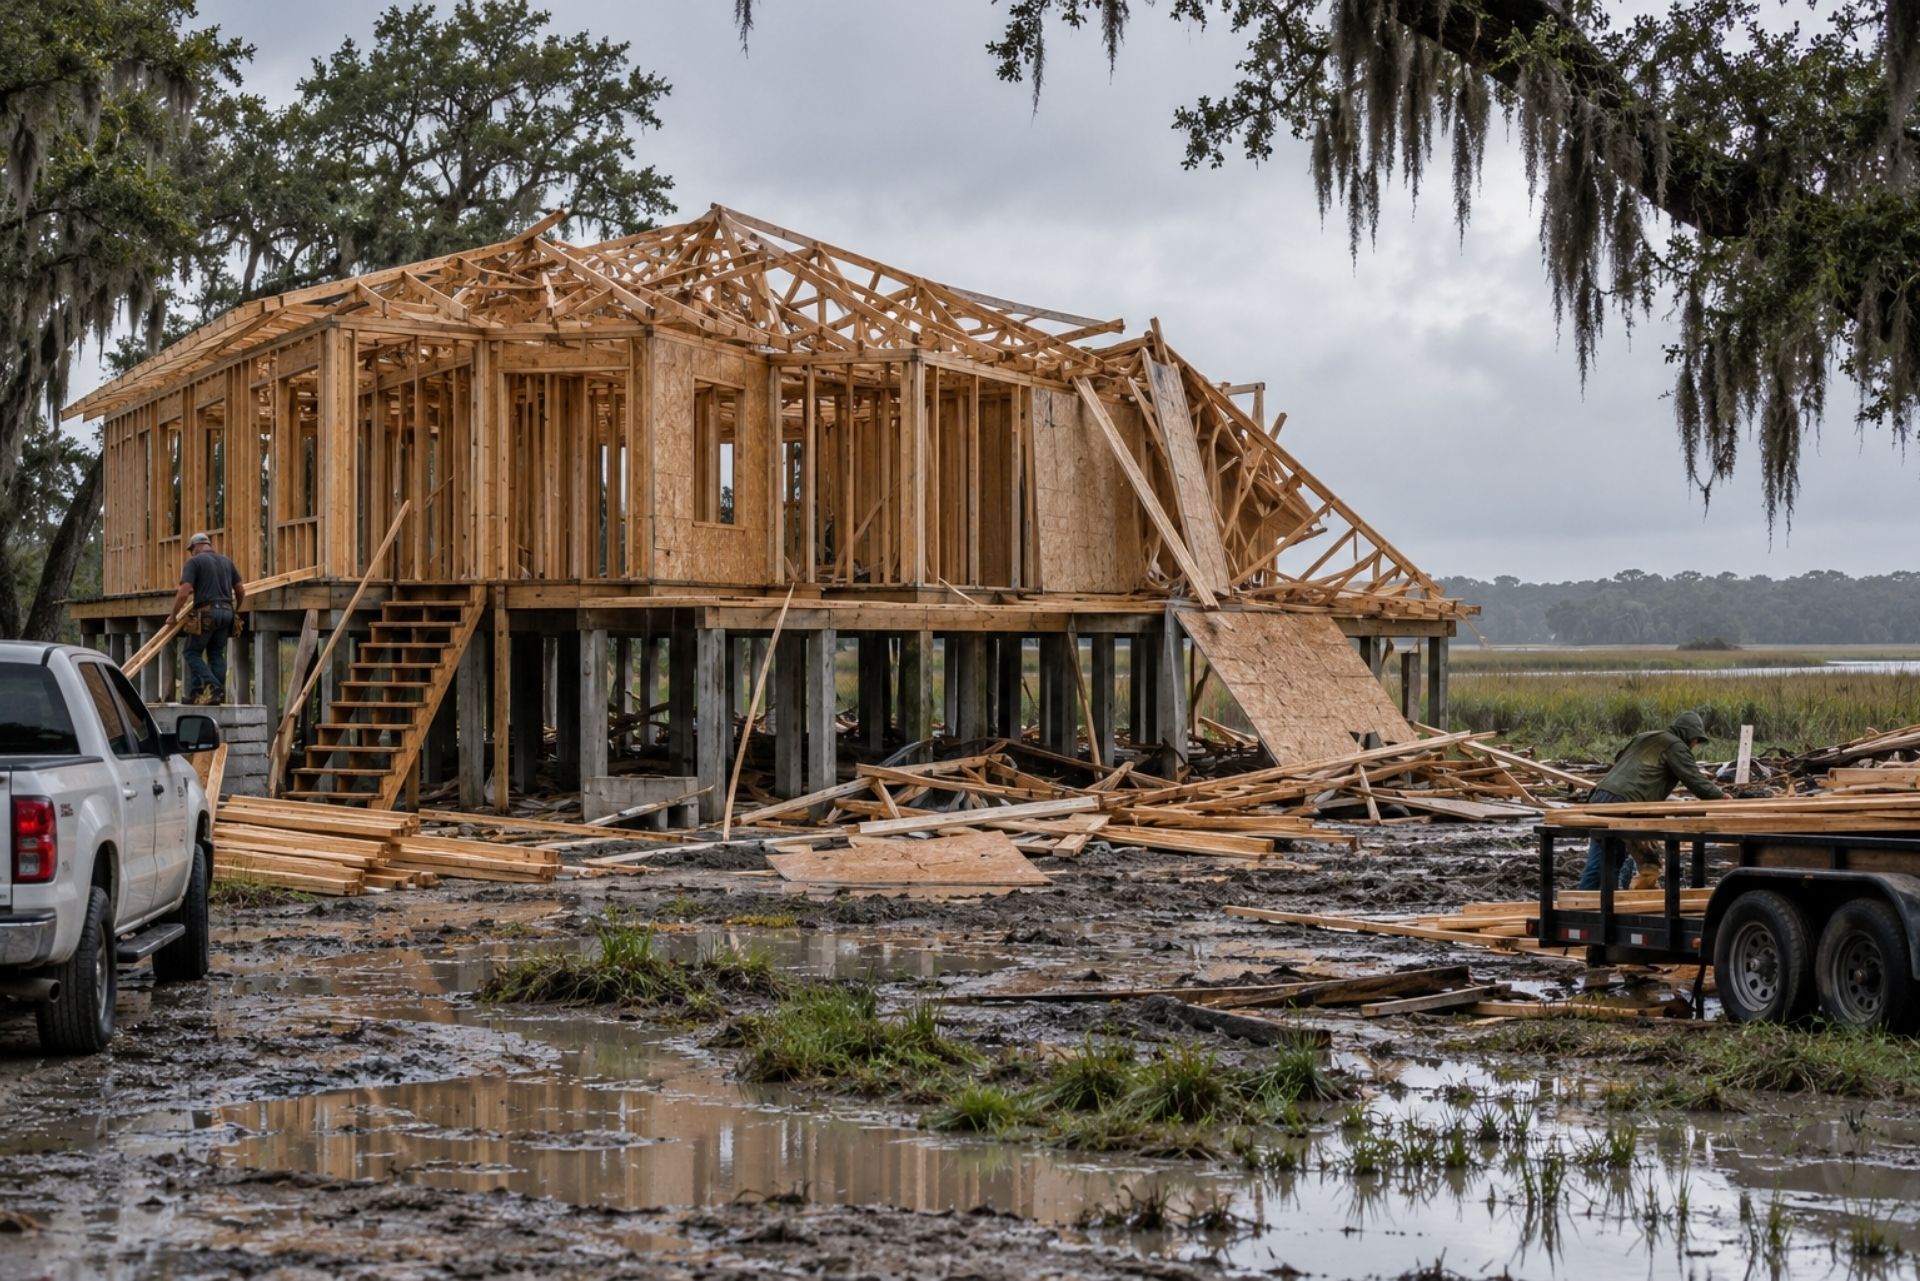
A framed house without sheathing, roof decking, or underlayment is basically a sail. Louisiana's hurricane season runs June through November, and even an afternoon thunderstorm can rack walls, snap trusses, or tip an unbraced gable end. The window between standing walls and dry-in is when the structure is weakest and the most money is at risk.


Builder's risk insurance is designed for this exposure. It covers the building and materials on site during construction. The catch is that many builder's risk policies in coastal Louisiana may exclude named storms or wind and hail entirely, or carry a separate percentage deductible that can run into thousands of dollars. You want to confirm, in writing, that wind and hail are included before the roof goes on.


Ask these questions before the job starts:


  • Does the policy include wind and hail, or is it excluded?
  • Is there a separate named storm deductible, and how is it calculated?
  • Does coverage include materials stored on site or in transit?
  • Who is the named insured: you, the GC, or the homeowner?


There's an upside for the homes you frame. Under Regulation 136, Louisiana insurers must offer premium reductions of 16% to 49% for homes built to the IBHS FORTIFIED standard by January 1, 2027. The Louisiana Fortify Homes Program also offers grants of up to $10,000 for FORTIFIED roof upgrades. Framers who understand FORTIFIED nailing and connection details can market that knowledge to builders and homeowners.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Common Questions About Louisiana Framing Insurance

Do I need workers comp if I only have two employees? In most cases, yes. Louisiana requires most employers to carry workers comp regardless of size, and general contractors will typically require a certificate either way.


What happens at my year-end audit? An auditor reviews your payroll and payments to subcontractors. Any sub without valid insurance may be added to your payroll, which can create a large additional premium.


Does general liability cover my own injured workers? No. General liability covers third parties, while employee injuries fall under workers compensation.


Who buys builder's risk on a new home in St. Tammany Parish? It depends on the contract. Usually the GC or homeowner buys it, but you should confirm in writing and check that wind coverage is included.


Can a safety program really lower my premium? It can. Documented safety and return-to-work programs may improve your experience modifier and give underwriters a reason to quote more favorably.


Why did my comp rate jump when I took on more raised homes? Carriers often price height exposure more heavily. Working on pilings or second stories may increase both claim frequency and severity in an underwriter's eyes.

What This Means for Your Business

Framing in Louisiana means working higher, paying more for comp, answering for every crew on your jobsite, and racing the weather to dry-in. None of those risks are going away, and the 2026 changes to benefit rates and the manual labor exception make sloppy paperwork more expensive than ever.


The framers who keep their insurance costs under control tend to do three things well: they document safety, collect certificates from every sub, and confirm wind coverage before the first wall goes up. A knowledgeable agent can help with all three.


Aubert Insurance Agency has insured businesses in Covington and Slidell since 1910, so we understand raised construction, Northshore storm seasons, and how Louisiana carriers look at framing risk. As an independent agency, we compare options from multiple carriers and explain what each policy covers, and what it doesn't, in plain language. Ready to see where your coverage stands? Start a Quote today.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461