













Covington & Slidell Independent Insurance Agents
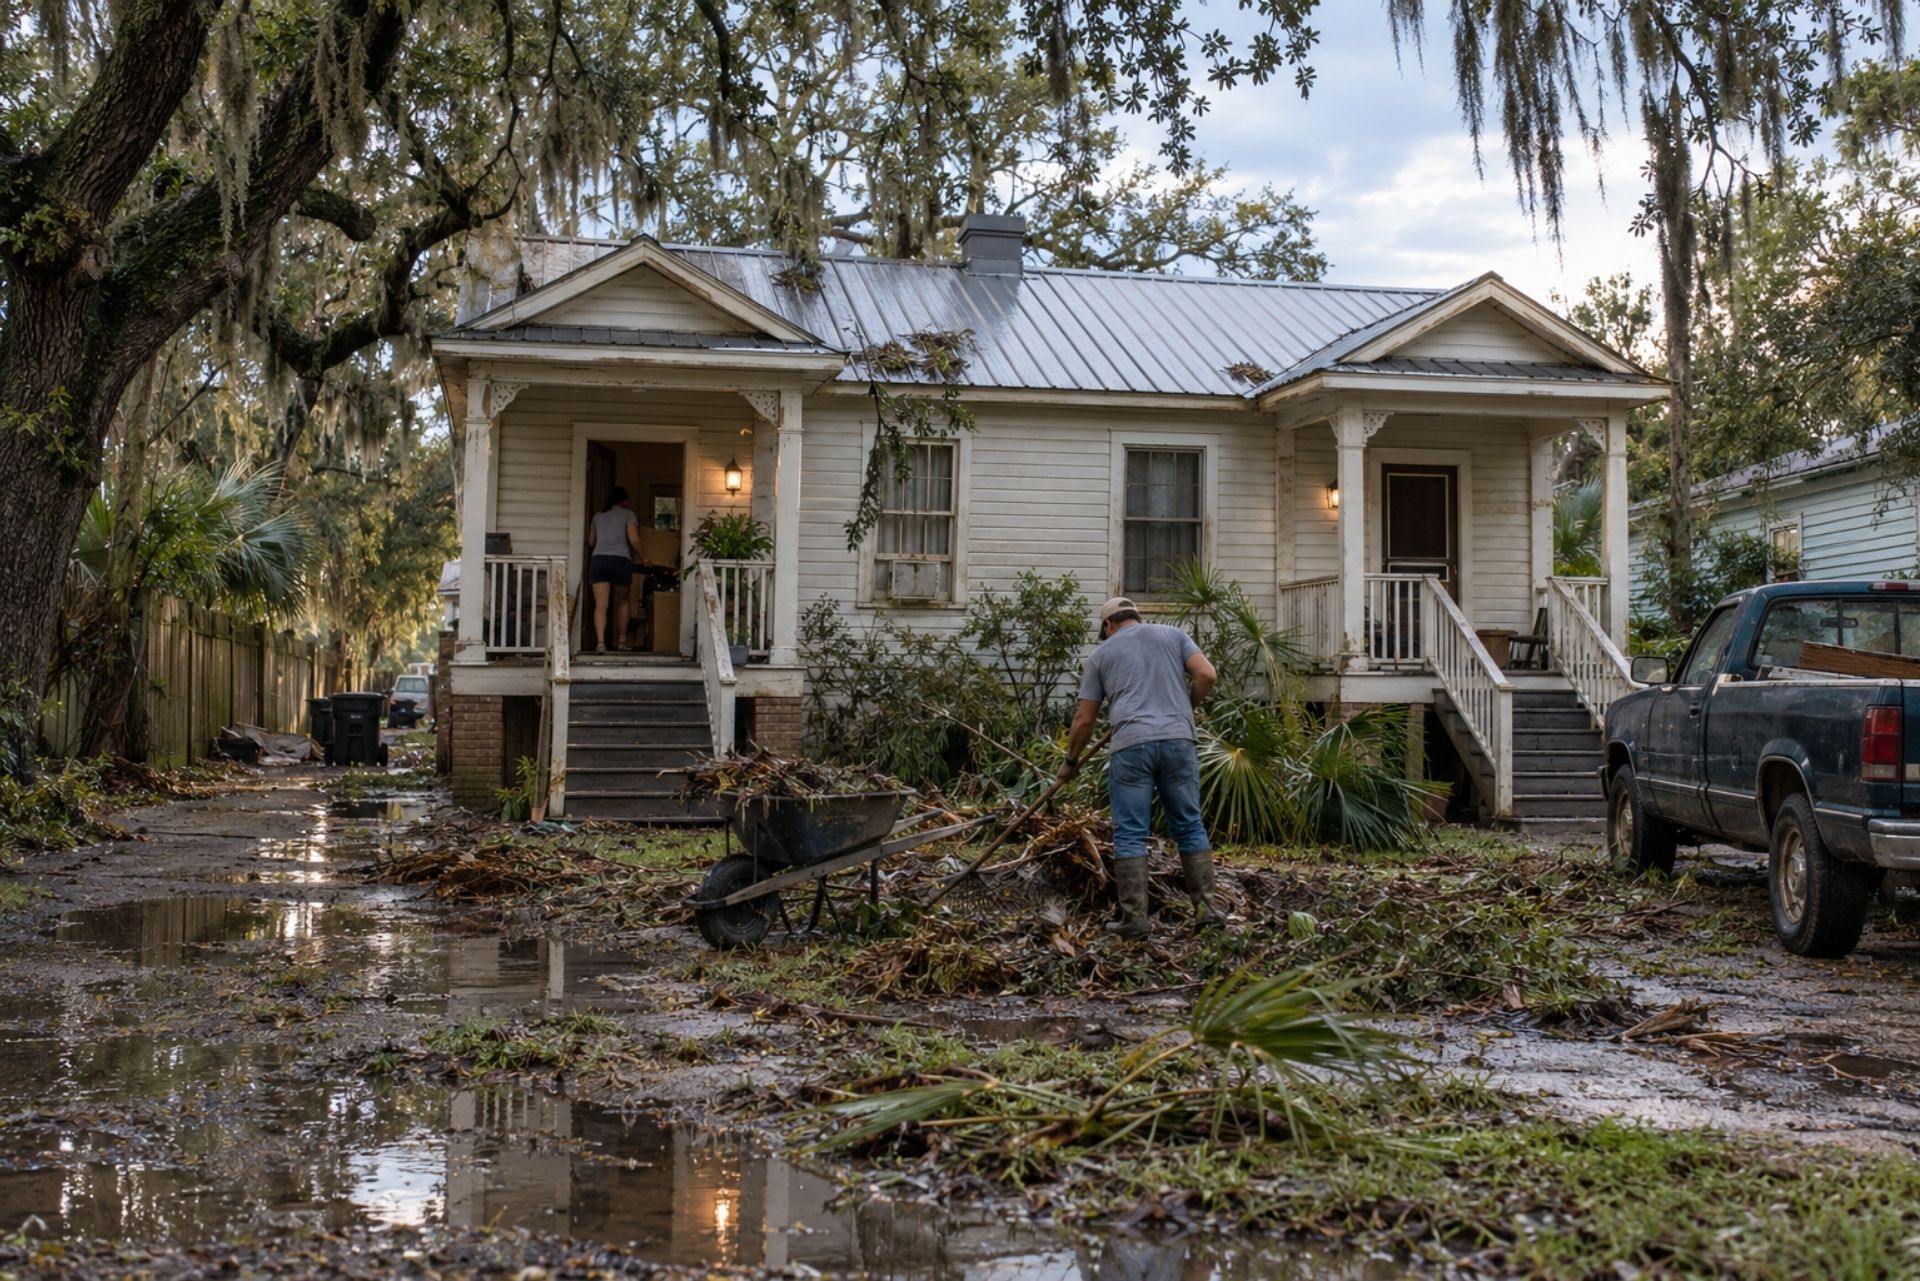
The call usually comes a few days after the storm passes. The roof on a Slidell double is peeled back, both tenants have moved in with family, and the landlord is reading the policy for the first time, wondering whether it covers the lost rent, how big the hurricane deductible will be, and what happens if a tenant trips on storm debris before repairs begin.
Those questions have answers. They are much easier to deal with before hurricane season than after it. If you own a single-family rental in Covington, a double in Slidell, or a few doors scattered across St. Tammany Parish, the policy you need differs from a homeowners policy. A small difference in policy language can decide whether a claim pays in full or barely pays at all.
The timing also helps owners in 2026. After several hard years, the Louisiana market has steadied. Statewide rate changes have hovered near 0.1% through April 2026, and new carriers have entered the state. That means comparing options is worth your time again. Here is how the pieces of a rental policy fit together.
Understanding Louisiana Dwelling Fire Policies for Rental Properties
Louisiana landlord insurance typically uses a Dwelling Fire form rather than a homeowners policy. It covers the structure of a rental house or double against named or open perils. Depending on the carrier, it can also add liability protection and fair rental value coverage for income lost after a covered loss.
Homeowners policies assume the owner lives in the home. Once you rent the property out, most carriers will not insure it under an HO-3, and a claim on a mis-written policy can be denied outright. Dwelling Fire policies, usually called DP forms, are designed for non-owner-occupied homes. They focus on the building itself and other structures such as a detached garage or shed.
A DP policy does not automatically include everything a homeowners policy does. Personal liability and premises medical payments are often added by endorsement rather than built in. Loss of rents may be limited, and contents coverage applies only to items you own, such as a stove or refrigerator you supply. Before you sign a renewal, read the declarations page line by line and confirm that liability actually appears on it.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Protecting Your Rental House or Double with the Right Policy Form
Doubles are common across south Louisiana, and they raise their own questions. You might live in one side and rent the other, or you might rent both. If you occupy one unit, some carriers may write a homeowners policy with a rental endorsement. If both sides are rented, a Dwelling Fire form is the normal fit. Tell your agent exactly how the building is used, because misstating occupancy is one of the quickest ways to have a claim challenged.
Age and condition matter too. Older raised cottages in Covington and pre-1980 doubles may only qualify for the most basic form until the roof, wiring, or plumbing is updated. Recent updates can open up broader coverage, so keep receipts and photos of any improvements.
Comparing DP-1, DP-2, and DP-3 Coverage Options
The three forms differ in which perils they cover and in how they pay you after a loss. Actual cash value (ACV) pays what the damaged item was worth, which means replacement cost minus depreciation. Replacement cost (RC) pays what it takes to rebuild with similar materials today.
| Feature | DP-1 (Basic) | DP-2 (Broad) | DP-3 (Special) |
|---|---|---|---|
| Perils covered | Short named list: fire, lightning, internal explosion; wind often by endorsement | Named list adds falling objects, weight of ice, sudden water discharge | All risks except listed exclusions |
| Typical payout on the building | Actual cash value | Often replacement cost | Typically replacement cost |
| Plain-language result | A 15-year-old roof pays out at a depreciated value | Rebuild cost is usually paid if limits fit | Strongest building protection |
| Loss of rents | Often limited or excluded | Commonly included | Commonly included |
| Who it suits | Older or vacant properties | Average rentals in good repair | Well-maintained or newer rentals |
On paper, the premium gap between a DP-1 and a DP-3 can look large. Then a $40,000 roof claim pays out at half its value. For most St. Tammany rentals in reasonable shape, a DP-3 is usually worth pricing first.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Recovering Loss of Rents After a Storm
Picture the Slidell double from the opening. Both units bring in $1,300 a month, and repairs take five months because contractors are booked across the parish. That adds up to $13,000 in lost income, while the mortgage, taxes, and premium still come due. Fair rental value coverage, often listed as Coverage D, is meant to fill that gap.
A few details decide how much it actually helps:
- Covered cause only. Rent loss usually pays only when a covered peril damaged the property. If flood caused the damage and you carry no flood policy, lost rent typically is not paid either.
- Time and dollar caps. Some forms limit benefits to a percentage of the dwelling limit, such as 10% or 20%, or to a set number of months.
- Civil authority. Certain policies may pay for a short period when a mandatory evacuation order blocks access, even without direct damage.
- Documentation. Keep signed leases and rent records. Adjusters want proof of income, not estimates.
Claim timelines can also stretch after a major event. After Tropical Storm Arthur in June 2026, the state's Emergency Rule 50 extended the time insurers had to begin loss adjustments to 60 days. A slower start can push back repairs and lengthen the rent loss, which is one more reason to buy enough months of coverage.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
| Feature | Basic Coverage | Extended Coverage |
|---|---|---|
| Property valuation | Actual cash value (depreciated) | Replacement cost (new item price) |
| Liability limit | $100,000 | $300,000 to $500,000 |
| Valuables (jewelry, guns, art) | Low sublimits, often $1,500 or less | Scheduled items at appraised value |
| Water backup from drains | Usually excluded | May be added by endorsement |
| Loss of use | Limited dollar cap | Higher cap or longer timeframe |
| Flood | Not covered | Still not covered (needs NFIP or private flood) |
| Named storm deductible | Percentage applies | Percentage applies, sometimes lower options |
Navigating Wind and Hail Deductibles in Coastal Louisiana
In south Louisiana, the wind deductible on a rental often matters more than its premium. Most policies here carry two deductibles: a flat all-other-perils deductible, such as $2,500, and a separate named storm or wind and hail deductible, usually set as a percentage of the dwelling limit.
That percentage can surprise owners. On a double insured for $300,000, a 5% hurricane deductible means you pay the first $15,000 yourself. A 2% option lowers that to $6,000 but raises the premium. Some carriers apply the percentage only to named storms. Others apply it to any wind or hail loss, including a spring hailstorm that has nothing to do with hurricane season. Ask which trigger your policy uses.
Louisiana gives landlords some protection on this point. Under R.S. 22:1337, you are limited to one hurricane or named storm deductible per calendar year. If two storms hit the same rental in one season, the second loss should not cost you a second full percentage deductible. Keep good records of the first claim so the credit is easy to show.
Your location affects pricing as well. Improved fire protection ratings in 18 Louisiana districts could save between $69 and $166 a year on a standard $250,000 dwelling. Fortified roof credits may also reduce wind premiums with participating carriers.
Liability Coverage When a Tenant Is Hurt on the Property
A tenant falls on a rotted back step you were told about in March. Their attorney sends a demand letter for medical bills and lost wages. Without premises liability on your policy, that claim is paid from your savings.
Landlord liability coverage typically pays for your legal defense and for settlements when you are found responsible for an injury on the property. The usual triggers come from conditions you control: stairs and railings, porch decking, exterior lighting, trees overhanging walkways, and repair requests that sat unanswered. Tenants and their guests can both bring claims. A separate medical payments coverage may pay small injury bills quickly, regardless of fault, which can keep a minor incident from becoming a lawsuit.
Security is a less obvious exposure. Louisiana tort law has held that landlords may be liable for criminal intrusions when they fail to maintain minimum security measures promised at the start of a lease. If your lease promises deadbolts or working gate locks, keep them working and document each repair.
Many owners carry $300,000 or $500,000 in liability. With several doors, a personal umbrella policy may extend that protection further, provided the umbrella carrier accepts rental exposures.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
Common Questions About Louisiana Landlord Insurance
Does my policy cover a tenant's personal belongings? No. Your Dwelling Fire policy covers the building and items you own. Tenants need their own renters policy, and many landlords require one in the lease.
What happens if a hurricane makes my rental uninhabitable? If wind damage is covered, fair rental value coverage may pay the rent you lose while repairs are underway, up to your policy limits. The building repairs go through the dwelling coverage, minus your named storm deductible.
Is flood damage included? Typically not. Flood requires a separate policy through the NFIP or a private flood carrier, and it usually has a 30-day waiting period, so do not wait until a storm is in the Gulf.
Can my insurer drop my rental with little warning? Effective July 1, 2026, Act 182 requires insurers to give at least 60 days' written notice before canceling or non-renewing a property policy. That gives you time to shop for replacement coverage.
My rental is with Louisiana Citizens. Am I stuck there? Not necessarily. A depopulation round scheduled for April 1, 2026, allows private insurers to take over Citizens policies, often at lower rates. An agent can also quote private options directly.
Does a short-term rental need different coverage? Usually, yes. Nightly and weekly rentals carry different risks, and many standard DP policies may exclude them unless you add a specific endorsement.
Making the Right Choice for Your Investment
A solid rental policy rests on four decisions. First, choose a DP form that pays replacement cost on the building. Second, carry enough fair rental value coverage to last through a slow rebuild. Third, set a wind deductible you could pay out of pocket the week after a storm. Fourth, buy liability limits that match how many tenants walk through your doors each day. If any one of these is weak, the policy can fall short when you need it.
The market is giving landlords more room to choose. Three new insurers, including Progressive Paloverde and GuardianPointe, were licensed to write in Louisiana through April 2026, and state regulators have been encouraging policyholders to shop around. Local insurance leaders have also discussed recent reforms and what's ahead for property owners in St. Tammany.
Aubert Insurance Agency has insured Louisiana properties since 1910 from offices in Covington and Slidell. As an independent agency, we compare rental coverage across multiple carriers and explain the exclusions before you sign. Start a Quote online, let us shop for you, and pick the plan that protects both your building and your rent checks.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













