













Covington & Slidell Independent Insurance Agents
Personal property covers furniture, clothing, tools and electronics. Jewellery, firearms and silver carry low internal caps, so we schedule those items separately when they are worth more than the cap.
Your belongings
Liability and loss of use
Liability answers injury and damage claims brought against you, and loss of use pays for somewhere to live while the house is repaired. Raising those limits is what our umbrella insurance page covers.
A Covington roofing contractor and a Slidell dental office both pay for workers comp, but their premiums can differ by thousands of dollars per employee. That gap comes down to class codes, payroll, claims history, and which carrier writes the policy.
Nearly every Louisiana employer with even one employee must carry workers compensation insurance. Your premium is typically calculated from payroll, an NCCI class code rate, and your experience modification factor. LWCC, LUBA, Stonetrust, and the Homebuilders Self Insurers Fund each may suit different business types, so comparing them side by side helps.
This guide covers who must carry Louisiana workers comp, how class codes and experience mods set the rate, and how those four markets compare. Business owners in St. Tammany Parish often tell us they renew the same policy year after year without knowing why the number changed. Understanding the mechanics puts you in a much stronger position at renewal, during an audit, or when a claim happens.
Who Must Carry Louisiana Workers Comp Insurance?
Louisiana takes a broad view of who counts as an employee. If you have at least one person working for you, whether full-time, part-time, or seasonal, you are almost certainly required to carry coverage. That includes the summer helper on a landscaping crew and the part-time receptionist who works two mornings a week.
The policy does two jobs. First, it pays medical bills and replaces a portion of lost wages for employees hurt on the job, regardless of who was at fault. Second, it generally protects the business from most injury-related lawsuits, because workers comp serves as the exclusive remedy for covered workplace injuries in most situations.
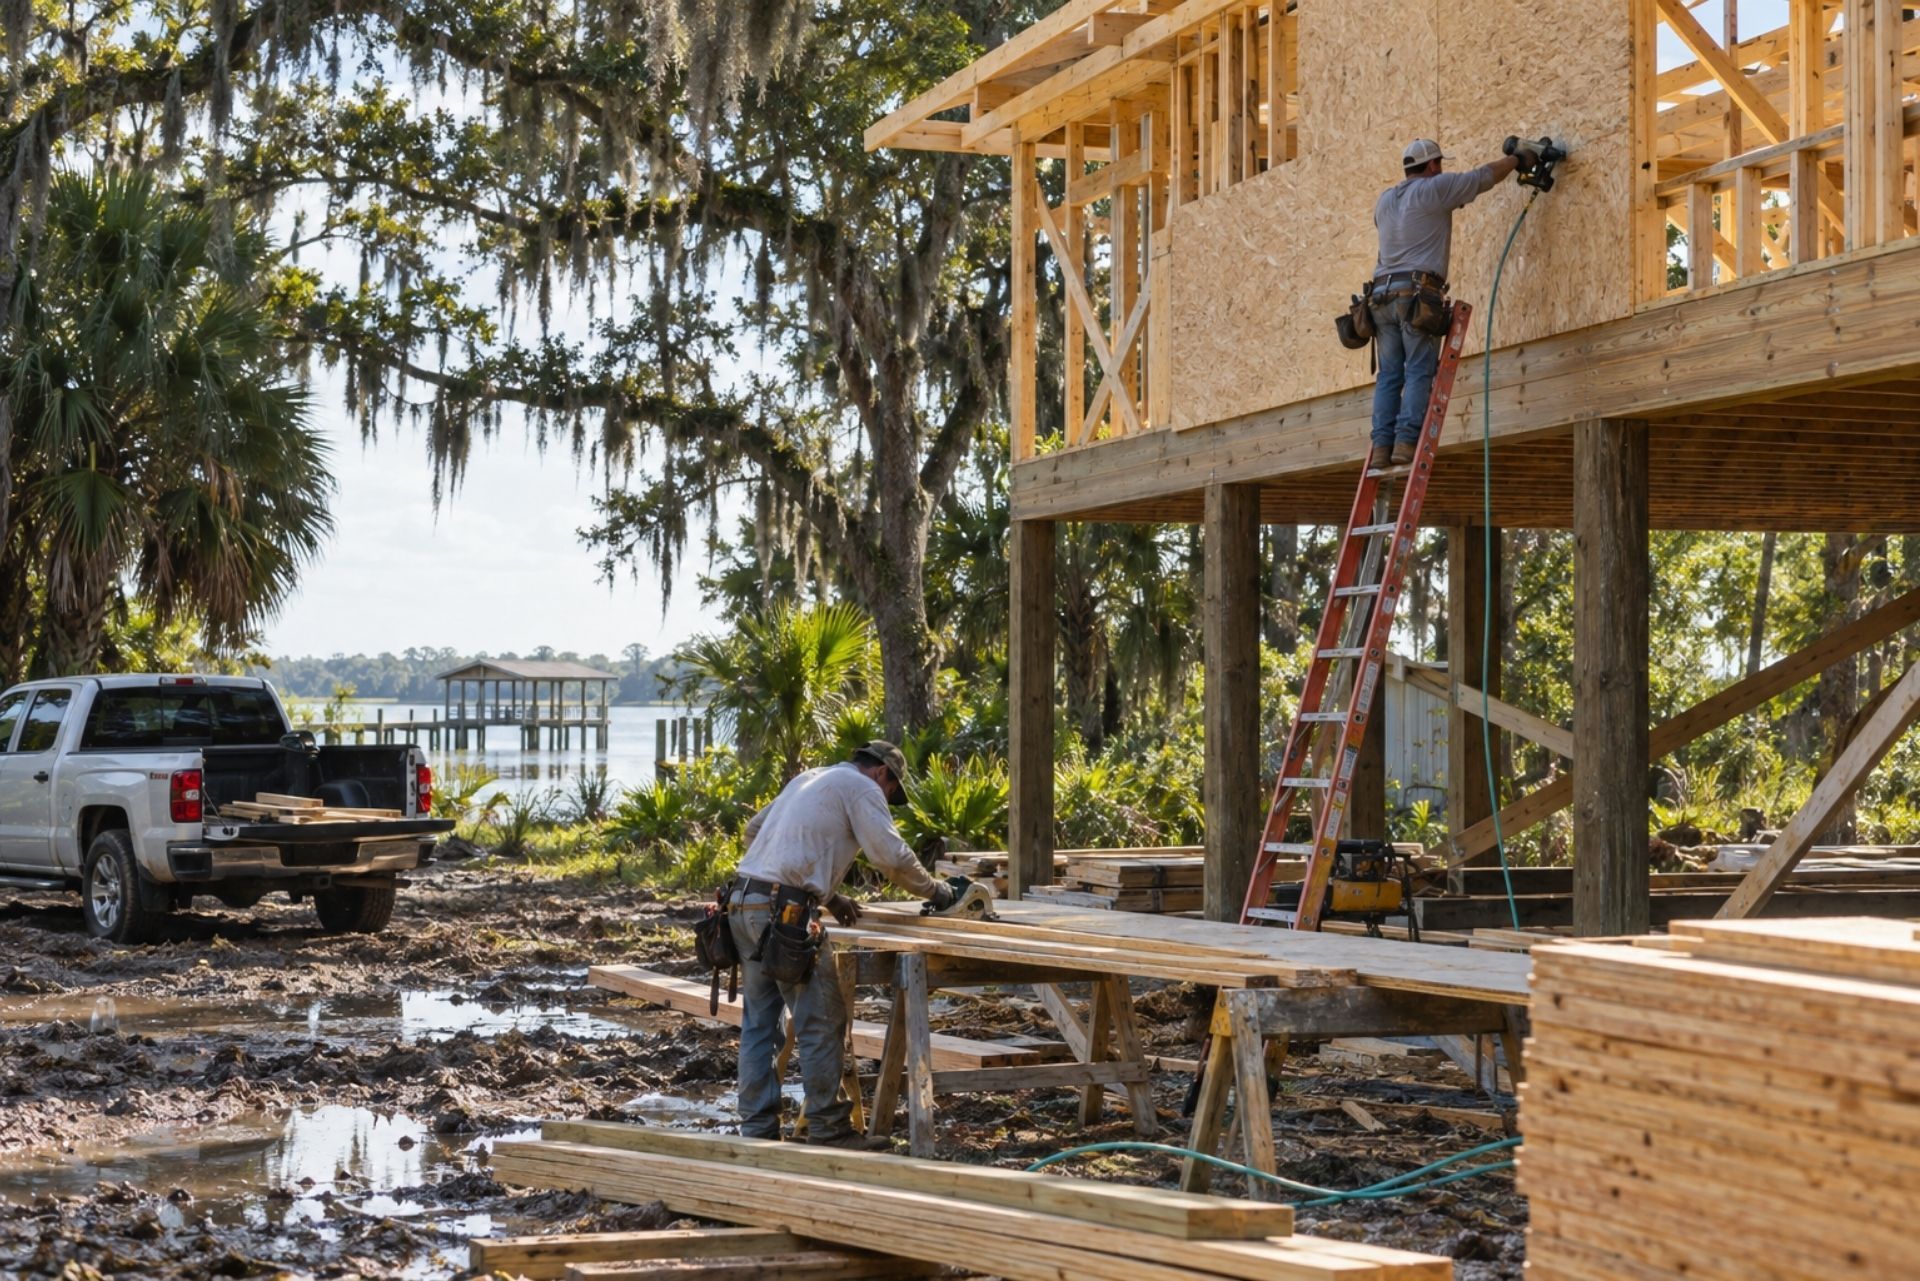
One change in 2026 deserves attention from contractors and anyone who hires outside crews. Effective August 1, 2026, House Bill 185 expanded the "manual labor exception", which allows employees of independent contractors to obtain benefits when they perform manual labor that is part of the principal's regular business. In plain terms, if you run a framing company and hire a contractor whose workers frame houses alongside yours, an injured worker from that crew may be able to look to you.
The most common mistake we see is a business assuming a 1099 label settles the question. It doesn't. Louisiana looks at the actual work relationship, and auditors look at it too. If an uninsured subcontractor's payroll lands on your audit, you can face an unexpected premium bill months after the policy year ends.
The system around these policies is also shifting. Act 766 of 2026 provided funding for an All Workers' Compensation Medical Claims Database, designed to store payment data and establish a firmer reimbursement schedule for medical and pharmacy claims. That could affect how claims costs are tracked statewide over time.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
How Class Codes and Experience Mods Set the Rate
Your workers comp premium isn't pulled from thin air. The basic formula looks like this:
- Take your estimated annual payroll and divide it by 100.
- Multiply that figure by the rate assigned to your class code.
- Multiply the result by your experience modification factor.
- Apply any carrier-specific credits, debits, or fees.
Each piece matters, but the first two variables, class code and mod, drive most of the difference between one business and another.
The Role of NCCI Class Codes
Louisiana uses the classification system maintained by the National Council on Compensation Insurance (NCCI). Every type of work gets a four-digit code, and each code carries a rate reflecting the injury risk tied to that work. Clerical office staff sit in a low-risk code. Roofers, tree trimmers, and steel erectors sit in some of the highest.
Here's where businesses get into trouble. Misclassification cuts both ways. If a carrier lumps your shop employees and your office manager into the same high-risk code, you overpay. If you classify a field employee as clerical to save money, the audit will catch it, and you'll owe the difference.
A practical example: a small HVAC company in Slidell might have two installers, one estimator who visits job sites, and a bookkeeper. The installers belong in an HVAC installation code, the bookkeeper in clerical, and the estimator's code depends on how much time he spends in the field. Tracking payroll separately by duty is what makes the split defensible at audit.
Market conditions also feed into these rates. NCCI data shows the workers comp system remained profitable in the 2025 calendar year with a combined ratio of 91%, even with a 0.2% decrease in net written premiums. A healthy system generally supports stable pricing, though your individual rate still depends on your own risk.
Understanding the Experience Modification Factor
The experience mod compares your claims history to that of similar businesses in your class code. A mod of 1.00 means you're average. Below 1.00, you pay less than the base rate. Above 1.00, you pay more.
To illustrate with hypothetical numbers: if your base premium works out to $20,000, a 0.85 mod lowers it to $17,000, while a 1.25 mod raises it to $25,000. Same payroll, same code, very different bill.
Mods typically look back at three years of claims, excluding the most recent year. That means a bad claim can follow you for years. Claim frequency often hurts more than a single large claim, because a pattern of small injuries signals ongoing risk. Businesses that report injuries promptly, manage return-to-work programs, and keep medical-only claims from turning into lost-time claims tend to see their mods improve.
Smaller employers may not qualify for a mod at all until their premium reaches a certain threshold. If you're unsure whether you have one, ask your agent to pull it.
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
How coverage choices change a Louisiana homeowners premium. Structure only — your rate depends on your property. [CONFIRM figures]
| Scenario | Dwelling limit | All-other-perils deductible | Named-storm deductible |
|---|---|---|---|
| Newer build, inland St. Tammany | $350,000 | $1,000 | 2% |
| Newer build, higher wind zone | $350,000 | $1,000 | 5% |
| Older home, updated roof | $275,000 | $2,500 | 2% |
| Older home, original roof | $275,000 | $2,500 | 5% |
| Fortified roof designation | $400,000 | $1,000 | 2% |
| Rebuilt after a prior claim | $400,000 | $2,500 | 5% |
| Bundled with auto | $350,000 | $1,000 | 2% |
Comparing LWCC, LUBA, Stonetrust, and the Homebuilders Self Insurers Fund
Louisiana has a strong group of homegrown workers comp markets, and the right one depends on your industry, size, and claims history. Here's how these four typically stack up.
LWCC remains the largest workers compensation carrier in Louisiana. It operates as a mutual-style company that returns money to policyholders in good years, and it announced a $90 million dividend distribution to more than 18,500 policyholders in April 2026. Dividends are never guaranteed, but they can meaningfully reduce net cost for businesses with clean records.
LUBA Workers' Comp is a regional casualty carrier writing coverage in 13 states, with deep roots in Louisiana. It held an "A- (Excellent)" financial strength rating from A.M. Best as of January 2026. LUBA may appeal to employers who want a carrier with strong local knowledge and a multi-state reach for workers who occasionally travel.
Stonetrust is another Louisiana-focused carrier that typically works through independent agents. It may be a good option for small and mid-sized employers across a range of industries, and underwriting appetite can vary by class code.
The Homebuilders Self Insurers Fund is a group self-insurance fund built around the residential construction trade. Eligibility typically ties to membership in a homebuilders association, and the fund structure means members share in the program's results. For residential builders and related trades, it may offer coverage designed specifically around their exposures.
Carrier Comparison Table
| Market | Structure | Typical Fit | Notable Feature |
|---|---|---|---|
| LWCC | Louisiana carrier, policyholder dividends | Broad range of Louisiana employers | Largest workers comp carrier in the state; $90M dividend announced April 2026 |
| LUBA | Regional casualty carrier | Employers wanting local roots with multi-state reach | A- (Excellent) A.M. Best rating as of January 2026 |
| Stonetrust | Louisiana-focused carrier | Small to mid-sized businesses | Typically written through independent agents |
| Homebuilders Self Insurers Fund | Group self-insurance fund | Residential builders and related trades | Membership-based; members may share in results |
No single market wins every time. A restaurant with a 0.80 mod might get its strongest terms from one carrier, while a residential framing crew might do better in the homebuilders fund. Shopping all four side by side is the only reliable way to know.

Common Questions About Louisiana Coverage
Do I need coverage for subcontractors? If your subcontractors don't carry their own workers comp, their payroll may be added to your policy at audit. With the 2026 changes to the manual labor exception, it's smart to collect current certificates of insurance from every sub before they start work.
How do I pay my premiums? Most carriers typically offer annual, quarterly, or monthly installments, and some offer pay-as-you-go billing tied to your actual payroll. Pay-as-you-go may reduce surprises at audit because premiums track real wages as you run payroll.
What happens at a premium audit? After the policy year ends, the carrier reviews your actual payroll and class codes. If payroll came in higher than estimated, you owe more; if lower, you may get a refund.
Can I cover myself as the owner? Louisiana generally allows certain owners, officers, and LLC members to include or exclude themselves depending on the business structure. Your agent can explain the paperwork and the tradeoffs before you decide.
Does workers comp cover injuries away from the job site? Coverage typically applies to injuries arising out of and in the course of employment, which can include travel between job sites or work errands. A normal commute from home usually isn't covered.
Why did my rate go up even though nobody got hurt? Changes in your class code rates, a payroll increase, or a mod calculated from older claims can all raise your premium. Ask your agent to break down which factor moved.
Making the Right Choice for Your Louisiana Business
Workers comp is required, but overpaying for it isn't. The businesses that keep premiums in check tend to do three things well: they keep class codes accurate, they manage claims so their experience mod stays low, and they compare carriers rather than renewing on autopilot. Watch the new manual labor rules too, especially if you use subcontractors.
Aubert Insurance Agency has served Covington and Slidell since 1910, and as an independent agency we compare LWCC, LUBA, Stonetrust, the Homebuilders Self Insurers Fund, and other markets in one place. We'll also walk you through how your policy works, including exclusions and audit details, so nothing catches you off guard.
Ready to see how your current policy measures up? Start a Quote with Kyle Beerbohm and get a clear, side-by-side look at your Louisiana workers comp options.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













