













Louisiana Fence Contractor Insurance

Covington & Slidell Independent Insurance Agents

Louisiana fence contractors typically need general liability with at least $500,000 in limits to keep a residential license, plus inland marine coverage for augers and trailers, commercial auto, and policy wording that clearly includes pool barrier and gate work. Utility strikes, boundary mistakes, and excluded pool jobs cause the most expensive coverage surprises.


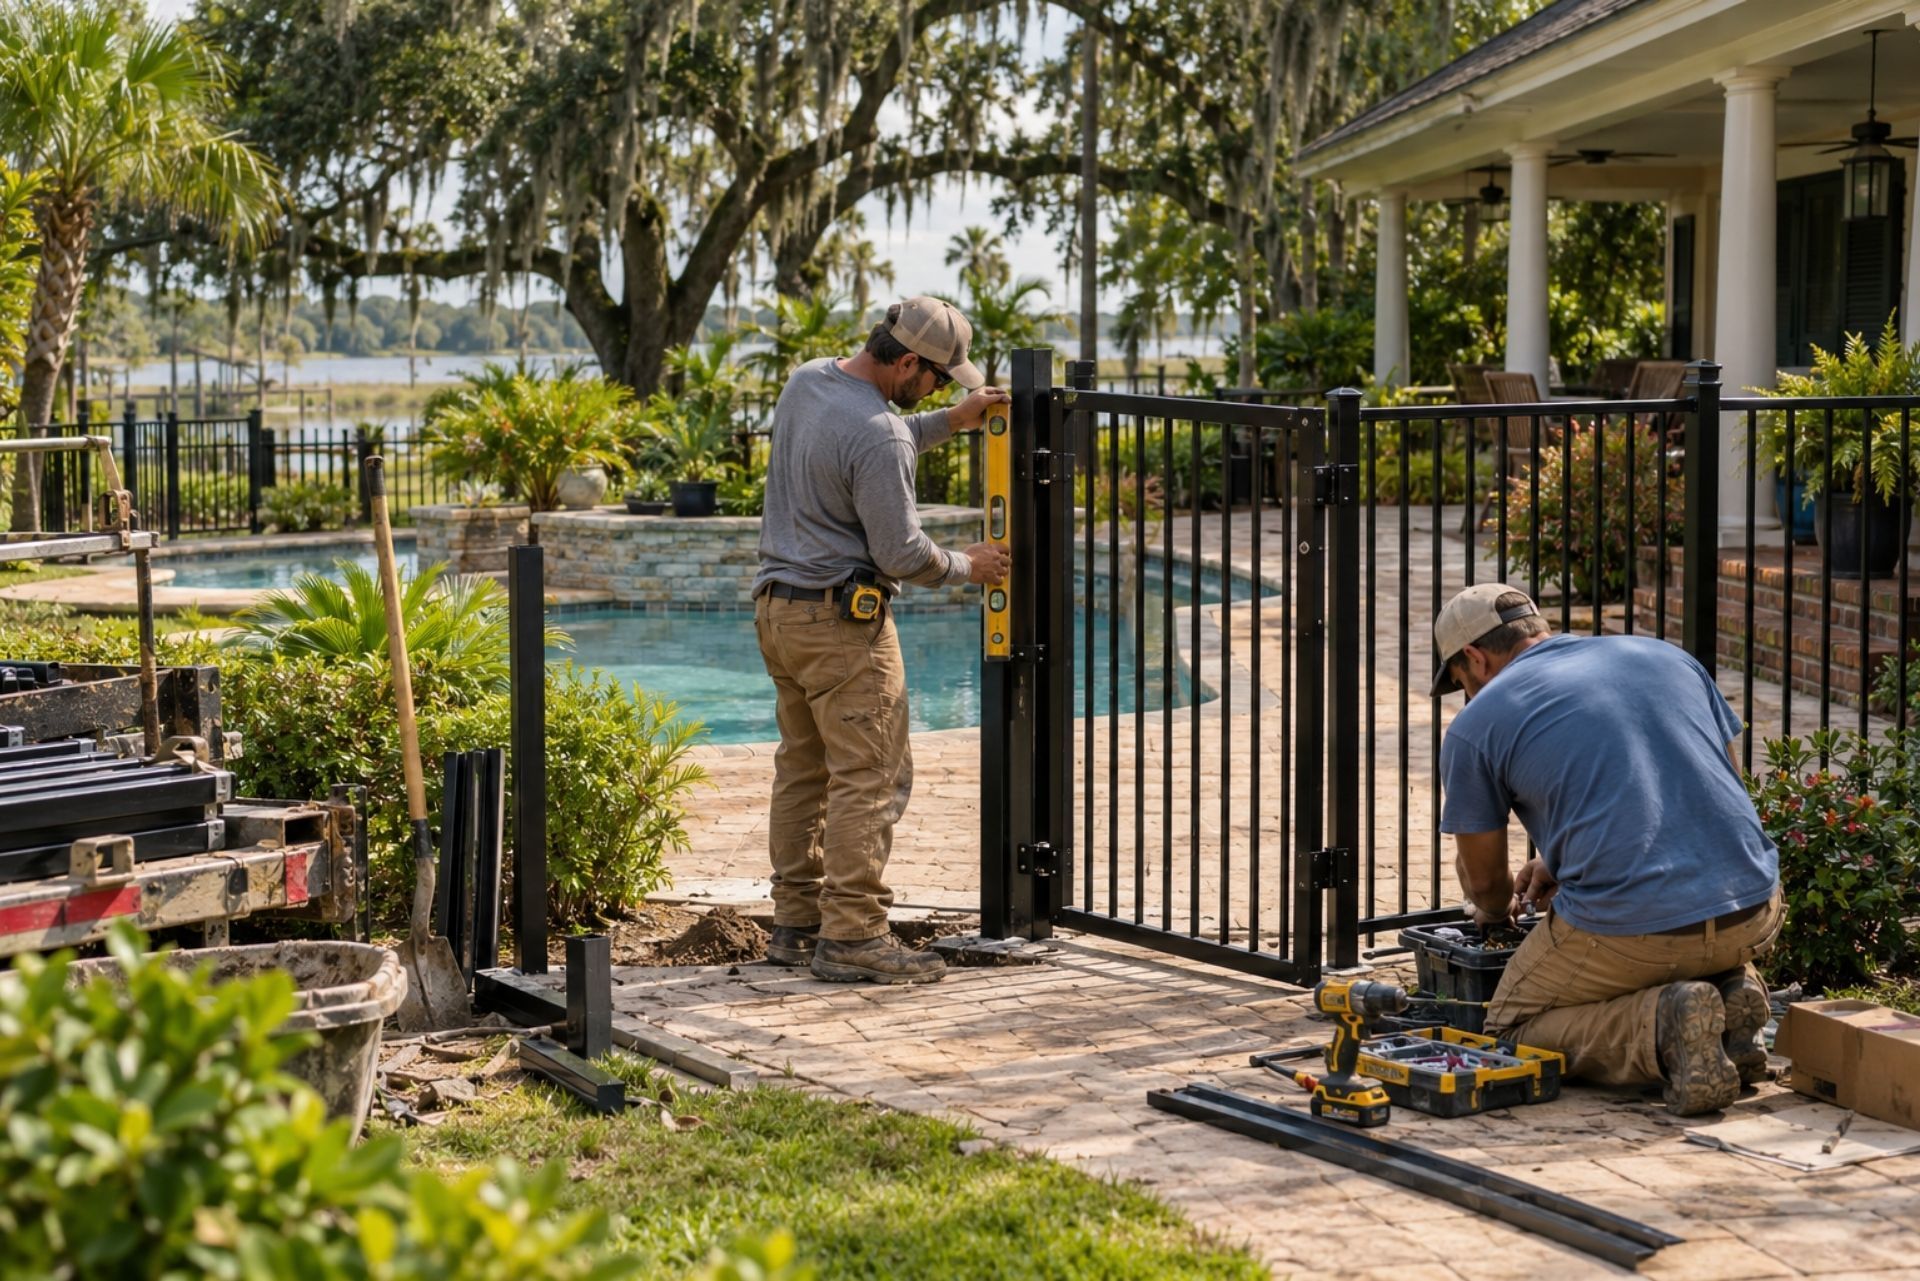
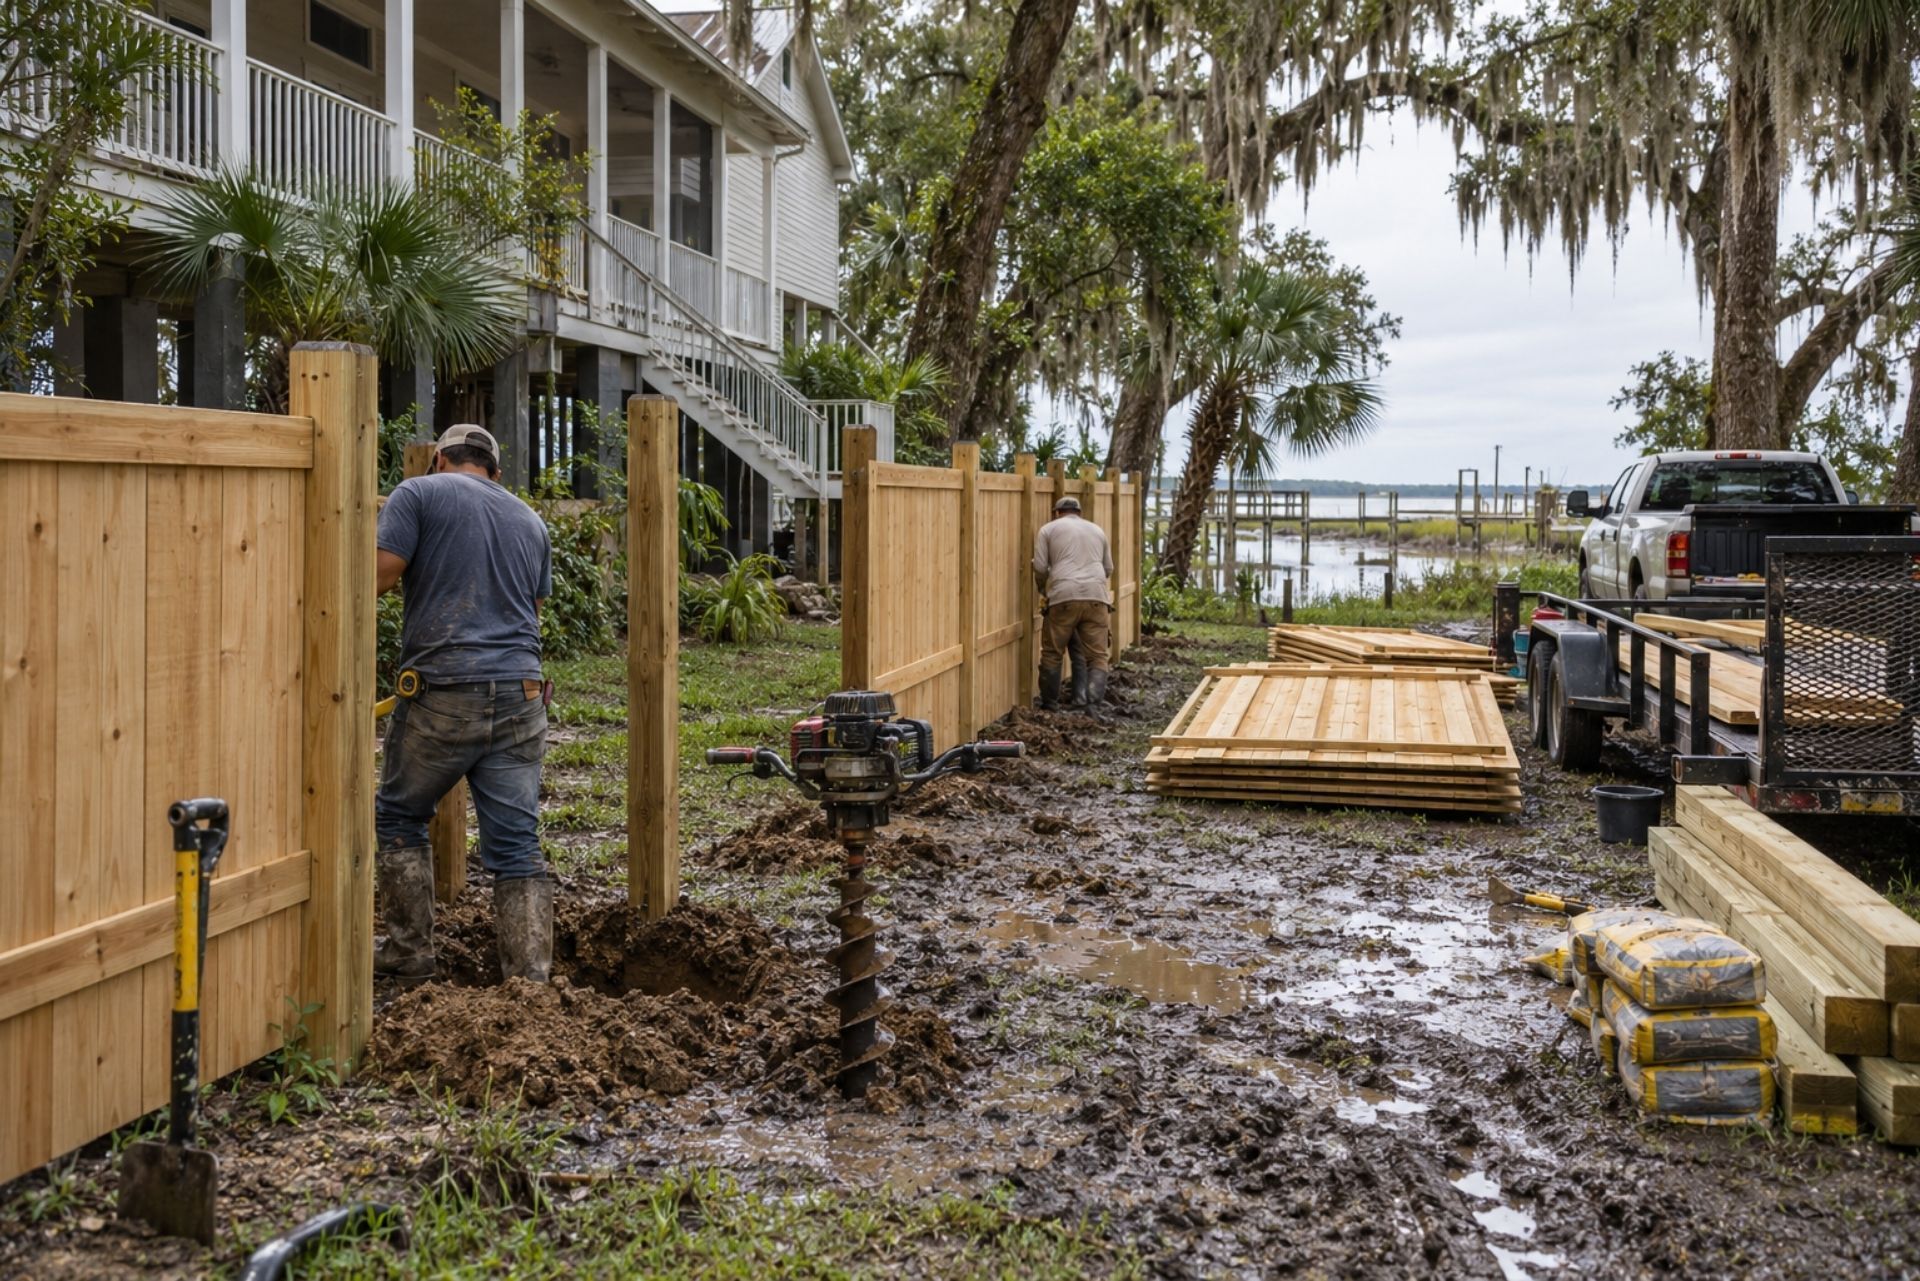
Fence work looks simple from the street. You dig some holes, set posts, hang panels, and move on to the next yard in Covington or Slidell. The risk sits underground, along survey lines, and inside the policy language most contractors never read until a claim lands on their desk.


A single auger strike on a fiber line can shut down a neighborhood's internet. A fence set eighteen inches onto the neighbor's lot can turn into a demand letter for removal and reinstallation. A pool gate that fails to self-latch can become a lawsuit no fence installer ever wants to face. Each of these scenarios hits a different part of an insurance program, and gaps between policies are where St. Tammany Parish contractors get hurt.


This guide walks through how coverage for Louisiana fence contractors handles underground utility strikes, property line disputes, gate operator and pool barrier liability, and the trailers and augers your crew depends on every day. We also cover the new 2026 rules that change how you dig and how much liability you carry.

Essential Insurance for Louisiana Fence Contractors

The baseline changed this year. Effective August 1, 2026, residential and home improvement contractors must carry at least $500,000 in general liability insurance to maintain their license with the Louisiana State Licensing Board for Contractors. If your current policy shows $300,000 per occurrence, your license, not just your coverage, is at stake.


A working fence contractor program in Louisiana usually includes:


  • General liability: Third-party property damage and bodily injury, including utility strikes and completed operations
  • Inland marine (contractor's equipment): Augers, post drivers, skid steer attachments, and tools
  • Commercial auto: Trucks and the trailers they pull
  • Workers' compensation: Crew injuries from augers, saws, and lifting
  • Umbrella: Extra limits above GL and auto for severe claims


Many contractors treat the GL certificate as the whole story because that's what homeowners and builders ask to see. That certificate tells a customer you're insured. It doesn't tell you whether your own trailer, your auger, or a pool gate job is actually covered.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

What Happens During Underground Utility Strikes While Digging?

Picture a crew on a Mandeville job hitting a gas service line at 30 inches. The first question an adjuster asks is whether you had a valid locate ticket. Starting August 1, 2026, enforcement officers can order the immediate cessation of excavation activities if they have reasonable cause to believe you're violating the Dig Law, including digging without a ticket.


The updated rules also require that excavators who damage a facility notify both the facility owner and Louisiana 811. At least one person on every excavation site must have completed Safe Digging training within the past year. Before you dig, confirm that member operators have issued their Positive Response showing whether lines are marked or clear of conflict.


Here's what that means for you on the insurance side. General liability typically responds to third-party damage from a strike, such as repair costs billed by the utility. Carriers may scrutinize claims where the crew skipped the ticket or ignored marks, and a stop-work order can cost you days of revenue that GL won't reimburse. Keep ticket numbers, photos of paint marks, and training records in a job file for every address.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Managing Property Line Disputes and Encroachment Risks

Boundary disputes are among the most frustrating claims fence contractors bring to us, partly because many of them aren't covered at all. If a homeowner points to a spot and says "put it there," and the fence ends up a foot onto the neighbor's lot, the neighbor may demand removal. Tearing out and reinstalling your own work is generally treated as faulty workmanship, which standard GL policies typically exclude.


What GL may cover is damage you caused to the neighbor's property along the way, such as a crushed irrigation system or a destroyed hedge row. The cost of fixing your mistake usually falls back on you. Some carriers offer professional or errors and omissions endorsements, but they're uncommon for fence trades, so prevention carries most of the weight.


A few habits that protect you:


  • Write into your contract that the property owner is responsible for identifying the boundary
  • Ask for a survey, or recommend one, on any lot where stakes are missing
  • Have the owner sign off on the line before the first hole goes in
  • Photograph pins, stakes, and string lines


These steps won't stop every dispute, but they move the liability where it belongs.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Gate Operator and Pool Barrier Liability Standards

Pool fences and automated gates carry a different level of risk than a cedar privacy fence. The potential claims involve children, drowning, and crushing injuries, and juries treat those seriously. This is where policy wording matters more than anywhere else in your program.

Meeting Louisiana Pool Safety Requirements

A 2026 lawsuit should get every fence contractor's attention. In Hiscox Insurance Co. v. All Babies Are Safe, Inc., the insurer sued to avoid defending a fence firm over a pool near-drowning claim. The contractor's policy was written for "fence installation" and excluded "pools." The case highlights why your GL policy needs to clearly include pool barrier work.


The common mistake is describing your business too narrowly on the application. If you install pool barriers, self-closing gates, or removable mesh fencing, say so. Then follow local code and manufacturer specs for gate height, latch placement, and self-closing hardware, and document each installation with photos and a homeowner sign-off.

Mechanical Gate Entrapment and Malfunction Risks

Automatic gate operators add motors, sensors, and moving arms to the equation. Entrapment injuries, vehicles struck by closing gates, and malfunctions after a power surge can all lead to bodily injury or property damage claims, sometimes years after installation. That's completed operations exposure, and you'll want to confirm your policy includes it with adequate limits.


Carriers may also ask whether you install, service, or only sell operators. Install photo eyes and edge sensors per the manufacturer's instructions, and leave written operating guidance with the owner.

Covington & Slidell Independent Insurance Agents

Protecting Your Trailers and Augers on the Job

A standard general liability policy won't pay to replace your own equipment. If someone steals your hydraulic auger from a job site in Slidell overnight, GL won't help. You need inland marine coverage, sometimes called a contractor's equipment floater, which is built for tools that move from site to site.


For small to mid-sized operations, inland marine policies covering augers, trenchers, and similar gear typically run between $400 and $1,500 per year. That range depends on scheduled equipment values, deductibles, and theft history. Schedule high-value items individually with serial numbers, and keep a blanket limit for smaller hand tools.


Trailers are trickier than most contractors expect. Your commercial auto policy usually extends liability to a trailer while it's attached, but physical damage to the trailer itself may require it to be listed on the policy. Commercial auto for Louisiana contractors typically costs $2,200 to $3,800 per vehicle annually in late 2026. Make sure the equipment loaded on the trailer is covered under inland marine, since auto policies generally exclude cargo you own.

not, unless you're both named on the policy. Each roommate typically needs their own coverage, and shared policies can get messy when one person files a claim.


Will my renters insurance cover my dog biting someone? Many policies include pet liability under personal liability, but some carriers exclude certain breeds or cap dog bite claims. Tell your agent about your pet upfront so there's no surprise later.


Does my landlord's insurance cover my belongings? No. Your landlord's policy typically covers the building only, so your furniture, clothes and electronics need your own policy.


When should I buy flood insurance before hurricane season? Aim for spring. NFIP contents coverage generally has a 30-day waiting period, so buying in late May means protection by the heart of the season.


What should I do to prepare my rental for a hurricane? Take a video walkthrough of every room, save receipts for big items in the cloud and keep a copy of your policy on your phone. Good documentation is the single biggest factor in how fast a storm claim gets paid.


Will renters insurance pay for a hotel if we evacuate? It depends. Loss of use typically kicks in when your rental is uninhabitable from a covered loss or when a civil authority orders evacuation, but check your policy wording.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Comparing General Liability and Inland Marine Coverage

Contractors often assume these two policies overlap. They actually cover opposite sides of the same jobsite: one protects others from you, the other protects your gear.

Situation General Liability Inland Marine
Auger hits a neighbor's water line Typically covered Not covered
Your auger is stolen from a site Not covered Typically covered
Customer trips over your materials Typically covered Not covered
Post driver damaged in transit Not covered Typically covered
Pool gate injury claim Covered only if pool work is included Not covered
Required for LSLBC license Yes, $500,000 minimum No

The pattern is simple once you see it. GL handles injury and damage to third parties, subject to exclusions like faulty workmanship. Inland marine handles your equipment, wherever it sits. A fence contractor with only one of the two has a gap big enough to sink a season.

Common Questions About Fencing Insurance in Louisiana

How much liability insurance does a fence contractor need in Louisiana? As of August 1, 2026, residential and home improvement contractors need at least $500,000 in general liability to keep an LSLBC license. Many contractors carry $1 million because builders and HOAs often require it.


Does my insurance cover hitting a gas or fiber line? General liability typically covers third-party damage from a utility strike. Digging without a valid 811 ticket can create problems with the claim and may lead to a stop-work order.


Will insurance pay to move a fence I put on the wrong side of the property line? Usually not. Redoing your own work is generally excluded as faulty workmanship, though damage to the neighbor's property may be covered.


Do I need special coverage to install pool fences? Yes, in the sense that your policy must clearly include pool barrier work. An exclusion for "pools" could leave you without a defense if a child is hurt.


Is my auger covered if it's stolen from my truck? Not under GL or most commercial auto policies. You need inland marine coverage for your tools and equipment.


What does an inland marine policy cost? For small to mid-sized fence operations, it typically runs $400 to $1,500 a year, depending on equipment values and deductibles.

not, unless you're both named on the policy. Each roommate typically needs their own coverage, and shared policies can get messy when one person files a claim.


Will my renters insurance cover my dog biting someone? Many policies include pet liability under personal liability, but some carriers exclude certain breeds or cap dog bite claims. Tell your agent about your pet upfront so there's no surprise later.


Does my landlord's insurance cover my belongings? No. Your landlord's policy typically covers the building only, so your furniture, clothes and electronics need your own policy.


When should I buy flood insurance before hurricane season? Aim for spring. NFIP contents coverage generally has a 30-day waiting period, so buying in late May means protection by the heart of the season.


What should I do to prepare my rental for a hurricane? Take a video walkthrough of every room, save receipts for big items in the cloud and keep a copy of your policy on your phone. Good documentation is the single biggest factor in how fast a storm claim gets paid.


Will renters insurance pay for a hotel if we evacuate? It depends. Loss of use typically kicks in when your rental is uninhabitable from a covered loss or when a civil authority orders evacuation, but check your policy wording.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Making the Right Choice for Your Fencing Business

The fence contractors who come through a bad claim in good shape tend to share a few traits. They pull 811 tickets every time, get boundary sign-offs in writing, describe pool and gate work honestly on their applications, and insure their augers and trailers separately from their liability. None of it is complicated, but each piece lives in a different policy.


Review your program before August 2026 deadlines catch up with you. Check your GL limit against the $500,000 license minimum, read your classification and exclusions for any mention of pools, and confirm every trailer and major tool is scheduled.


Aubert Insurance Agency has been insuring Louisiana businesses since 1910, and as an independent agency we compare coverage from multiple carriers so you're not stuck with whatever one company offers. We'll also explain exclusions in plain language so you know what your contract actually says. Start online, let us shop for you, and pick the plan that fits your crew. Start a Quote today.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
