













Covington & Slidell Independent Insurance Agents
Summit Insurance workers comp in Louisiana is written through local independent agents, and Aubert Insurance Agency, serving Covington and Slidell since 1910, is one of them. Summit is a Southeast workers comp specialist that may offer on-site safety consultants, in-house claims handling, and dividend eligibility for qualified employers with strong loss experience.
Picture a roofing contractor in Mandeville who just lost a crew member to a fall injury in July. The claim itself is stressful, but the follow-up questions hurt more: How long will he be out? Will my premium jump at renewal? Did my carrier do anything to help me prevent this? Those questions are why the choice of workers comp carrier matters far more than most St. Tammany business owners expect.
Many employers treat workers compensation as a box to check for state compliance. They buy whatever policy comes back with an acceptable number and don't think about it again until someone gets hurt. The carrier behind that policy shapes how claims get handled, how quickly employees return to work, and whether good safety habits ever pay you back. The sections below cover what a regional specialist like Summit may offer Louisiana employers and how to tell whether your business fits.
Understanding Workers Comp with a Southeast Specialist
Summit focuses on workers compensation in the Southeast instead of selling every line of insurance in every state. That focus matters in Louisiana, where heat, humidity, hurricane cleanup work, and a large construction and industrial base create injury patterns that national generalists don't always price or manage well.
Summit's coverage is also available only through local independent agents, not direct online sales. Aubert Insurance Agency has worked with businesses from offices in Covington and Slidell since 1910, so local owners get a person who knows the parish, the contractors, and the claim history behind a quote.
Financial strength is the other piece. Summit's managed carriers, Bridgefield Casualty Insurance Company and Bridgefield Employers Insurance Company, hold an A+ (Superior) rating from AM Best as of December 2025. A workers comp claim can stay open for years, so you want a carrier that will still pay benefits long after the injury.
As an independent agency, Aubert doesn't have to push Summit on everyone. If another carrier suits your operation better, you'll hear that plainly. Summit is one strong option among several, and the job is matching your business to the right one.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
The Role of Safety and Loss Control Support
Most employers find out what their carrier's safety support is worth only after a bad claim. With Summit, professional safety consultants may perform on-site field evaluations and help employers build drug-free workplace programs. These field assessments typically focus on identifying job-specific hazards, such as how a framing crew handles ladders or how a warehouse stages pallets near forklift lanes.
For high-risk work, Summit offers safety resources and industry-specific training for sectors like construction and excavation. A trench collapse or a struck-by injury on a Slidell site can turn into a six-figure claim. Training aimed at those specific exposures beats a generic safety poster in the break room.
Loss control matters after an injury, too. Summit's Back2work® program is designed to reduce claim duration through transitional duty. If an injured worker can't climb but can handle light-duty tasks, keeping that person working typically shortens the claim and keeps them connected to the job.
Policyholders may also have access to in-house adjusters and nurses who handle medical complexities. This matters because one of the most common mistakes we see is employers losing track of an open claim. A nurse coordinating care can keep a straightforward shoulder strain from dragging on for months.
The long-term payoff goes beyond fewer injuries. Fewer and shorter claims improve your experience modification factor, and that factor follows your business into every future renewal.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Accounting firms hold Social Security numbers, bank details, and tax records, which makes them prime targets. One industry observer put it bluntly: for most CPA firms, cyber insurance is no longer optional, and failing to meet MFA and EDR requirements can result in denied claims or total exclusion from the market. Translation: carriers now want multi-factor authentication and endpoint detection software in place before they will write you, and they may check after a claim. A cyber policy may cover breach notification, forensic investigation, ransomware response, and lawsuits from affected clients.
Cyber Liability
Dividend Eligibility for Louisiana Policyholders
Here's a piece of workers comp many Louisiana owners never hear about: some policies may pay dividends. A dividend is a partial return of premium that a carrier may declare for qualified employers whose loss experience comes in better than expected.
The catch is that dividends are never guaranteed. A carrier's board decides whether to declare them, and that decision depends on the carrier's own results as well as yours. Anyone who promises you a specific dividend amount at the time of sale is telling you something no one can honestly promise.
What typically drives eligibility:
- Loss experience: Fewer claims and lower claim costs during the policy period.
- Premium size: Some dividend plans have minimum premium thresholds.
- Plan type: Flat plans and sliding-scale plans work differently, and sliding-scale returns usually shrink as losses grow.
- Timing: Dividends usually come months after the policy period ends, once claims have developed.
This is where safety and dividends connect. An employer who uses the field evaluations, trains crews, and brings injured workers back on transitional duty is the employer most likely to have the clean loss record that dividend plans reward. If you're comparing quotes, ask your agent whether the policy is dividend-eligible and what plan structure applies, then judge the base premium on its own merits.

The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
The Types of Employers Summit Typically Fits
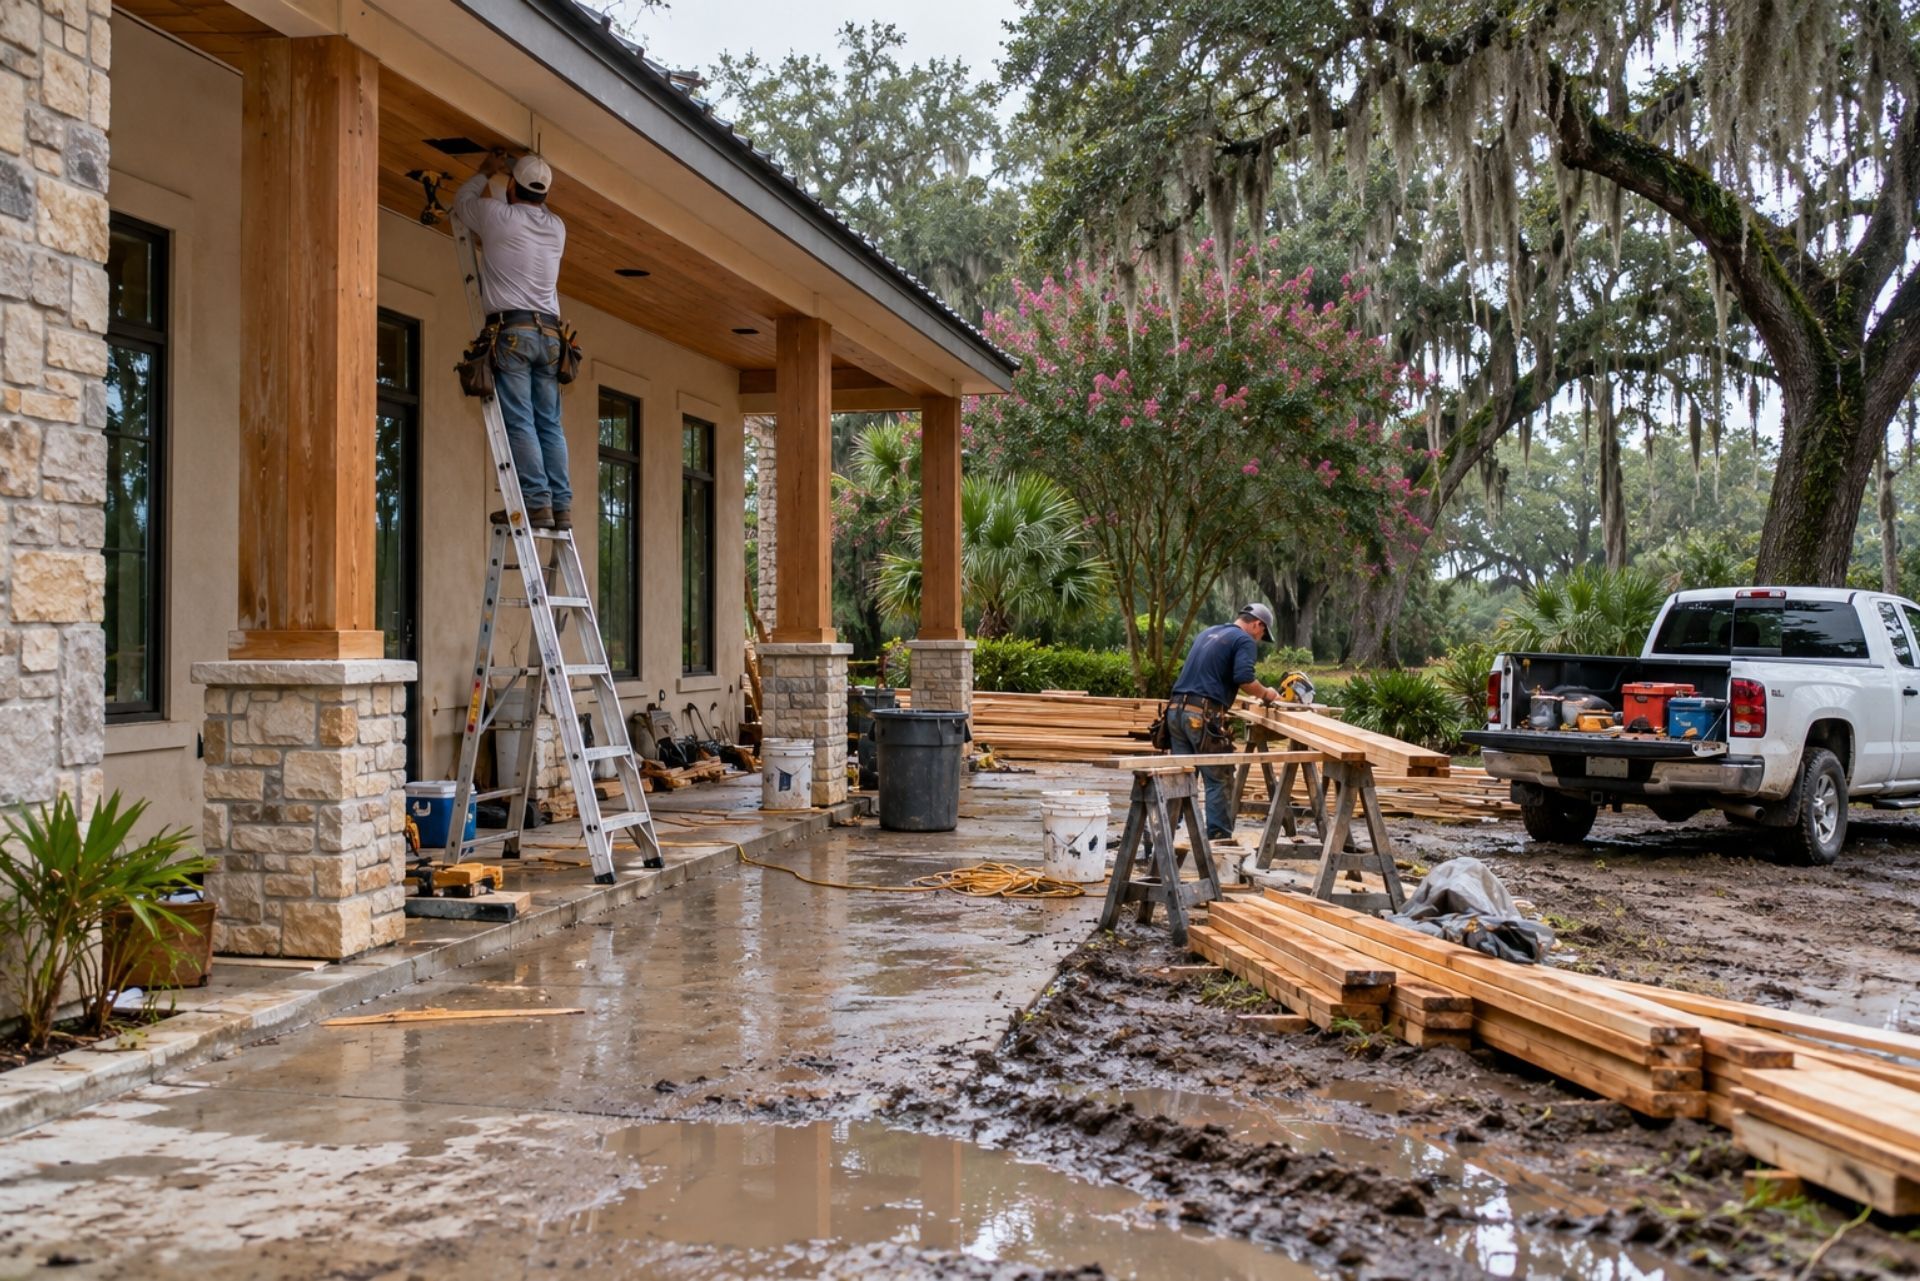
Summit generally looks for employers in industries where injuries are a real exposure and where a hands-on carrier can make a difference. Across the Southeast region where it operates, which includes Louisiana, these businesses typically align with its underwriting appetite:
- Construction trades: General contractors, roofers, framers, electricians, plumbers, and HVAC contractors.
- Excavation and site work: Dirt work, utility installation, and grading crews.
- Manufacturing and fabrication: Metal shops, millwork, and light industrial plants.
- Wholesale and distribution: Warehouses and businesses running delivery fleets.
- Healthcare and service businesses: Some assisted living, janitorial, and landscaping operations, depending on class codes.
Business size varies. Summit may write small and midsize employers, from a 10-person HVAC outfit in Covington to a manufacturer with a few hundred employees. Fit usually depends more on operations, safety culture, and loss history than on headcount. A five-person crew with clean records and written safety procedures can be a stronger candidate than a larger company with repeat back claims.
Employers who may not fit include businesses with very poor loss history or certain specialty classes outside the carrier's appetite. That's where an independent agency helps, because those accounts can go to other markets.
Comparison of Coverage Features
| Feature | Summit (Typical) | Generic Carrier (Common) |
|---|---|---|
| How you buy | Local independent agent | Agent, direct, or online |
| Safety support | On-site field evaluations may be included | Often online resources only |
| Claims handling | In-house adjusters and nurses | Varies, often outsourced |
| Return-to-work | Back2work® transitional duty program | Not always structured |
| Dividends | May be available to qualified employers | Less common |
| Regional focus | Southeast specialist | National |
How Jones Act Exposure Differs From State Workers Comp
Common Questions About Louisiana Workers Comp
What does workers comp cover? It typically pays medical bills and a portion of lost wages for employees injured on the job. It also generally protects the employer, since employees who receive benefits usually can't sue over the injury.
Do I need workers comp in Louisiana if I have only a few employees? Louisiana generally requires most employers with even one employee to carry coverage, with limited exceptions. Ask your agent to review your situation before assuming you're exempt.
Can I buy Summit coverage directly? No. Summit coverage is sold only through independent agents, so you'd work with a local agency like Aubert in Covington or Slidell.
Are workers comp dividends guaranteed? No. Dividends depend on your loss experience and the carrier's results, and they're never promised in advance.
What's a common mistake with workers comp? Misclassifying employees or underestimating payroll is a big one. Either can lead to a surprise bill at audit, so report payroll accurately and update your agent when job duties change.
How do I start a quote? Start online or call the Covington or Slidell office with your payroll estimates, employee job descriptions, and the last three to five years of loss runs. The agency shops the market and walks you through the options.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| What it covers | Physical injuries and property damage | Mistakes, oversights, bad advice |
| Example claim | Client slips in your lobby | Missed tax deadline costs a client penalties |
| Included in a BOP? | Usually yes | Usually no |
| Who needs it | Nearly every office with visitors | Accountants, consultants, agencies giving advice |
| Policy trigger | Usually occurrence-based | Usually claims-made |
Making the Right Choice for Your Business
A workers comp policy is more than a premium number. For Louisiana employers in construction, excavation, manufacturing, and similar fields, a Southeast specialist like Summit may bring safety consultants to your job sites, keep nurses involved in claims, help injured workers return through transitional duty, and potentially reward a clean loss record with dividends. None of that is guaranteed for every business, which is why fit matters as much as price.
Before you renew, pull your loss runs, look at how your last claim was handled, and ask whether your current carrier has ever set foot on your site. If the answers disappoint you, it's time to compare.
Aubert Insurance Agency has helped St. Tammany businesses sort through these decisions since 1910, and we'll explain exactly what your policy covers and excludes. Start a Quote with our Covington or Slidell office today and see whether Summit, or another carrier, fits your crew.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Visit
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













