













Covington & Slidell Independent Insurance Agents
Lacombe drivers typically need more than Louisiana's 15/30/25 minimum liability, especially when commuting Highway 190 or 434 to I-12, towing boats, or driving rural roads where deer strikes are common. Comprehensive coverage handles animal collisions. Aubert Insurance Agency, serving Louisiana since 1910, compares multiple carriers to fit your situation.
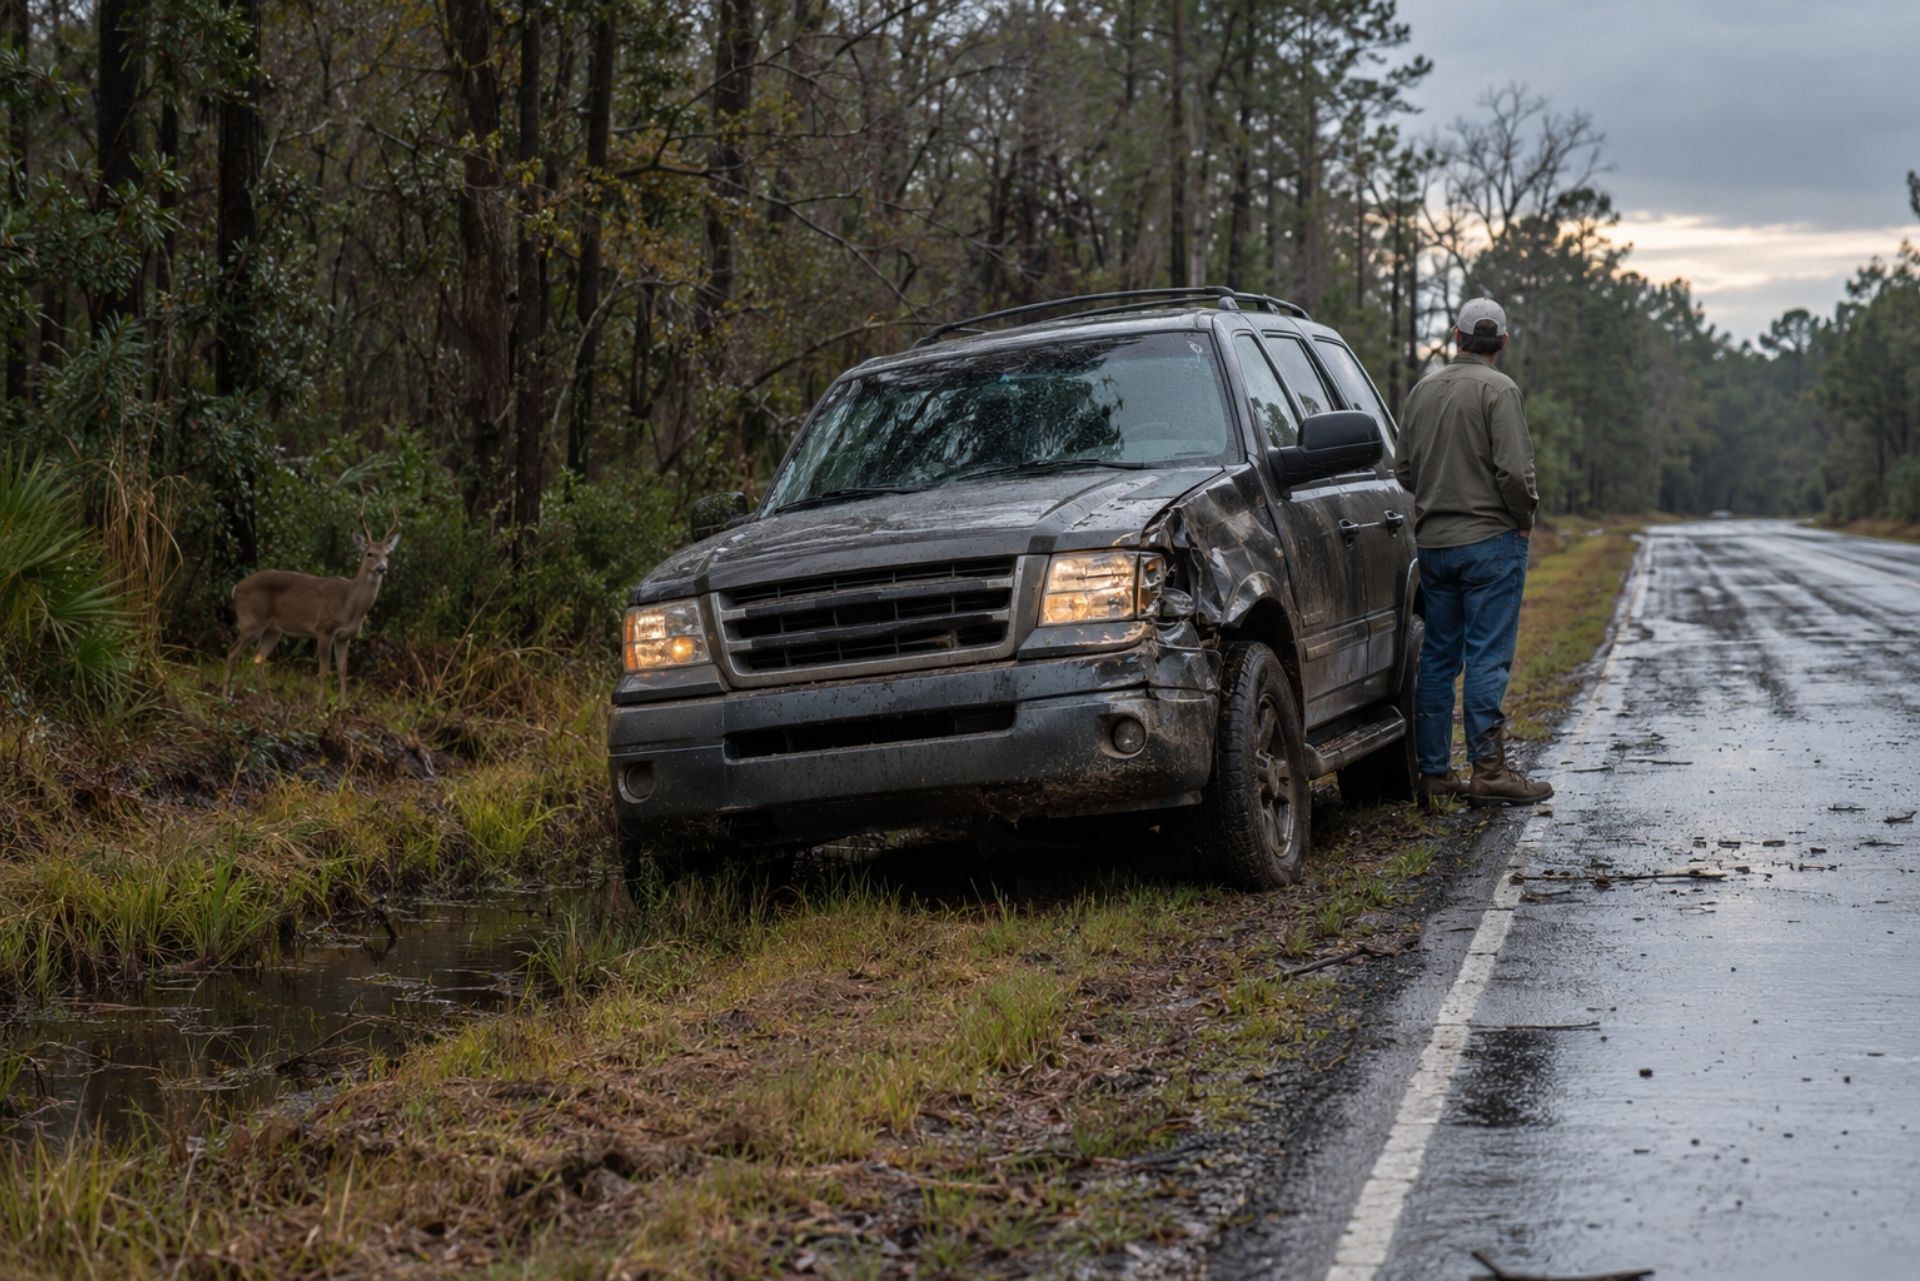
Picture a Tuesday in early November. You leave Lacombe before sunrise, headed down Highway 434 toward I-12, coffee in the cupholder, and a doe steps out of the tree line near the bayou. Most Lacombe drivers know that moment, or know someone who's paid a body shop because of it.
Car insurance in this corner of St. Tammany Parish works differently than it does in a dense subdivision in Mandeville. The roads are two-lane in long stretches. The trucks are bigger, and plenty of them have a boat or utility trailer hitched on the weekend. Commutes stack rural miles on top of interstate miles. All of that shapes how claims happen and which coverage gaps hurt the most.
This guide walks through Lacombe auto coverage the way a local agent would: by the routes you drive, the things you tow, the wildlife you dodge, and the liability limits that actually hold up when something goes wrong. Louisiana passed significant insurance reforms in 2025, and several of those changes affect Lacombe households directly.
Navigating Lacombe Car Insurance Requirements
Louisiana sets the floor, not the target. The state's minimum liability requirements for 2026 remain 15/30/25, which means $15,000 for bodily injury per person, $30,000 per accident, and $25,000 for property damage. That's the legal minimum to register and drive in Lacombe.
Here's the problem with stopping there. A new pickup truck can easily cost more than $25,000 to replace, and a single hospital stay after a serious crash can blow past $15,000 in days. Once your limits run out, the rest becomes your personal problem.
The 2025 reforms raised the stakes for anyone tempted to let a policy lapse. Under HB 434, uninsured motorists are barred from recovering the first $100,000 in bodily injury and $100,000 in property damage, even when the other driver caused the wreck. Skipping a payment for a month could cost you far more than the premium ever would.
A second change matters too. HB 450 eliminated the Housley Presumption, so plaintiffs must now prove through medical testimony that an injury was caused by the accident. That typically means documenting injuries quickly and getting checked out after any crash, even one that seems minor.
Aubert Insurance Agency has been insuring Louisiana families since 1910, and our approach hasn't changed: explain how the policy works before you sign it, including the exclusions most people never read.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.
Here's a common scenario: you misjudge a curve and clip a late-model pickup, injuring the driver. A single ambulance ride, ER visit, and follow-up imaging can eat through $15,000 quickly. Anything above your limit can become your personal responsibility, which may put your savings, wages, or home at risk.
| Scenario | Dwelling limit | All-other-perils deductible | Named-storm deductible |
|---|---|---|---|
| Newer build, inland St. Tammany | $350,000 | $1,000 | 2% |
| Newer build, higher wind zone | $350,000 | $1,000 | 5% |
| Older home, updated roof | $275,000 | $2,500 | 2% |
| Older home, original roof | $275,000 | $2,500 | 5% |
| Fortified roof designation | $400,000 | $1,000 | 2% |
| Rebuilt after a prior claim | $400,000 | $2,500 | 5% |
| Bundled with auto | $350,000 | $1,000 | 2% |
Commuting via Highway 190 and Highway 434 to I-12
Most Lacombe commuters reach I-12 one of two ways. Highway 190 runs east-west through town toward Slidell and Mandeville, while Highway 434 heads north to the interstate interchange. Both carry a mix of local traffic, work trucks, and drivers trying to make up time before they hit the on-ramp.
That mix creates predictable claim patterns. Rear-end collisions near turn lanes and business driveways on 190 are common, along with sideswipes when someone merges late approaching I-12. Once you're on the interstate, speeds jump and so does the severity of any crash.
Road conditions have improved on part of this route. A $4 million improvement project on US 190 between LA 434 and LA 433, covering pavement patching and asphalt overlays, wrapped up in late summer 2026. Smoother pavement helps, but it doesn't change the basic exposure of a daily commute that blends two-lane highway with interstate traffic.
For commuters, a few coverages tend to carry more weight:
- Uninsured/underinsured motorist coverage: protects you when the at-fault driver carries only state minimums or nothing at all
- Medical payments coverage: may help with immediate costs while fault is sorted out
- Rental reimbursement: keeps you getting to work while your vehicle sits in the shop
The Risk of Rural Collisions and Animal Strikes
Leave the main corridors and Lacombe turns rural fast. Unlit roads, tree lines close to the shoulder, and wetlands near Bayou Lacombe all create spots where deer, hogs, and other animals cross without warning.
Statewide, Louisiana drivers have a 1 in 215 chance of hitting an animal, which ranks the state 36th nationally. That sounds moderate until you consider when the risk concentrates. In Area 4, which includes St. Tammany, the peak deer collision period runs from September 26 through February 26 during the rut. That's five months of heightened risk, much of it during dark morning and evening commutes.
One detail catches people off guard. Hitting an animal is typically a comprehensive claim, not a collision claim. If you swerve to avoid the deer and hit a tree instead, that usually falls under collision. Drivers who carry liability only have neither, so the whole repair bill lands on them.
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
| Coverage Area | State Minimum | Common Higher Option | Stronger Option |
|---|---|---|---|
| Injury, one person | $15,000 | $50,000 | $100,000 |
| Injury, per accident | $30,000 | $100,000 | $300,000 |
| Property damage | $25,000 | $50,000 | $100,000 |
| Who it fits | Legal compliance only | Riders with modest assets | Homeowners, families, higher earners |
Here's a common scenario: you misjudge a curve and clip a late-model pickup, injuring the driver. A single ambulance ride, ER visit, and follow-up imaging can eat through $15,000 quickly. Anything above your limit can become your personal responsibility, which may put your savings, wages, or home at risk.
Minimum Coverage vs. Actual Protection Needs
The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.
Insuring Trucks Towing Boats and Trailers
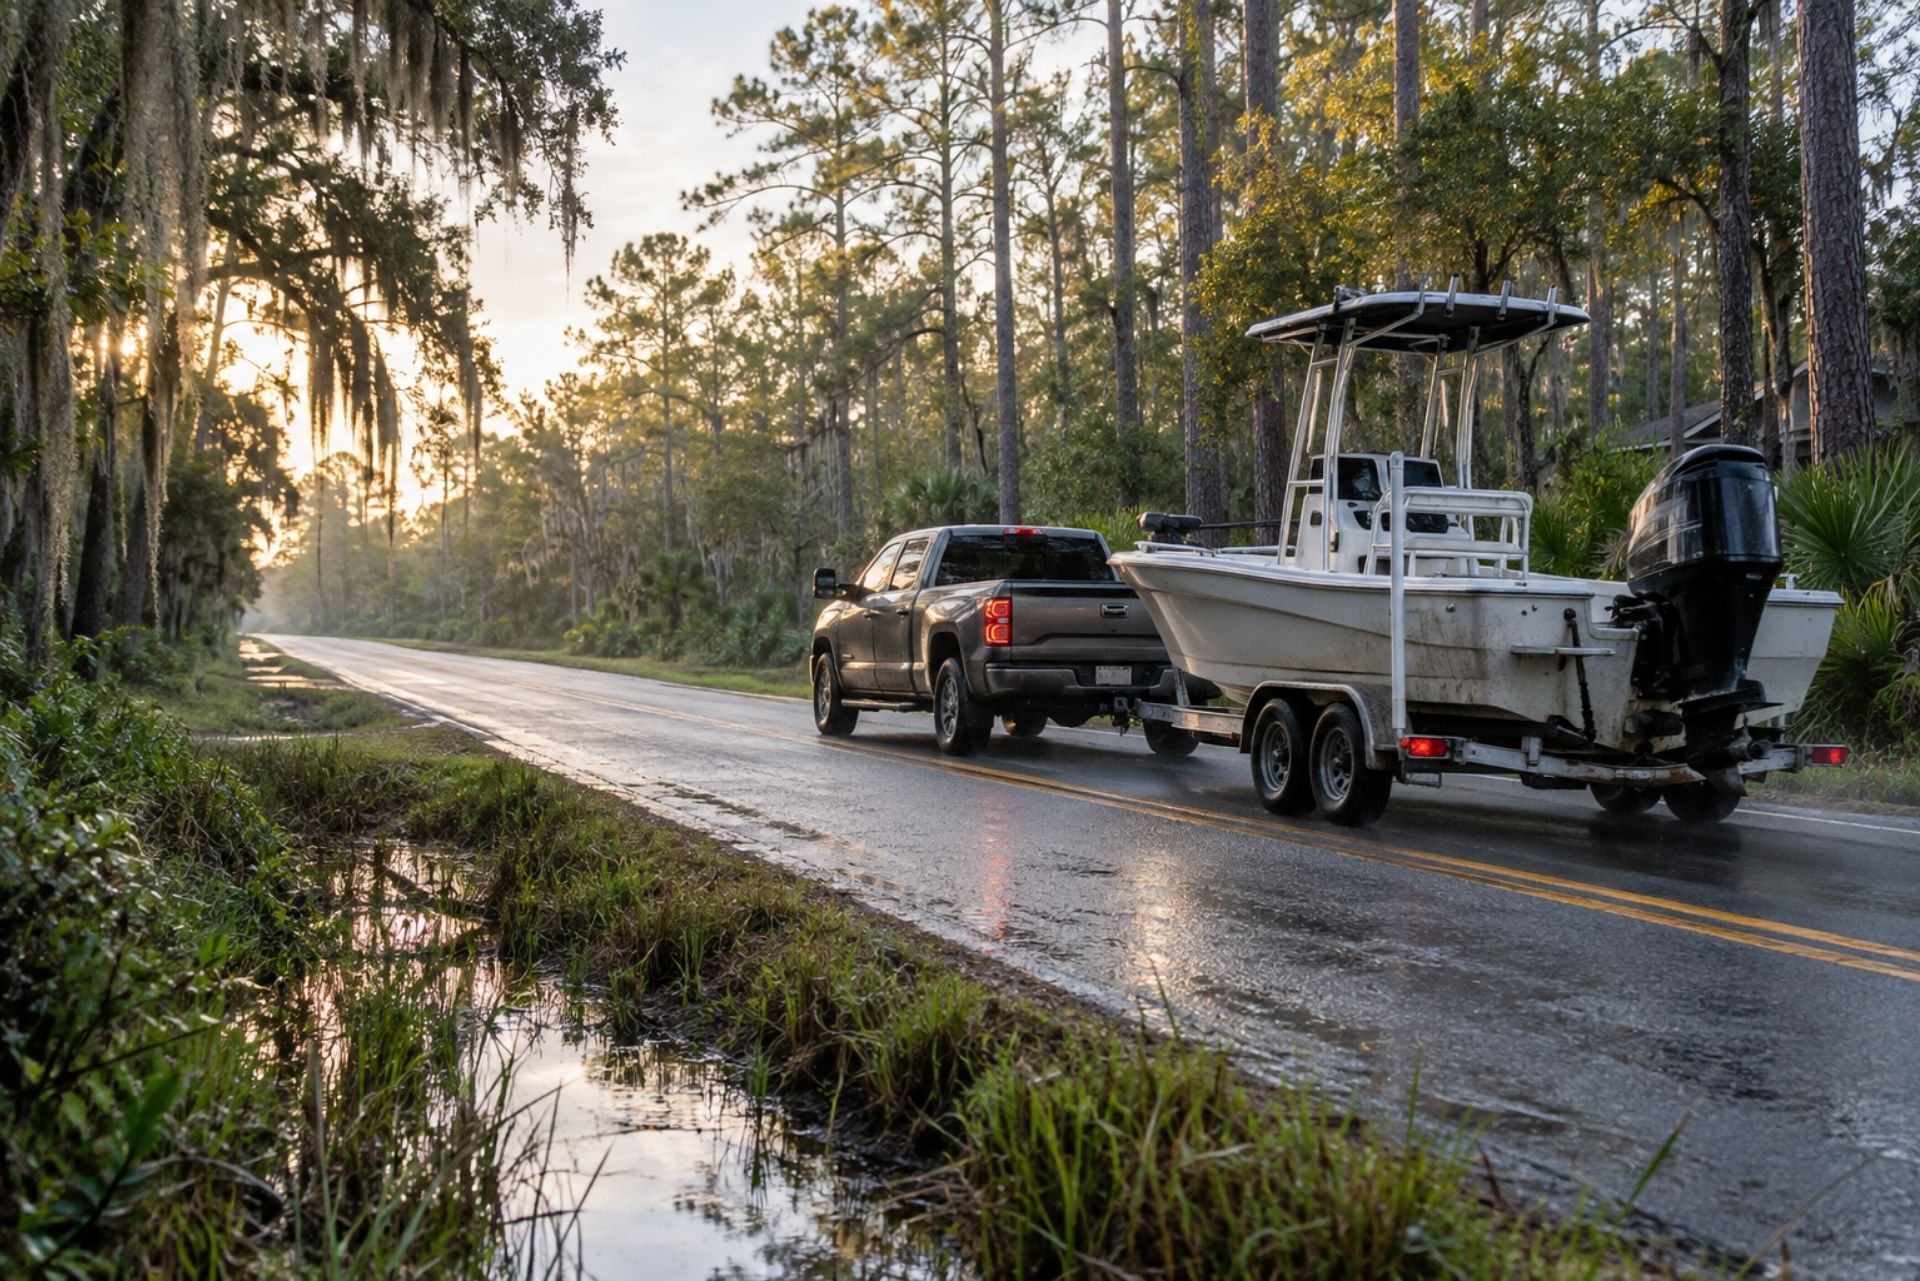
Weekend mornings in Lacombe look a lot like a boat launch parade. Bass boats, bay boats, jon boats, and utility trailers loaded with mowers or ATVs all head out behind full-size pickups. Towing changes your insurance picture in ways many owners don't realize until a claim is denied or comes up short.
Here's how coverage typically splits. Your auto policy's liability coverage usually extends to a trailer while it's attached to your insured vehicle. If the trailer swings into another lane and damages a car, your auto liability generally responds. Physical damage to the boat or trailer itself is a separate question, and many auto policies may not cover it unless the trailer is listed or you carry separate boat coverage.
Common mistakes we see:
- Assuming the boat is covered by the truck policy when it needs its own policy
- Forgetting to list a utility trailer, then finding out it isn't covered after it's stolen from the driveway
- Lending the truck and trailer to a friend without checking how the policy treats permissive use
- Adding expensive aftermarket equipment, like lift kits, trolling motors, or electronics, without updating coverage
A boat policy typically handles damage to the hull, motor, and gear, plus liability on the water. Your auto policy handles the road. You need both pieces lined up.
Liability Limits for Heavy Loads
A loaded truck and trailer can weigh several times more than a sedan. When that much weight is involved in a crash, damage and injuries escalate quickly. A trailer that jackknifes on I-12 can involve multiple vehicles in seconds.
That's why state minimum limits make little sense for anyone who tows. A $25,000 property damage limit may not cover even one late-model SUV, let alone a multi-car pileup. Many towing households consider limits of 100/300/100 or higher, and an umbrella policy may add another layer of protection above your auto and boat liability. Your agent can show you what higher limits actually cost compared to the risk you'd be absorbing.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.
One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.
| Feature | Commercial Property | Inland Marine (Tool Floater) |
|---|---|---|
| Where it applies | Your fixed shop location | Jobsites, truck, in transit |
| Typical items | Stationary machines, inventory, building | Portable saws, nailers, hand tools |
| Theft from vehicle | Usually not covered | Often covered, with conditions |
| Fire or storm at shop | Typically covered | May be covered if tools are there |
| Who needs it | Carpenters with a shop | Nearly every working carpenter |
How Deductible Types Compare
Comparison of NFIP vs. Excess Flood Coverage
| Feature | NFIP Policy | Excess Flood Policy |
|---|---|---|
| Building limit | Up to $250,000 | Typically adds coverage above $250,000 |
| Who issues it | Federal program, sold through agents | Private carriers |
| Waiting period | Generally 30 days | May be shorter, varies by carrier |
| Additional living expenses | Not included | May be included, depending on policy |
| Basement coverage | Very limited | May be broader on some policies |
| CRS premium credit | Applies in Mandeville | Typically does not apply |
| Best fit for | Base layer for most homes | Higher-value or lakefront homes |
Comparing Coverage Needs for Lacombe Drivers
The real choice for most Lacombe households comes down to two approaches. This table shows how they typically compare on the situations local drivers actually face.
| Situation | Basic Liability (15/30/25) | Full Coverage (Liability + Collision + Comprehensive) |
|---|---|---|
| You hit a deer on Highway 434 | Not covered | Comprehensive typically pays, minus deductible |
| You swerve and hit a tree | Not covered | Collision typically pays |
| You cause a crash on I-12 | Pays others up to limits | Pays others, plus repairs your vehicle |
| Tree limb falls in a storm | Not covered | Comprehensive typically pays |
| Truck stolen from driveway | Not covered | Comprehensive typically pays |
| Loan or lease requirement | Usually doesn't qualify | Usually satisfies lender |
| Protection above minimums | None | Limits can be raised |
Basic liability can make sense for an older, paid-off vehicle you could replace out of pocket. For most commuters with newer trucks, the animal strike risk alone makes comprehensive worth pricing. Your deductible choice matters as well. A $500 deductible versus a $1,000 deductible can change both your premium and how painful a deer season claim feels.
General liability covers physical harm: fires, shocks, and property damage from your work. Professional liability, sometimes called errors and omissions, may cover financial loss from design mistakes or bad advice, such as an undersized service you specified on a load calculation. Electricians who do design-build work, panel sizing for solar, or consulting often need both, because a general liability policy typically will not respond to a pure financial loss.
The most common mistake is buying limits sized for the center you opened, not the center you run now. Enrollment grows, a second van shows up, an after-school program starts, and the policy stays the same. A yearly review against your actual operations catches that drift before a claim exposes it.
General Liability vs. Workers Compensation
Frequently Asked Questions About Lacombe Auto Insurance
What's the minimum car insurance required in Lacombe, LA? Louisiana requires 15/30/25 liability coverage. That's $15,000 per person and $30,000 per accident for injuries, plus $25,000 for property damage.
Does car insurance cover hitting a deer? Typically yes, if you carry comprehensive coverage. Liability-only policies won't pay for damage to your own vehicle after an animal strike.
Is my boat covered when I tow it with my truck? Your auto liability may extend to damage the trailer causes to others while attached. Damage to the boat itself usually needs a separate boat policy.
What happens if I drive without insurance and someone hits me? Under Louisiana's 2025 reforms, you can't recover the first $100,000 in bodily injury or the first $100,000 in property damage, even if the other driver is at fault.
When is deer season worst for drivers in St. Tammany Parish? Peak risk runs from late September through late February, during the rut. Dawn and dusk are typically the highest-risk times.
Should I get more than the minimum liability limits? Most drivers benefit from higher limits, especially if you tow, commute on I-12, or own a home or other assets worth protecting.
The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.
One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.
| Feature | Commercial Property | Inland Marine (Tool Floater) |
|---|---|---|
| Where it applies | Your fixed shop location | Jobsites, truck, in transit |
| Typical items | Stationary machines, inventory, building | Portable saws, nailers, hand tools |
| Theft from vehicle | Usually not covered | Often covered, with conditions |
| Fire or storm at shop | Typically covered | May be covered if tools are there |
| Who needs it | Carpenters with a shop | Nearly every working carpenter |
Making the Right Choice for Your Policy
Lacombe driving packs a lot into a single policy: interstate commutes, two-lane rural roads, five months of heightened deer activity, and weekend towing. The state minimum covers almost none of that well. Comprehensive handles the animal strikes, higher liability limits protect you when a loaded trailer is involved, and a separate boat policy covers what your auto policy won't.
The 2025 reforms make continuous coverage and good documentation more important than ever. A lapse can wipe out your right to recover damages, and injury claims now require medical proof.
I'm Kyle Beerbohm, and at Aubert Insurance Agency we shop multiple carriers to match coverage to the way you actually drive. We have offices in Covington and Slidell, and we'll walk you through every line of your policy before you commit.
Ready to see your options? Start a Quote today, and we'll handle the comparison for you.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













