













Louisiana Painting Contractor Insurance

Covington & Slidell Independent Insurance Agents

Louisiana painting contractors typically carry General Liability for property damage and Workers' Comp for crew injuries. Many also add endorsements that address overspray and lead paint exposure. On the Northshore, one windy afternoon or one 1920s cottage can turn an ordinary job into a claim, so it pays to know where your policy starts and stops.


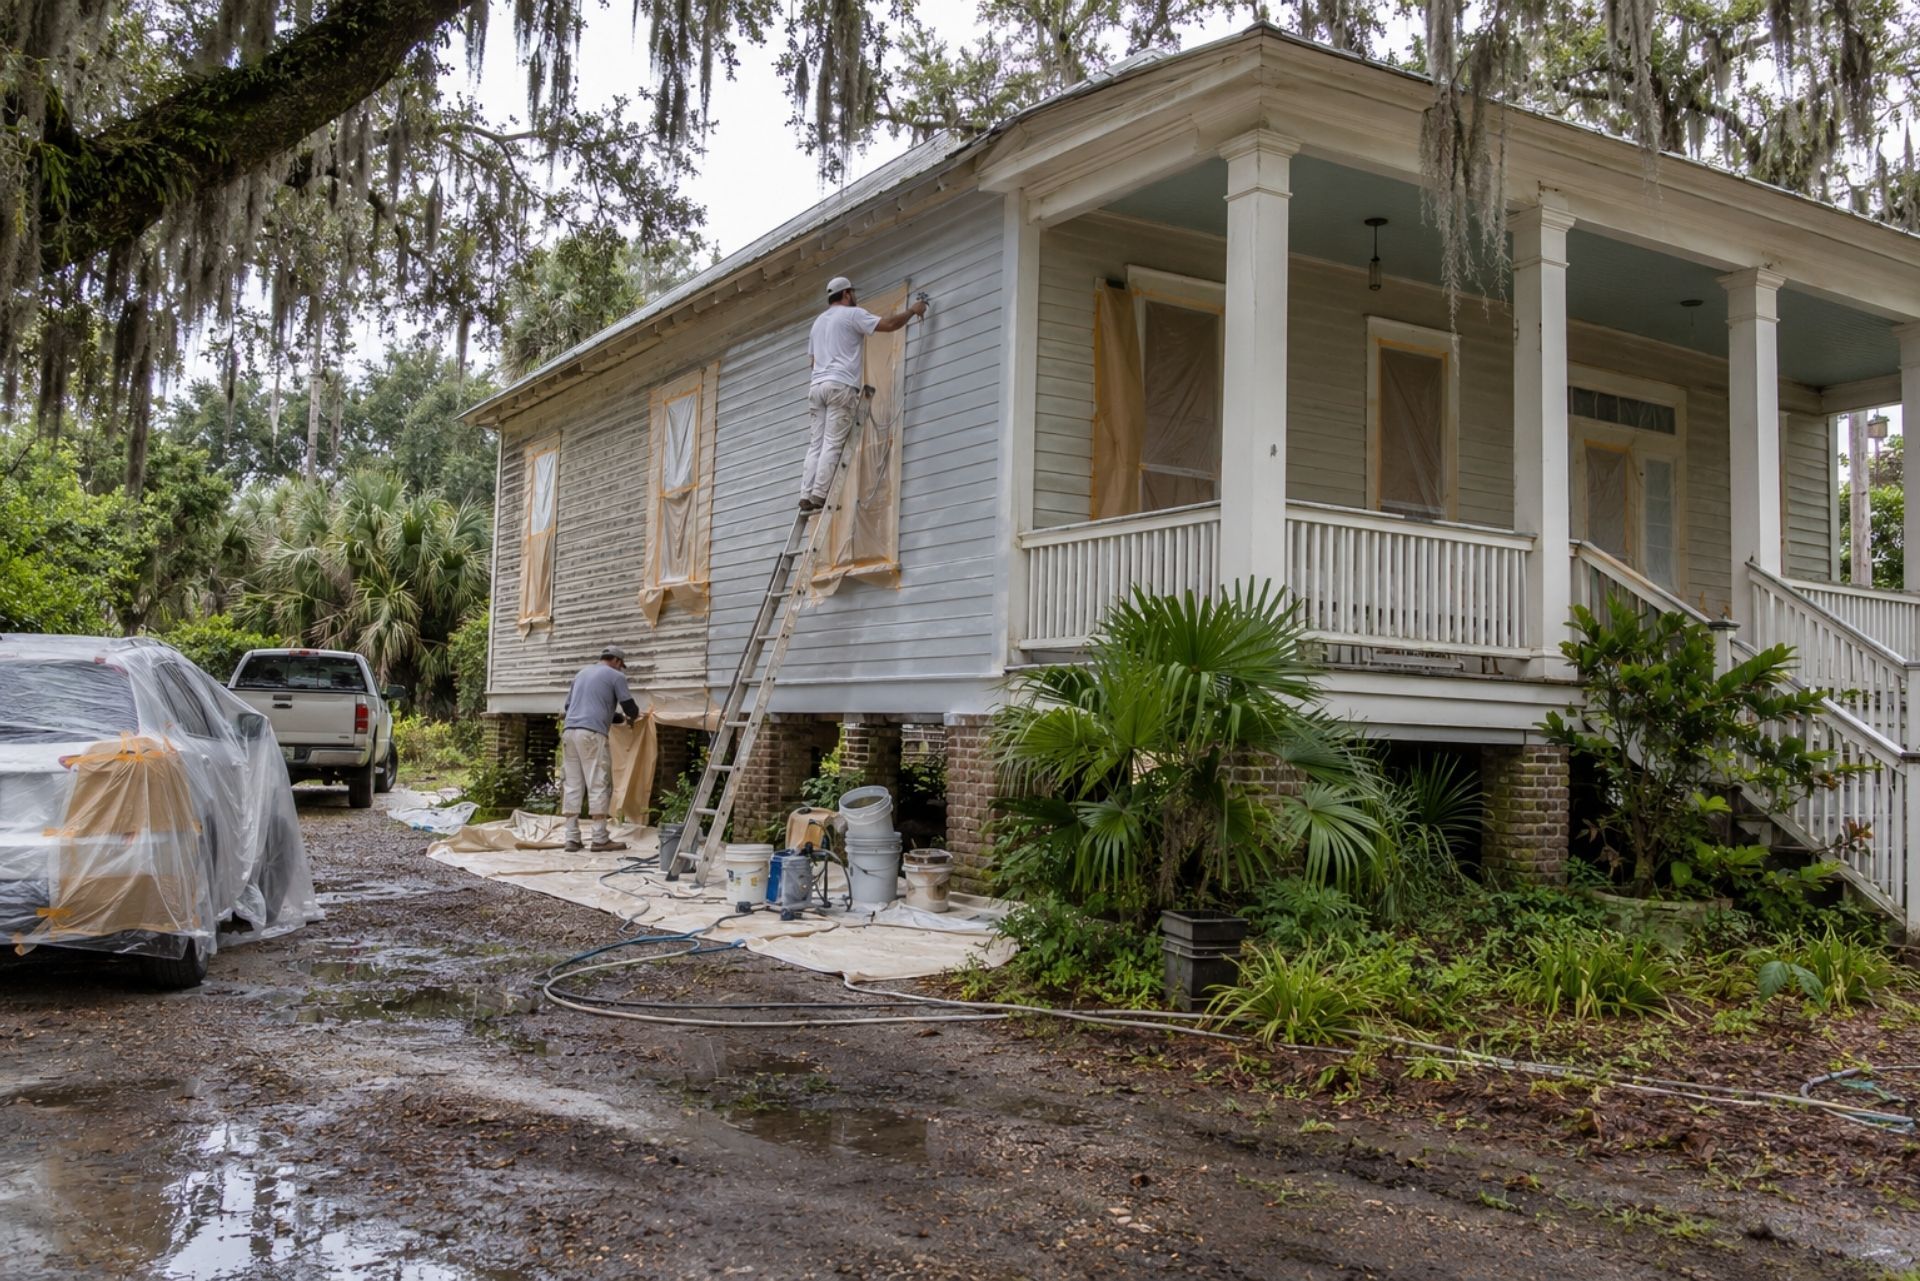
Picture a crew rolling the exterior of a raised Creole cottage off Columbia Street in Covington. A Gulf breeze kicks up around 2 p.m. By 4, the neighbor is pointing at a fine white mist across his black pickup. Down the block, a helper has stepped off a ladder rung and is holding his wrist. The homeowner mentions, almost in passing, that the house was built in 1925.


None of this is unusual for a working painter in St. Tammany Parish. It is just a Tuesday. Each of these moments tests a different part of your insurance program, though, and the gaps usually show up at the worst time: after a claim, or at year-end when the auditor asks for paperwork you never collected.

Louisiana Painting Contractor Insurance Requirements

Most Louisiana painters need three layers of protection. General Liability covers damage to other people's property. Workers' Compensation covers employee injuries. Endorsements fill specific gaps like overspray and lead disturbance. Aubert Insurance Agency has helped contractors in Covington and Slidell sort out these layers since 1910.


Workers' Comp is required under Louisiana law once you have employees. General Liability is not mandated statewide, but you will rarely land commercial work, property management contracts, or jobs for larger general contractors without a certificate showing it. Many homeowners now ask for one too.


Your painting class code matters. Contractors are typically rated under NCCI Code 5474 for painting work, and a misclassification can trigger a surprise bill at audit. If you also do drywall repair, pressure washing, or light carpentry, tell your agent so the right codes appear on the policy from day one.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Many St. Tammany families end up with both: standalone coverage for the land, plus an umbrella over the home and vehicles.

Comparison: Standalone Liability vs. Umbrella Coverage

Understanding the Named Storm Deductible

A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.


There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.

Factor Standalone Liability Umbrella Policy
Underlying policy required No Yes, home and auto typically
When it pays First dollar of a covered claim After underlying limits run out
Typical use Vacant land, hunting tracts, specific risks Broad extra protection across policies
Cost structure Priced by acreage, use, and limit Priced by number of homes, cars, drivers
Scope Narrow, tied to named property or risk Wide, follows underlying coverage
Common limits $300,000 to $1 million $1 million and up

People use the two terms as if they mean the same thing. They do not.


A true umbrella policy may provide broader coverage than the policies below it. In some cases it can "drop down" to cover a claim the primary policy excludes, usually subject to a self-insured retention, often $10,000 or $25,000. An excess policy is typically "follow form," which means it copies the terms and exclusions of the underlying policy and simply adds more limit.


Here is why that matters. If your general liability policy excludes a certain type of claim, a follow-form excess policy will generally exclude it as well. Higher limits do not repair a weak foundation. We go through the endorsements on each layer with clients before binding, because the wording on page 14 of the policy is what decides whether a claim gets paid.

Managing Risks of Overspray on Vehicles and Neighbors

Overspray claims are among the most common we hear about from painters, and Louisiana conditions make them more likely. Afternoon breezes off Lake Pontchartrain can carry atomized paint farther than most crews expect. Subdivisions in Slidell and Mandeville often have homes 15 or 20 feet apart, with cars parked in shared driveways or along the curb.


Airless sprayers are fast, but they put a lot of fine particles in the air. A light coat of latex on a neighbor's Tahoe, a boat under a carport, or vinyl siding next door can lead to a detailing bill or a full repaint demand. Specks on windows and patio furniture count too.


General Liability may cover these third-party property damage claims, subject to your policy terms and deductible. The key word is third-party. Damage to the client's own property you are actively working on can fall under a "your work" or "care, custody, or control" exclusion, depending on the carrier's wording.


A few habits keep claims down:


  • Check wind before you spray. Switch to rollers and brushes when gusts pick up.
  • Ask neighbors to move vehicles. A knock on the door costs nothing.
  • Use car covers and drop cloths generously. Cover anything within the spray zone, not just the house.
  • Photograph the area first. Pre-existing scratches and grime on nearby cars are easy to prove when you have dated photos.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

How Sublimits Affect Overtime and Minimum Wage Disputes

Homeowners with a mortgage

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Ladder and Lift Falls: Protecting Your Crew and Business

Falls are the injury that keeps painting contractors up at night. Your crew spends the day on extension ladders, walk boards, scaffolding, and rented boom lifts, often on uneven ground or wet grass after a morning shower. A two-story fall from a ladder on the back of a raised home can mean surgery, months off work, and a long recovery.


Workers' Compensation typically pays the injured employee's medical bills and a portion of lost wages while they recover. In most cases, it also protects you from being sued directly by that employee over the injury. Without it, you could be personally on the hook for hospital bills that quickly reach five or six figures.


A common mistake we see: owners who classify every helper as a "1099 guy" to skip Workers' Comp. Louisiana courts and auditors look at how the work actually happens, not what the paperwork says. If you supply the ladders, set the hours, and direct the work, that person may be treated as your employee.


Lift rentals deserve a quick note too. Rental agreements often push damage responsibility onto you, so ask whether your policy or an inland marine form covers rented equipment before signing.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Scenario Dwelling limit All-other-perils deductible Named-storm deductible
Newer build, inland St. Tammany $350,000 $1,000 2%
Newer build, higher wind zone $350,000 $1,000 5%
Older home, updated roof $275,000 $2,500 2%
Older home, original roof $275,000 $2,500 5%
Fortified roof designation $400,000 $1,000 2%
Rebuilt after a prior claim $400,000 $2,500 5%
Bundled with auto $350,000 $1,000 2%

Exact terms vary by carrier, so treat this as a starting point for comparing quotes.

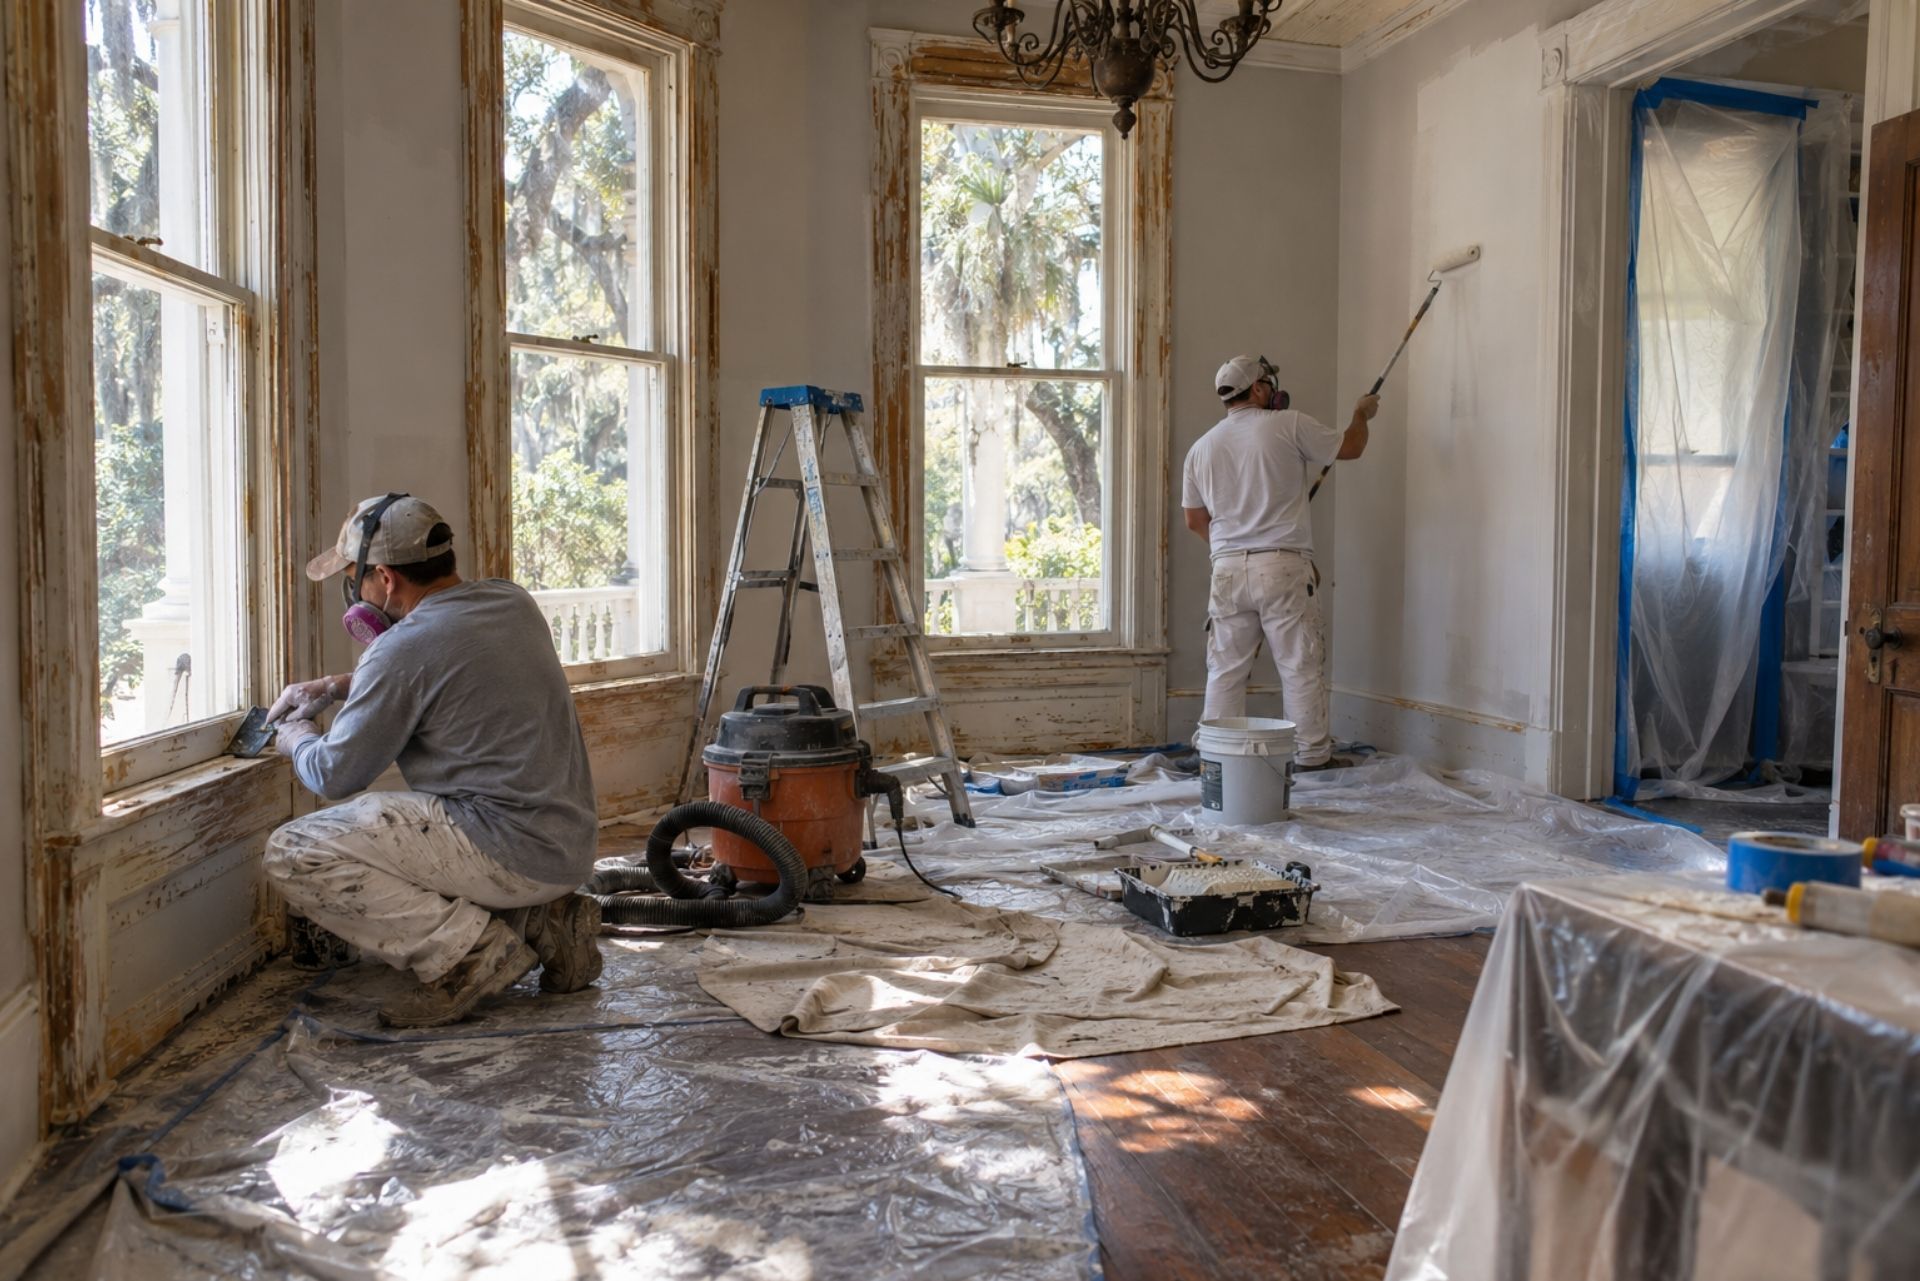
The Northshore is full of homes built before 1978, the year lead-based residential paint was banned. Old Covington neighborhoods, the historic district in Abita Springs, and plenty of older Slidell properties may still have lead layers under newer coats. Sanding, scraping, or heat-gunning that paint creates dust that can contaminate a home and the soil around it.


Federal EPA rules require firms doing renovation, repair, and painting work on pre-1978 homes and child-occupied facilities to be certified and to follow lead-safe practices. Skipping that step can bring regulatory penalties, and a family with a child who later tests high for lead may file a lawsuit years after you finish the job.


Here is the gap many painters miss. Standard General Liability policies usually contain a pollution exclusion, and lead dust may fall squarely inside it. A contractor's pollution liability policy, or a lead-specific endorsement, may provide coverage for cleanup costs and bodily injury claims tied to lead disturbance.


If you take on historic restoration work, ask your agent directly: "Would a lead claim be covered under what I have now?" Get the answer in writing.

Homeowners who own outright

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Bonding capacity is the total amount of work a surety will back, usually expressed as a single-job limit and an aggregate limit. A contractor might qualify for $500,000 on any one project and $1.5 million in total open work. Those numbers come from a careful review, not a formula pulled off a shelf.


The process has changed. Roughly 67% of surety carriers have digitized their processes as of 2026, and many use automated tools to issue smaller commercial bonds almost instantly. Larger contract bonds still get a human underwriter who digs into your file.


Underwriters in 2026 are also paying closer attention to mid-market contractors' project mix and labor management. They want to know whether you're taking on more than your crews can handle. A contractor who jumps from residential remodels to a municipal drainage job will face hard questions.

How Underwriters Set Bonding Capacity

Homeowners who own outright

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Workers' Comp and General Liability premiums are estimated at the start of your policy year, then trued up after it ends. That audit compares your actual payroll and subcontractor costs to what you estimated. Hiring an uninsured sub can cost you a lot at this stage.


If a subcontractor cannot prove they carried their own Workers' Comp and liability coverage, the auditor may treat what you paid them as your payroll. That means you pay premium for their exposure, often months after the job is done and the money is spent. Painters who lean on outside crews during busy seasons can see audit bills in the thousands.


The stakes went up in 2026. Effective August 1, Louisiana HB 185 expanded the manual labor exception to include employees of independent contractors. In plain terms, if your sub's workers are uninsured and one gets hurt, you as the principal contractor may owe their comp benefits.

The Impact of Subcontracted Crews at Audit

Workers' Comp and General Liability premiums are estimated at the start of your policy year, then trued up after it ends. That audit compares your actual payroll and subcontractor costs to what you estimated. Hiring an uninsured sub can cost you a lot at this stage.


If a subcontractor cannot prove they carried their own Workers' Comp and liability coverage, the auditor may treat what you paid them as your payroll. That means you pay premium for their exposure, often months after the job is done and the money is spent. Painters who lean on outside crews during busy seasons can see audit bills in the thousands.


The stakes went up in 2026. Effective August 1, Louisiana HB 185 expanded the manual labor exception to include employees of independent contractors. In plain terms, if your sub's workers are uninsured and one gets hurt, you as the principal contractor may owe their comp benefits.

Collecting Certificates of Insurance

A certificate of insurance (COI) is your proof at audit. Build a simple routine:


  1. Request COIs before the first day of work. Not after the invoice arrives.
  2. Confirm the dates. The policy should be active for the entire job.
  3. Check for Workers' Comp, not just GL. Many subs carry liability only.
  4. Ask to be named as additional insured on their liability policy when possible.
  5. Store certificates by job. A shared folder sorted by address makes audit day painless.


Sub-only crews who claim to have no employees may provide a workers' comp exemption or a ghost policy. Ask your agent how your carrier treats these before relying on one.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Comparing Essential Painting Coverage Options

Each policy answers a different "what if." This chart shows how they typically line up for a Louisiana painting business.

Coverage What It Typically Covers Example Claim Required?
General Liability Third-party injury and property damage Overspray on a neighbor's car Often required by contracts
Workers' Comp Employee medical bills and lost wages Helper falls from a ladder Required with employees
Pollution / Lead Endorsement Lead dust and contamination claims Child's lead exposure after scraping Strongly advised for pre-1978 work
Commercial Auto Work trucks and vans Crew van rear-ends another car Required for business vehicles
Inland Marine / Tools Sprayers, ladders, rented lifts Airless sprayer stolen from a trailer Optional
Umbrella Extra limits above GL and auto Large injury lawsuit exceeds GL limit Optional, sometimes required

Not every carrier words these the same way, and limits vary. That is where an independent agency helps: comparing several carriers side by side shows you who excludes what before you sign.

Common Questions About Painter Insurance in Louisiana

Do I need insurance for interior-only jobs? Yes. Interior painters still spill paint, damage furniture, and work on ladders. General Liability and Workers' Comp matter just as much indoors.


What happens if I spill paint on a client's wood floor? General Liability may cover it, but some policies exclude damage to property you are working on. Ask your agent how your policy handles client property inside the work area.


I'm a one-person operation. Do I still need Workers' Comp? Sole proprietors without employees may not be required to carry it. Many general contractors will still ask for coverage or an exemption before hiring you.


Will a single overspray claim raise my premium? It may. Carriers look at claim frequency and size at renewal, so smaller claims sometimes make sense to handle directly. Talk it through with your agent first.


How do I avoid a big bill at audit? Collect certificates from every sub, keep payroll records accurate, and make sure your class codes match the work you actually do.


Does my GL cover lead paint claims? Often it does not, because of the pollution exclusion. A separate pollution policy or lead endorsement is typically needed.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Your Next Steps for Professional Protection

Painting in St. Tammany Parish comes with its own mix of risks. Lake breezes push overspray onto neighbors' cars. Raised homes put your crew high on ladders. Pre-1978 houses hide lead under fresh coats, and a new state law makes uninsured subcontractors your problem. A policy that looks fine on paper can still leave a gap in any one of these areas.


The fix starts with a frank review. List the work you actually do, how many people you have on site, which subs you use, and how old your typical client's house is. Then match coverage to those facts instead of guessing.


Kyle Beerbohm and the team at Aubert Insurance Agency compare options from multiple carriers to fit your Louisiana painting business, and they explain the exclusions in plain language. Start a Quote today and head into your next audit knowing exactly where you stand.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
