













Covington & Slidell Independent Insurance Agents
A local independent agent may place a Louisiana home with Bankers Insurance Group when a property needs homeowners coverage, private flood insurance, or both from a single carrier. The agent checks the address, construction, roof age, and flood zone, then compares Bankers against admitted and surplus lines markets before you decide.
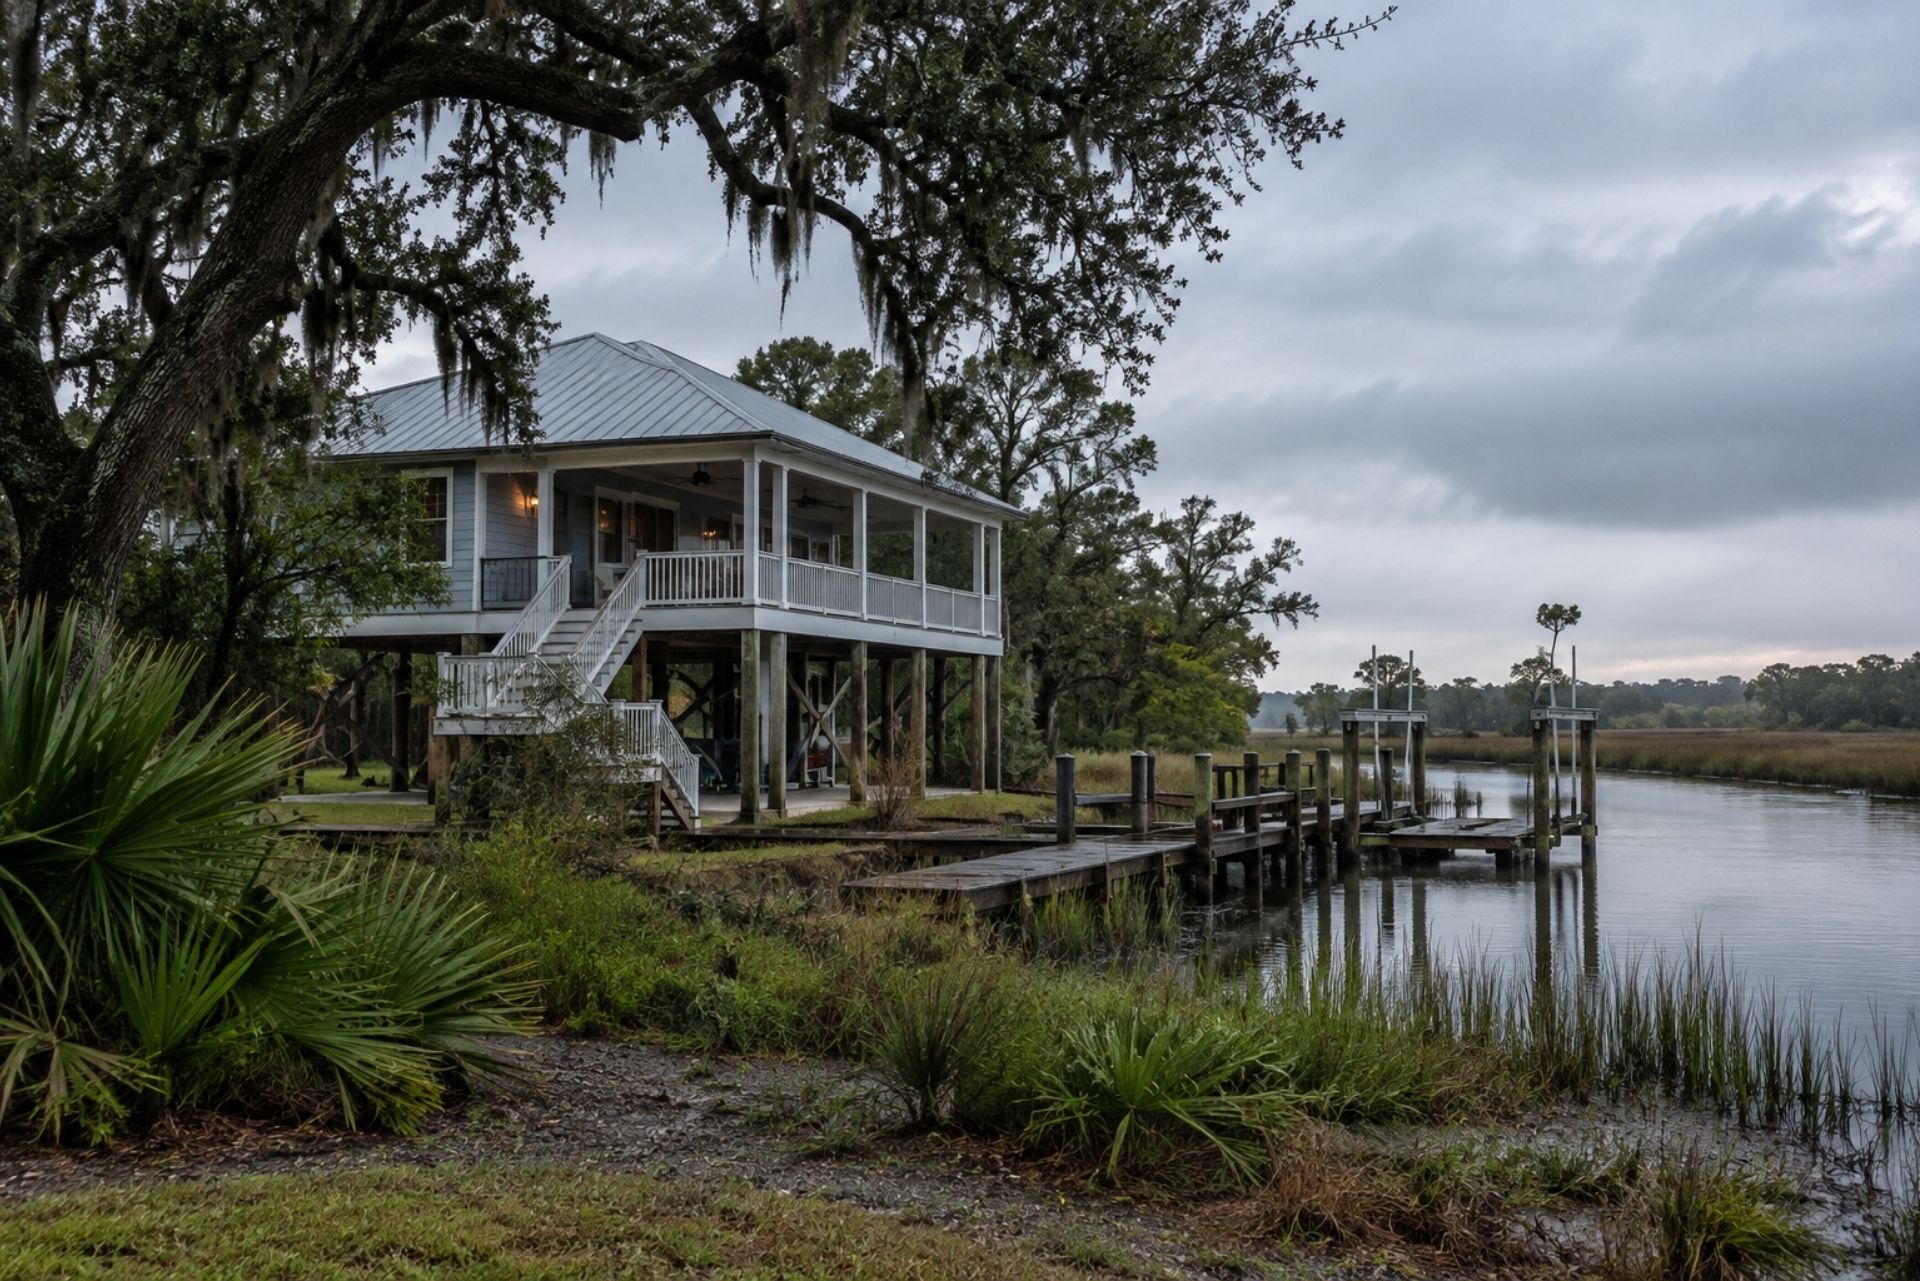
That's the short version. In practice, a quote for a brick ranch in Covington and one for a raised camp near Lake Pontchartrain in Slidell can look like they came from two different states. Underwriters see the same parish on the map, but they price wind, water, and roof condition very differently from street to street.
The good news is that the market feels steadier than it did a few years ago. The average homeowners rate change in Louisiana fell from a 14% increase in 2023 to just 0.1% in 2026. Stable doesn't mean affordable, though. It means you now have room to shop with a plan instead of taking whatever renewal shows up in your mailbox.
Understanding Home and Flood Options from Bankers Insurance Group
Bankers Insurance Group is one of the carriers that local Louisiana agents may turn to for property and flood protection. It typically shows up in two roles. The first is as a homeowners market for properties some national carriers have stepped back from. The second is as a flood option, either writing through the National Flood Insurance Program or offering private flood coverage.
Flood is where a lot of homeowners get surprised. Your standard homeowners policy typically excludes rising water entirely, which means a storm surge or a backed-up drainage canal isn't covered unless you carry a separate flood policy. Plenty of St. Tammany clients outside mapped high-risk zones assume they don't need it, and that assumption tends to hold right up until the first heavy rain event that overwhelms the ditches.
Here's what a Bankers flood option may include, depending on the policy form and property:
- NFIP-backed flood: Federal program coverage with set limits, including a $250,000 dwelling maximum
- Private flood: Coverage terms set by the carrier, which may offer different limits or additional living expense options
- Excess flood: Coverage that may sit on top of an NFIP policy for higher-value homes that exceed the federal dwelling limit
One timing detail catches people off guard. Private flood policies, including those from Bankers, typically carry a 30-day waiting period before coverage starts, with an exception during a property closing. If a named storm is already in the Gulf, it's too late to buy protection for that storm.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Coastal Eligibility for Louisiana Homeowners
Eligibility with any coastal-friendly carrier comes down to distance, elevation, and construction. Bankers doesn't publish a single statewide rule that applies to every home, and guidelines can change from one underwriting cycle to the next. So treat what follows as the factors that typically drive the decision, not a guaranteed checklist.
Distance to open water matters most for wind coverage. Homes closer to the coastline or to large bodies of water like Lake Pontchartrain may face tighter guidelines, higher hurricane deductibles, or a requirement that wind be written separately. A home in north Covington and one in the Eden Isle area of Slidell sit in the same parish but may land in very different rating territories.
Flood eligibility follows a different logic. Your flood zone, the elevation of your lowest floor, and whether you have an elevation certificate all shape what a carrier may offer. Raised homes with documented elevation often get more favorable treatment in private flood markets.
Underwriters also commonly look at:
- Roof age and material, with older shingle roofs drawing the most scrutiny
- Wind mitigation features such as hurricane straps, impact-rated openings, or a fortified roof
- Prior claims history on the property, not just on you
- Occupancy, since vacant or seasonal homes may be harder to place
Comparing Bankers Insurance Group vs. Standard Market Carriers
The table below shows how these options may differ. Specific terms vary by policy, so your agent should confirm each detail on an actual quote.
| Feature | Bankers Insurance Group | Standard Market Carriers |
|---|---|---|
| Coastal appetite | May accept homes closer to water | Often restrict near-coast properties |
| Hurricane deductible | Typically percentage-based, often 2% to 5% | Typically percentage-based, may be higher near coast |
| Flood integration | May offer NFIP and private flood | Usually refer flood elsewhere |
| Excess flood | May be available above NFIP limits | Rarely offered |
| Roof requirements | Varies by underwriting | Often strict on older roofs |
| Wind exclusion | Less common, depends on location | May exclude wind in coastal zones |
With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.
Homeowners who own outright
Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.
Homeowners with a mortgage
Accounting firms hold Social Security numbers, bank details, and tax records, which makes them prime targets. One industry observer put it bluntly: for most CPA firms, cyber insurance is no longer optional, and failing to meet MFA and EDR requirements can result in denied claims or total exclusion from the market. Translation: carriers now want multi-factor authentication and endpoint detection software in place before they will write you, and they may check after a claim. A cyber policy may cover breach notification, forensic investigation, ransomware response, and lawsuits from affected clients.
Cyber Liability
How an Independent Agency Weighs Bankers Against Other Markets
A captive agent can only show you one company's answer. An independent agency in Covington or Slidell can put several answers side by side and explain why they differ. That's the real advantage, and it matters more now that new competitors are arriving. Louisiana licensed three new homeowners carriers in early 2026: Progressive Paloverde, Continental Indemnity Company, and GuardianPointe Insurance Company.
At Aubert Insurance Agency, the evaluation typically follows a clear order:
- Gather the property facts first. Roof year, construction type, elevation certificate, prior claims, and any mitigation upgrades. Missing details lead to quotes that change after inspection.
- Run the admitted markets. Bankers, the newer entrants, and established regional carriers each get a look.
- Compare deductibles, not just premiums. A $300 lower annual premium may hide a hurricane deductible that costs you thousands more after a storm.
- Check the exclusions. Some forms limit roof coverage to actual cash value, which means depreciation comes out of your claim check.
- Pair home and flood thoughtfully. Sometimes one carrier for both simplifies claims. Sometimes splitting them saves money or gets better limits.
The comparison step is where most mistakes happen. We regularly see homeowners who switched carriers for a lower price without noticing they moved from replacement cost on the roof to actual cash value. On a 15-year-old roof, that difference can turn a covered loss into a large out-of-pocket bill.
Bankers may win on flood integration or coastal appetite. Another market might win on roof terms or price. The point is to see the trade-offs clearly before you sign a legally binding contract.

The roof
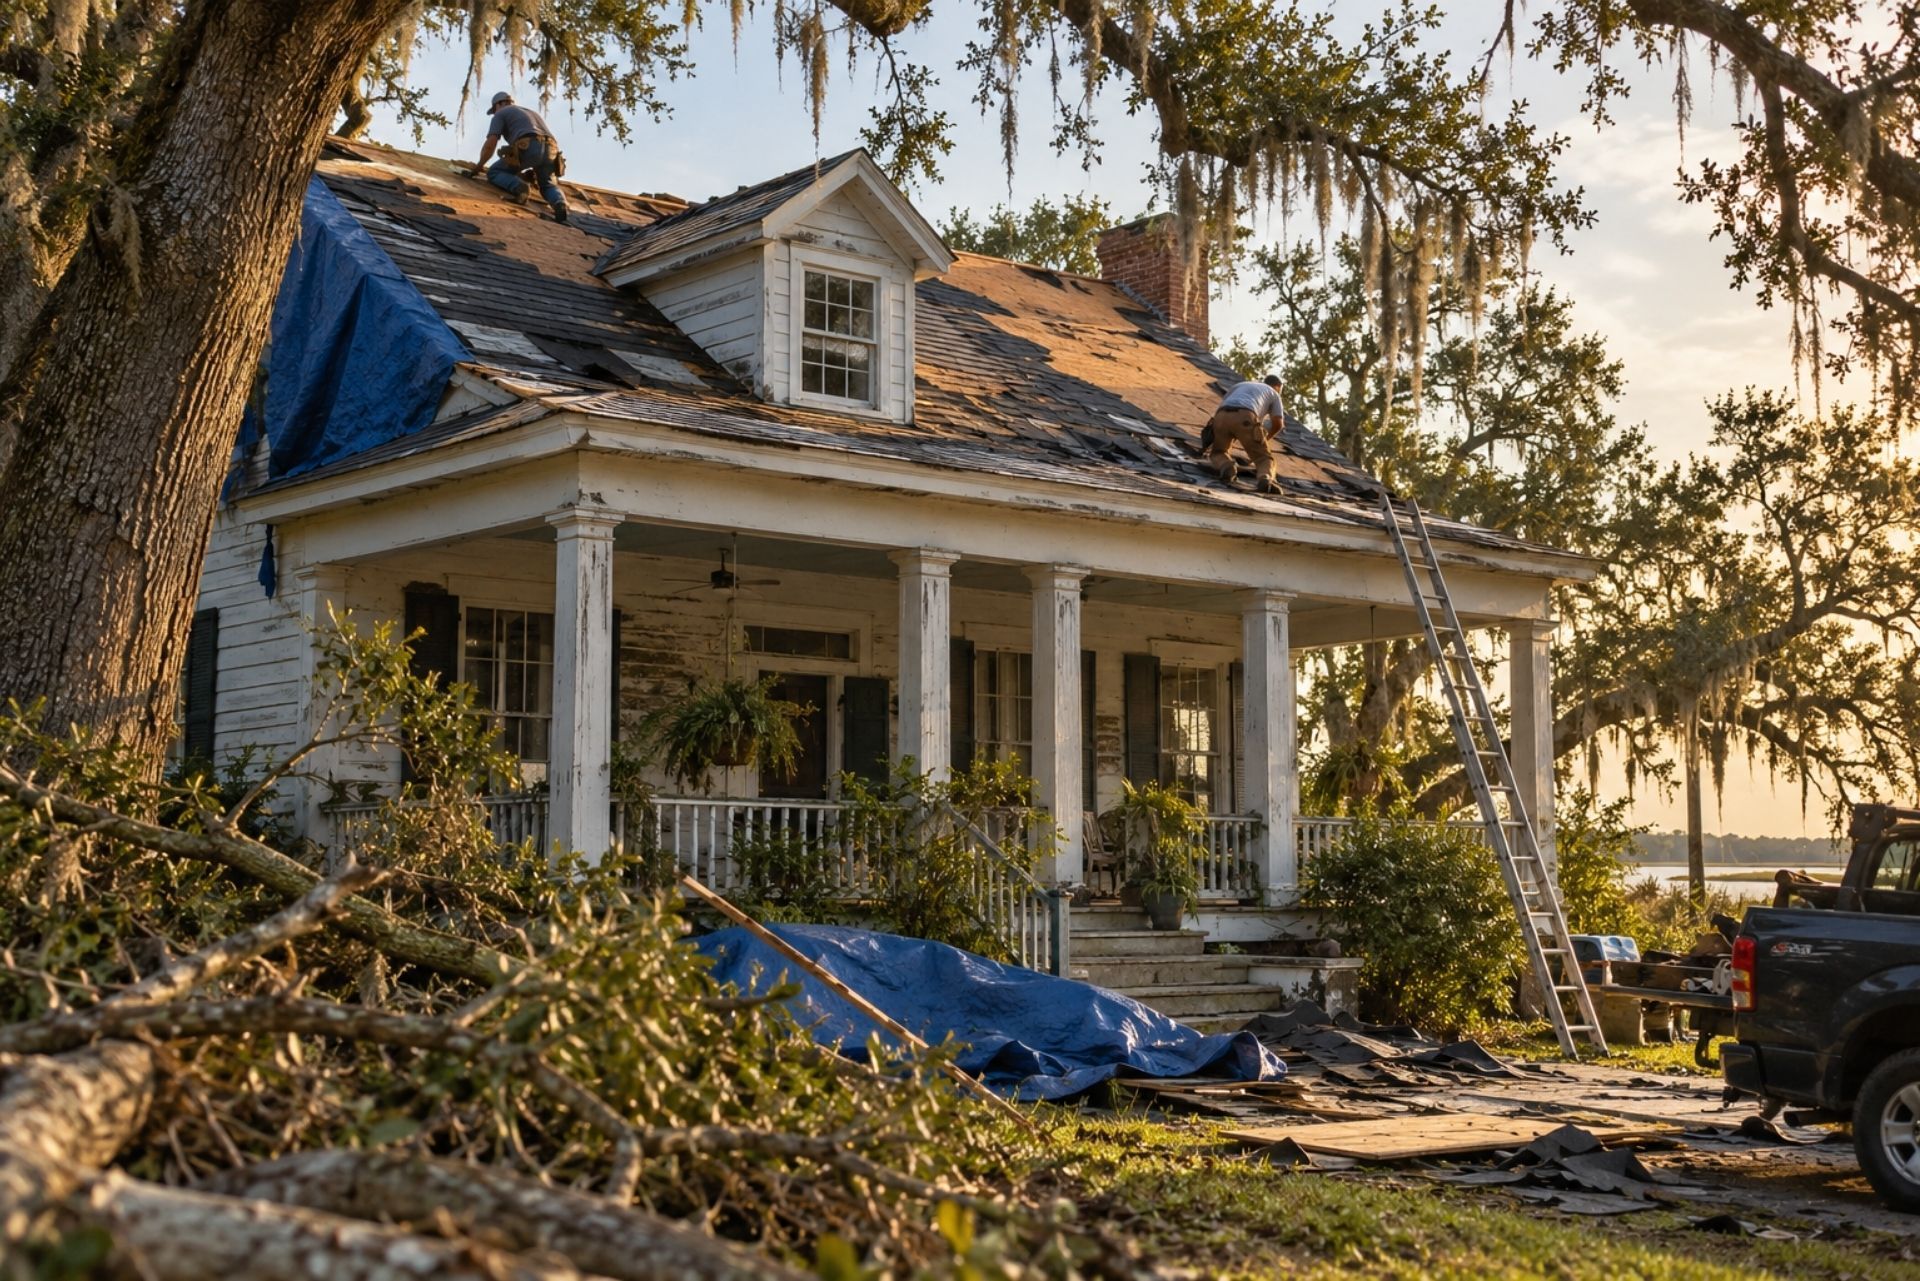
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
The Role of Excess and Surplus Lines in Coastal Coverage
Some homes simply don't fit admitted guidelines. That doesn't mean they're uninsurable. It means the agent may need to move to the excess and surplus lines market, where carriers have more freedom to set rates and terms for unusual risks.
Common reasons a Louisiana property ends up in surplus lines include a roof past a carrier's age cutoff, multiple recent claims, a home that sits very close to open water, or a high-value property that needs limits beyond what admitted carriers will write. Unique construction, like an older camp on pilings or a historic home with plaster walls, can also push a file in that direction.
The trade-off deserves a frank explanation. Surplus lines policies aren't backed by the Louisiana Insurance Guaranty Association the way admitted policies are, and forms may include more exclusions or higher deductibles. In exchange, you may get coverage that otherwise wouldn't exist outside the state's insurer of last resort.
A good agent treats surplus lines as a stepping stone, not a permanent home. If you replace the roof, add mitigation features, or go a few years without claims, your property may qualify for admitted markets again. We'd encourage anyone on a surplus lines policy to ask for a fresh market review at every renewal, especially with new carriers entering the state.
How Jones Act Exposure Differs From State Workers Comp
When Private Flood Is Worth Comparing
Common Questions About Louisiana Property Coverage
Do I really need flood insurance if I'm not in a high-risk zone? Many St. Tammany flood claims come from homes outside mapped high-risk areas, often from heavy rain and drainage overflow. If you can afford to replace your flooring, drywall, and furnishings out of pocket, you might skip it, but most families can't.
How much does flood insurance typically cost in Louisiana? The average annual NFIP premium in Louisiana is around $1,420 under Risk Rating 2.0, though your price depends on your specific home. Private flood quotes may come in lower or higher, so comparing both makes sense.
What's a hurricane deductible and how is it different? It's a separate deductible that applies to named storm damage, usually a percentage of your dwelling coverage instead of a flat dollar amount. On a $300,000 home with a 5% hurricane deductible, you'd pay the first $15,000 of a covered storm claim.
Can I buy flood insurance right before a storm? Generally no. Most flood policies typically carry a 30-day waiting period, except when the policy is tied to a home purchase closing.
Are insurance rates getting better in Louisiana? They've leveled off. One state official put it this way: "we've turned the curve... we're starting to come out of the trough," though premiums remain high compared to many states.
What if my home is valued above $250,000? NFIP caps dwelling coverage at $250,000. Private flood or excess flood coverage may fill the gap on higher-value homes.
The roof
Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.
| Feature | General Liability | Professional Liability (E&O) |
|---|---|---|
| What it covers | Physical injuries and property damage | Mistakes, oversights, bad advice |
| Example claim | Client slips in your lobby | Missed tax deadline costs a client penalties |
| Included in a BOP? | Usually yes | Usually no |
| Who needs it | Nearly every office with visitors | Accountants, consultants, agencies giving advice |
| Policy trigger | Usually occurrence-based | Usually claims-made |
Making the Right Choice for Your Louisiana Home
Coverage in this state rewards people who ask questions. Bankers Insurance Group may be a strong fit for a home that needs coastal appetite or flood paired with homeowners coverage, while a newer carrier or a regional market might handle another property more effectively. The only way to know is to compare real quotes with someone who reads the fine print alongside you.
Aubert Insurance Agency has been insuring what matters to St. Tammany families since 1910. That kind of history means we've watched carriers come and go, and we've learned which policy details hold up after a storm and which ones cause trouble at claim time. We'd rather spend an extra 20 minutes explaining your hurricane deductible today than have you discover it after a hurricane.
Our process is simple: you start online, we shop the markets for you, and you pick the plan that fits your home and budget. Ready to see where your property lands? Start a Quote with Kyle Beerbohm and get a clear, side-by-side look at your home and flood options.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Visit
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













