













Louisiana Real Estate Investor Insurance

Covington & Slidell Independent Insurance Agents

Louisiana investors can usually simplify their insurance by scheduling multiple rentals on one policy. The same review should also cover vacancy gaps, percentage-based named storm deductibles, and loss of rents. An independent agency serving Covington and Slidell can compare carriers and structure coverage that fits how your portfolio actually operates, from a single duplex to dozens of doors.


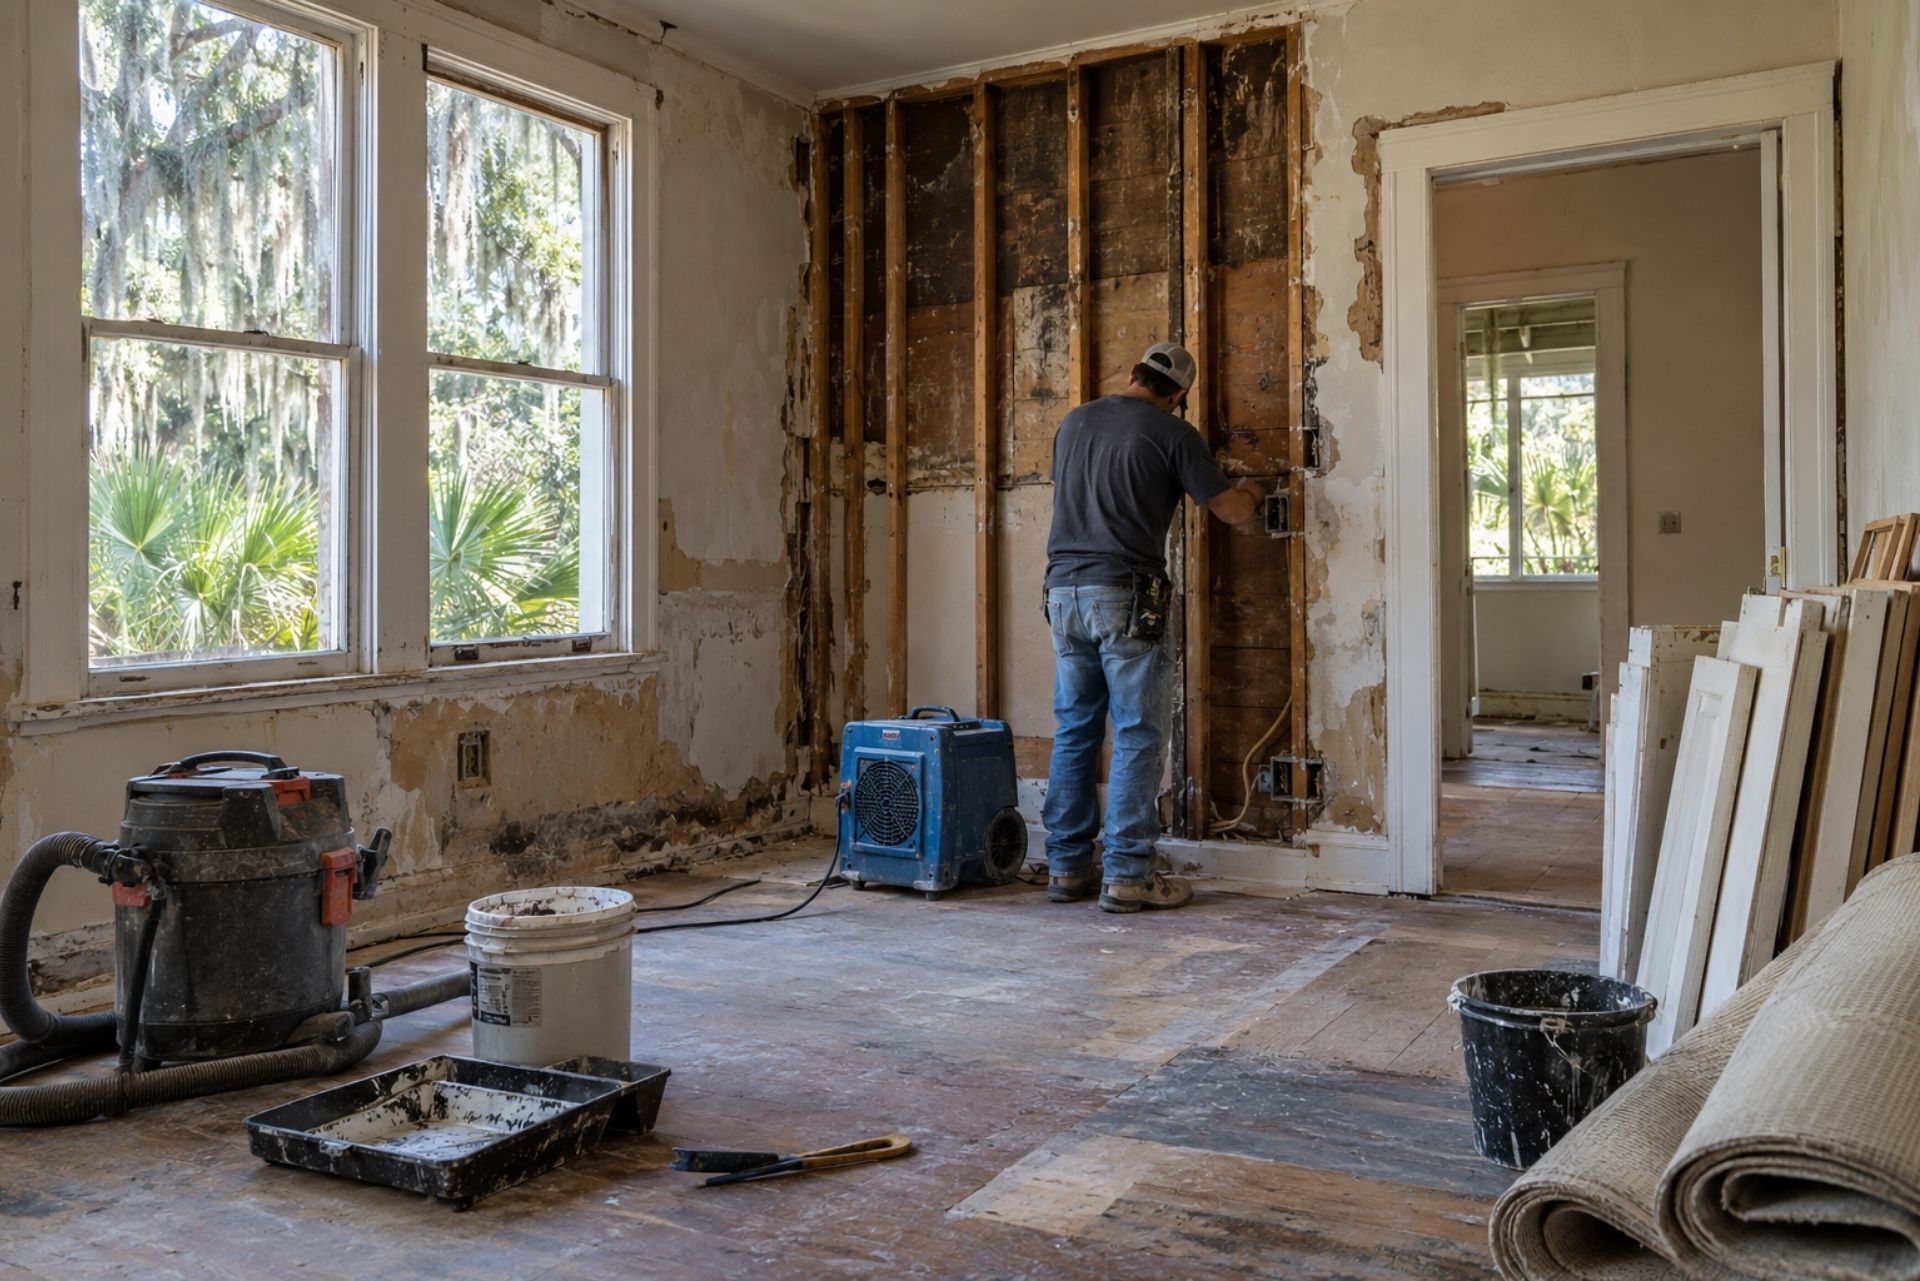
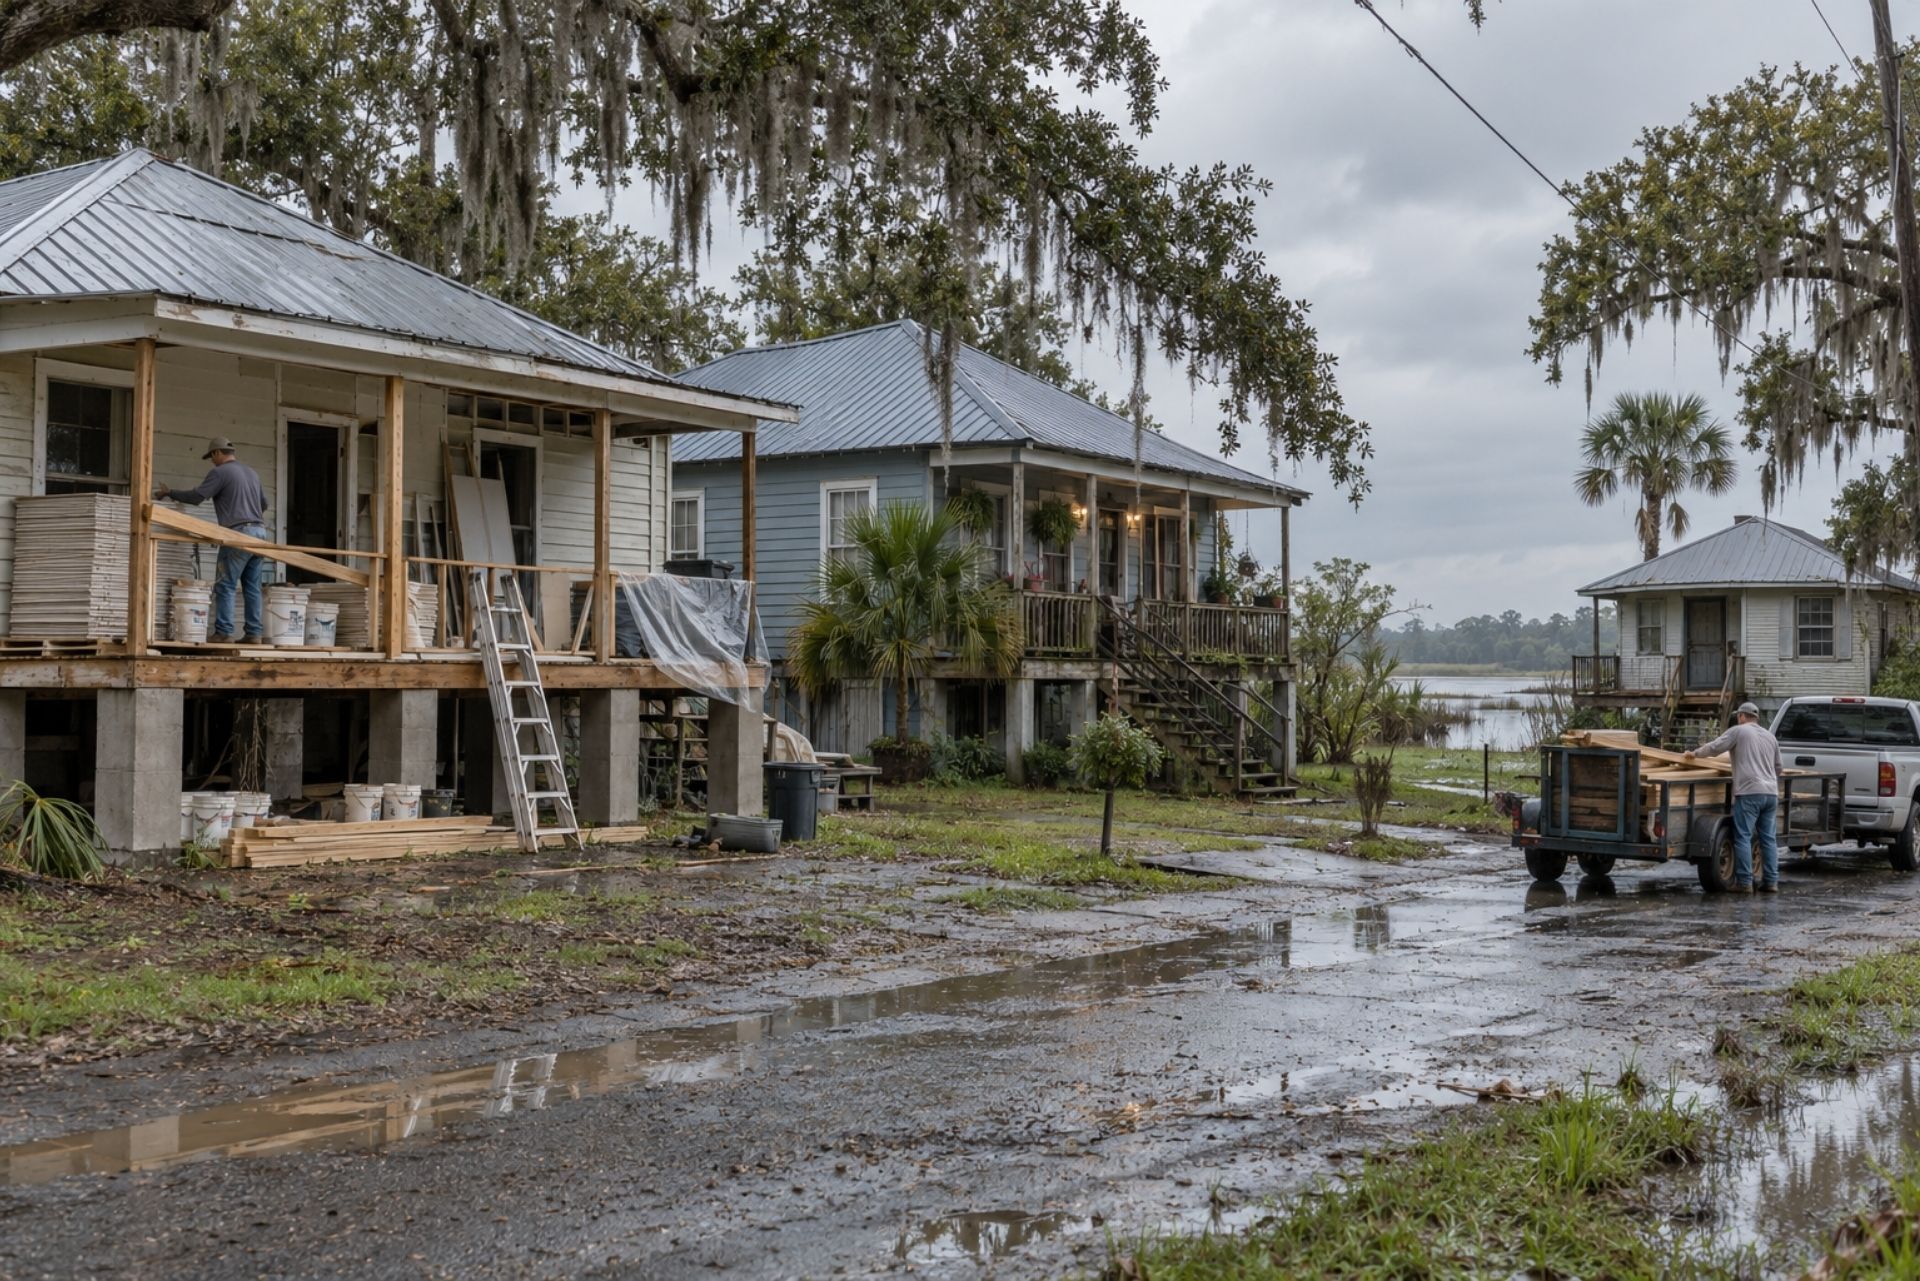
Picture an investor with six single-family rentals scattered between Slidell and Mandeville, plus a gutted shotgun house in Covington waiting on a contractor. That investor often has seven different policies with seven renewal dates, seven deductibles, and seven chances for something to slip through. Usually nobody notices until a storm rolls through or a tenant moves out and the house sits empty for two months.


The good news is that 2026 is a better year to fix that mess than any year in recent memory. Statewide homeowners rate changes averaged just 0.1% in 2026, down from 14% in 2023, and carriers are competing for business again. The real question is no longer whether you can find coverage. It is whether your coverage is built correctly.

Louisiana Real Estate Investor Insurance Essentials

Investor coverage in Louisiana is a different animal from the homeowners policy on your own house. A rental is typically insured under a dwelling fire form or a commercial property policy. Neither one automatically covers your tenants' belongings, and both may treat vacancy, storm damage, and lost income very differently than you'd expect.


The essentials break down into a few building blocks:


  • Property coverage for the structure itself, written on a Basic, Broad, or Special form
  • Premises liability in case a tenant or visitor is injured on the property
  • Loss of rents to replace income while a damaged unit is repaired
  • Wind and named storm terms, which in coastal parishes may carry their own deductible
  • Vacancy or builder's risk provisions for properties between tenants or under rehab


The state's market is opening up, too. More than 20 new insurers have been licensed to write property coverage in Louisiana since 2024, including seven in the first half of 2026. More carriers means more options for investor portfolios, which is exactly where an independent agency earns its keep.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Scheduling Rental Portfolios on One Policy

Once you own three or four rentals, separate policies start costing you time and money. A scheduled policy, sometimes called a master or blanket policy, lists each property on one contract with its own address, value, and coverage details. You get one renewal date, one bill, and one set of policy language to understand.


Consistency is the bigger benefit. When each property has its own policy, often from different carriers, you can end up with replacement cost on one house and actual cash value on another. The same can happen with $300,000 in liability on one property and $1 million on the next. A scheduled policy typically applies the same terms across every location, so you aren't guessing which house has which protection.


A few things to keep in mind when consolidating:


  • Each property still needs an accurate, current replacement value. Underinsuring one location can trigger coinsurance penalties on a claim.
  • Some carriers may require a minimum number of locations before offering a scheduled program.
  • Adding a newly purchased property mid-term is usually simple, but call before closing, not after.


Some carriers may offer a blanket limit that pools coverage across properties instead of fixing a limit per building. That can help when one house turns out to cost more to rebuild than expected, though blanket terms typically come with stricter valuation requirements.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Managing Vacant and Renovation Properties

This is where we see investors get hurt most often. Standard landlord and dwelling policies typically include a vacancy clause that restricts or eliminates coverage once a property sits unoccupied for 30 to 60 consecutive days. Depending on the policy wording, perils like vandalism, glass breakage, water damage, and theft may be excluded after that point. Some forms may also reduce any payout by a percentage.


Think about the flip you bought in Slidell in March. Closing takes a few weeks, permits take a few more, and your contractor gets pulled onto another job. By June, nobody has lived there for 75 days. If a pipe bursts or someone strips the copper, your regular policy may not respond at all.


Properties in this situation typically need one of two specialized forms:


  • Vacant dwelling policy: for homes that sit empty between tenants or before a sale, with no major construction underway.
  • Builder's risk or renovation policy: for properties under active rehab, covering the structure plus materials and work in progress.


Your contractor's coverage matters too. Effective August 1, 2026, Louisiana's Act 757 raised the minimum general liability requirement for residential contractors from $100,000 to $500,000. Ask for a current certificate before work starts, and make sure it reflects the new minimum.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Most Louisiana investors know their policies carry a separate deductible for named storms. Fewer realize that it is usually a percentage of the insured value rather than a flat dollar amount. A 5% named storm deductible on a rental insured for $250,000 means you pay the first $12,500 of a hurricane claim on that house.


On a scheduled portfolio, the math gets more involved. Percentage deductibles are often calculated per location, so a storm that damages four rentals could mean four separate deductibles. Check whether your deductible applies to each building's value, each location's value, or the total insured value, because the wording can swing your out-of-pocket cost dramatically.


Louisiana law provides an important protection here. Under La. R.S. 22:1267.1, commercial policies with a total insured value under $20 million must apply named storm deductibles annually rather than per storm. That means two hurricanes in one season shouldn't stack two full deductibles on you. Portfolios at $20 million or more in TIV are exempt from that rule, so larger investors may face per-event deductibles. That threshold is worth watching as your portfolio grows.


Before every June, run the numbers for a realistic storm that hits half your properties. If you can't comfortably cover those combined deductibles from reserves, talk with your agent about lower percentage options.

Covington & Slidell Independent Insurance Agents

Loss of Rents and Business Income Protection

Your mortgage doesn't pause because a kitchen fire forced your tenant out. Loss of rents coverage, sometimes called fair rental value or business income on commercial forms, typically replaces the rent you would have collected while a covered loss is repaired. The cause has to be a covered peril, such as fire, windstorm, or a burst pipe, and the unit has to be legitimately uninhabitable.


After a major hurricane, this coverage often matters more than the building repairs themselves. Contractors in St. Tammany Parish get booked for months after a big storm, and permitting slows down across the region. A roof repair that takes three weeks in a normal year might take five months after a direct hit. That's five months of payments with no income coming in.


Pay attention to how the coverage is limited. Some policies may cap loss of rents at a percentage of the dwelling limit, often in the 10% to 20% range, while others may pay for a set number of months. Many also include a waiting period of 72 hours or more before benefits begin. For rentals that make up most of your income, consider a longer period of restoration or an extended period of indemnity, which may continue paying for a time after repairs are done while you find a new tenant.

not, unless you're both named on the policy. Each roommate typically needs their own coverage, and shared policies can get messy when one person files a claim.


Will my renters insurance cover my dog biting someone? Many policies include pet liability under personal liability, but some carriers exclude certain breeds or cap dog bite claims. Tell your agent about your pet upfront so there's no surprise later.


Does my landlord's insurance cover my belongings? No. Your landlord's policy typically covers the building only, so your furniture, clothes and electronics need your own policy.


When should I buy flood insurance before hurricane season? Aim for spring. NFIP contents coverage generally has a 30-day waiting period, so buying in late May means protection by the heart of the season.


What should I do to prepare my rental for a hurricane? Take a video walkthrough of every room, save receipts for big items in the cloud and keep a copy of your policy on your phone. Good documentation is the single biggest factor in how fast a storm claim gets paid.


Will renters insurance pay for a hotel if we evacuate? It depends. Loss of use typically kicks in when your rental is uninhabitable from a covered loss or when a civil authority orders evacuation, but check your policy wording.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Coverage What It Covers Example Claim Required for License?
General Liability Injury to others, damage to client property Dust ruins a homeowner's sofa Yes, $500,000 minimum (residential)
Workers' Compensation Your employees' injuries and lost wages Taper falls from stilts Required if you have employees; proof needed for labor-only subs
Professional Liability Errors in advice or design Rarely relevant unless you design or consult No
Mold Buy-Back Limited mold claims, if offered Mold blamed on board you installed No, but often worth considering
Feature General Liability Garagekeepers Legal Liability Garagekeepers Direct Primary
What it protects Third-party injury and property damage from your operations Customer vehicles in your care Customer vehicles in your care
Fault required? Yes, you must be liable Yes, you must be negligent No, pays regardless of fault
Covers customer cars on your lot? Usually excluded Yes, if you're at fault Yes
Hail or flood to customer cars No Usually not (act of nature) Typically yes, if peril is covered
Customer relations N/A Customer may need to file with own insurer Shop handles claim directly
Relative cost Base cost Lower Higher

Comparison of Investor Coverage Options

Dwelling policies for rentals are typically written on one of three forms. The form determines which causes of loss are covered, and that choice affects your claim results more than almost any other decision.

Feature Basic Form (DP-1) Broad Form (DP-2) Special Form (DP-3)
How perils are covered Short named list Expanded named list All risks unless excluded
Fire, lightning, explosion Yes Yes Yes
Wind and hail Yes, with storm deductible Yes, with storm deductible Yes, with storm deductible
Burst pipes / water damage Typically no Typically yes Typically yes
Weight of ice, falling objects No Yes Yes
Typical settlement Actual cash value Often replacement cost Usually replacement cost
Loss of rents Optional or limited Often included Typically included
Who it fits Older or vacant property Mid-range rentals Most investor rentals

For a well-maintained rental with a reliable tenant, Special Form is usually worth the extra premium. Basic Form can make sense for older properties that may not qualify for replacement cost. In those cases, pair it with a careful review of what isn't covered.

Common Questions About Louisiana Investment Insurance

How does a named storm deductible work? It's a separate deductible, usually a percentage of the insured value, that applies only when damage comes from a named tropical storm or hurricane. On commercial policies under $20 million in total insured value, Louisiana law requires it to apply annually instead of per storm.


Can I insure my flip and my rentals together? Often yes, though the flip may need a vacancy or builder's risk endorsement while it's under renovation. Some carriers may let you schedule it on the same policy, while others write it separately.


Does my rental policy cover my tenant's furniture? No. Your policy covers your building and your liability, so tenants need their own renters insurance. Many investors require it in the lease.


How long can my rental sit empty before coverage changes? Many standard policies typically restrict coverage after 30 to 60 days of vacancy. Check your exact wording and call your agent before that deadline arrives.


Is now a good time to re-shop my portfolio? The state's insurance commissioner has said policyholders should shop around to take full advantage of rate decreases. With new carriers entering the market, a fresh comparison may turn up better terms.


Do I need flood insurance separately? Yes. Standard dwelling and commercial property policies exclude flood, so it must be purchased separately through the NFIP or a private flood carrier.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Your Next Steps for Portfolio Protection

A well-built investor program ties several pieces together. It schedules your rentals on one policy with consistent terms and keeps vacant or rehab properties properly covered. It sets named storm deductibles you can actually afford across every location and carries enough loss of rents to keep payments flowing while repairs drag on. Miss any one of those, and a single storm season can undo years of building equity.


Start with an honest inventory. List every property, its current carrier, its renewal date, its occupancy status, and its storm deductible in dollars, not percentages. Most investors are surprised by what that spreadsheet reveals.


Aubert Insurance Agency has helped Covington and Slidell property owners protect what they've built since 1910. As an independent agency, we compare options from multiple carriers and explain the policy language before you sign, so you know exactly where your coverage starts and stops. When you're ready to bring your Louisiana rental portfolio under one well-structured plan, Start a Quote with our team today.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
