













Louisiana Plumber Insurance

Covington & Slidell Independent Insurance Agents

Louisiana plumbers typically need general liability, workers compensation, and commercial auto coverage to protect against water damage claims, resulting mold, completed operations losses, and state licensing requirements. Aubert Insurance Agency, based in Covington and Slidell, has helped Louisiana contractors build that protection since 1910 by comparing options from multiple carriers.


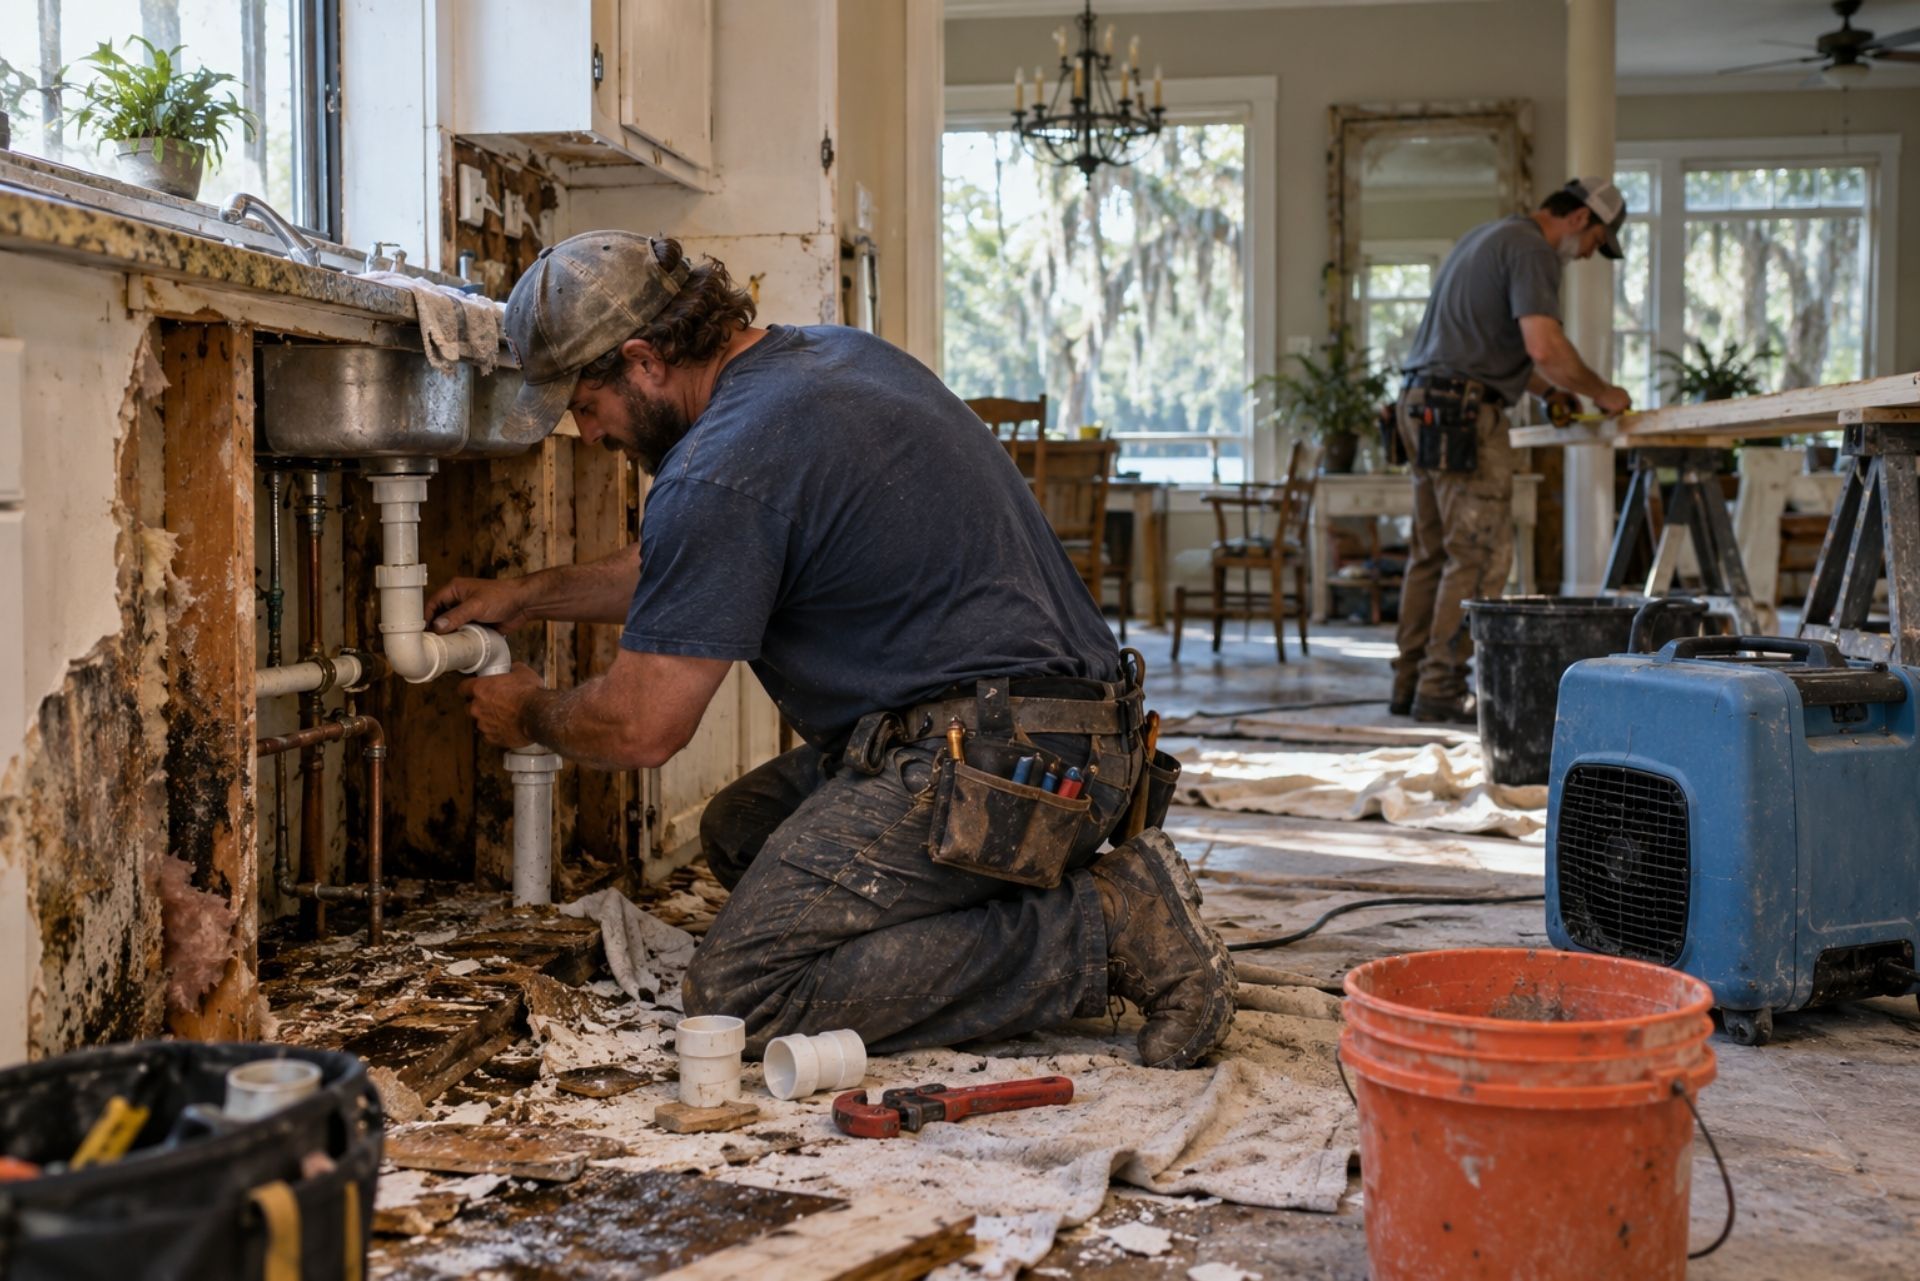
A supply line you replaced in a Mandeville kitchen two summers ago lets go on a Saturday night. By Monday, the subfloor is soaked, the cabinets are swelling, and the homeowner's adjuster is already asking who installed the fitting. That phone call is the reason plumbing insurance in Louisiana deserves more attention than a quick renewal signature.


Plumbers here work in a humid climate where a small leak can become a mold remediation job within days. They also drive vans through some of the most expensive commercial auto territory in the country. In 2026, they face a licensing system in the middle of a major overhaul.


The sections below walk through how licensing, water and mold exposure, completed operations, and vehicle risk fit together. Each one includes the coverage gaps that tend to surprise contractors when a claim actually lands. If you run a one-truck shop in Slidell or a crew of ten across St. Tammany Parish, the same pressure points apply.

Essential Insurance for Louisiana Plumbers

Most plumbing contractors start with three core policies, then add protection based on the type of work they do. Here is how the foundation typically breaks down:


  • General liability: Responds to third-party property damage and bodily injury, including damage that shows up after you leave a job.
  • Workers compensation: Covers medical bills and lost wages if an employee gets hurt, such as a back injury pulling a water heater out of an attic.
  • Commercial auto: Protects the vans and trucks your business owns or uses, along with the liability if one of your drivers causes a wreck.
  • Inland marine or tools and equipment: Covers pipe cameras, jetters, and power tools stolen from a job site or a parked van.
  • Umbrella liability: Adds limits above your general liability and auto policies for severe claims.


The mistake I see most often is a plumber who buys general liability alone because a general contractor asked for a certificate. That leaves the van, the crew, and the tools exposed. A policy built around your actual work, from new construction rough-ins to emergency service calls, tends to hold up far better when something goes wrong.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Louisiana State Plumbing Board Licensing Requirements

Licensing in Louisiana is changing fast, and plumbers should track it closely through 2026. Under recent legislation, the State Plumbing Board of Louisiana will be abolished effective January 1, 2027, with regulatory authority moving to the Louisiana State Licensing Board for Contractors. Act 908 also creates an 11-member Plumbing Contractors Subcommittee within the LSLBC to oversee trade regulations and continuing education.


Training standards shifted too. Apprentices now need 2,500 verified hours to sit for the journeyman exam, down from the previous 7,000 to 8,000 hours. Industry groups pushed back hard, with one trade association calling the changes "the most damaging rollback of plumbing licensure standards seen anywhere in the country."


Why does this matter for insurance? Underwriters look at experience. If you hire newer journeymen with fewer field hours, expect carriers to ask more questions about supervision, training, and the types of jobs those workers handle alone.

General Liability and Bond Standards

Insurance and bonding requirements tied to your license may be updated as authority shifts to the LSLBC, so confirm the current rules directly with the board before renewal. Beyond whatever the state requires, general contractors, property managers, and municipal projects in St. Tammany Parish frequently set their own minimum limits. Many commercial contracts ask for additional insured status, waivers of subrogation, and primary and noncontributory wording, which some policies may not include by default. Review contract requirements before you sign, not after the GC rejects your certificate.

Water Damage and Resulting Mold Claims

Water is the claim that defines this trade. A failed PEX crimp, an unglued PVC joint, or a water heater installed without a drain pan can cause thousands of dollars in damage before anyone notices. In Louisiana humidity, visible mold can follow within a couple of days, and remediation often costs more than drying out the water itself.


Here's what that means for you: many general liability forms contain a fungi or bacteria exclusion. Some carriers may give back limited coverage for mold that results from a covered water loss, while others exclude it completely. Two policies with the same liability limits can respond very differently to the same leak.


A few things to check on your current policy:


  • Whether a fungi or mold exclusion applies, and if any sublimit restores coverage
  • How the policy treats gradual leaks versus sudden failures
  • Whether your work itself is excluded while the resulting damage to other property is covered
  • Whether you would need a separate contractors pollution policy for mold exposure


That third point trips people up. Liability policies typically won't pay to redo your own faulty plumbing, but they may cover the drywall, flooring, and furniture it ruined. Knowing the difference before a claim keeps expectations realistic.

Completed Operations Years After the Job

Completed operations coverage is the part of general liability that responds after you've packed up and been paid. Plumbing failures rarely happen while you're standing there. A slab leak, a compression fitting that slowly loosens, or a backflow device installed incorrectly might not cause damage for months or even years.


The catch is that coverage generally follows the policy in force when the damage occurs, depending on the form. If you let your policy lapse, switch to a carrier with weaker completed operations terms, or retire without planning, a claim from a job finished years ago can land with nothing behind it. Some policies also carry a separate, lower aggregate for products and completed operations than for ongoing work.


Contractors who do new construction should pay special attention. Residential and commercial builds often come with long tails of exposure, and developers frequently require you to carry completed operations coverage for a set period after the project ends.


One thing to keep in mind: if you're closing or selling the business, ask about options for extended coverage. Old jobs don't stop being yours just because the company changes hands.

Managing Risk for Service Vans on the Road

Your van is a rolling shop full of copper, tools, and gas cans, and it spends hours on I-12 and Highway 190 every week. Louisiana's commercial auto market reflects that risk. Rates for clean fleets are rising 7% to 15% in 2026 because of repair inflation and litigation severity. Estimates put the annual cost to insure a plumbing service van in Louisiana between $2,200 and $3,800 per vehicle.


There is some relief available. Starting January 1, 2026, Louisiana insurers must offer premium reductions on the liability portion of commercial auto policies for vehicles equipped with working dashboard cameras and telematics systems. For a fleet of four or five vans, that can make the equipment worth the investment, and the footage helps defend against staged accidents.


Other steps that may help:


  • Run motor vehicle records before hiring any driver
  • Secure ladders and racks so nothing falls onto the roadway
  • Remember that personal auto policies typically exclude business use
  • Ask whether hired and non-owned auto coverage applies when employees drive their own trucks


Tools left in the van usually aren't covered by commercial auto, so pair it with inland marine coverage.

Comparing Coverage Needs for Plumbing Contractors

Not every plumbing business carries the same risk. A solo service plumber has a different profile than a crew roughing in new subdivisions. Use this table as a starting point for conversations with your agent.

Business Type Main Exposure Coverage Priorities
Solo service plumber Water damage from repairs General liability, commercial auto, tools coverage
Small residential crew Employee injuries, leaks Workers comp, GL with mold review, auto
Commercial and municipal work Contract requirements Bonds, additional insured endorsements, umbrella
Drain and sewer specialist Sewage backups, pollution Contractors pollution liability, equipment coverage

The right mix often depends on your contracts as much as your trade. A plumber who mainly does service work may grow into commercial jobs and suddenly face requirements the old policy can't meet. Reviewing coverage each year, especially before taking on a larger project, helps you avoid scrambling to meet a certificate deadline.

Common Questions About Louisiana Plumbing Insurance

Does my policy cover mold after a leak? It depends on your policy wording. Many general liability forms exclude mold, though some carriers may offer limited coverage when it results from a covered water loss.


What does the state board require for my license? Requirements may change as oversight moves from the State Plumbing Board to the LSLBC on January 1, 2027. Check directly with the licensing board for current insurance and bond rules.


Am I covered for a leak from a job I finished three years ago? Typically yes, if you have kept continuous general liability with completed operations coverage. A lapse in coverage can leave old jobs unprotected.


Do I need workers comp if I only have one helper? Louisiana generally requires workers comp for employees, and many general contractors will not hire you without it. A single injury can cost far more than the premium.


Can I use my personal truck policy for my plumbing business? Personal auto policies typically exclude business use, so a claim during a service call could be denied. Commercial auto is the safer route.


Will a dash cam lower my van insurance? Since January 1, 2026, Louisiana insurers must offer reduced premiums on the liability portion for commercial vehicles with working dash cams and telematics.

Making the Right Choice for Your Plumbing Business

Plumbing claims in Louisiana usually follow a pattern: a leak, a damp wall, a mold bill, and a question about whose policy pays. Add vans on busy highways, crews climbing into hot attics, and a licensing system in transition, and your coverage needs careful attention every year. The plumbers who come through claims in good shape are usually the ones who understood their exclusions before something broke.


As an independent agency, Aubert Insurance Agency compares coverage from multiple carriers and explains how each policy treats mold, completed operations, and vehicle use. Our process stays simple: start online, we shop for you, and you pick the plan that fits your business. If you work in Covington, Slidell, or anywhere across St. Tammany Parish, we can help you sort through your options.


Ready to see where your coverage stands? Start a Quote today and get protection that keeps working long after the job is done.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
