













Louisiana Landscaping Insurance

Covington & Slidell Independent Insurance Agents

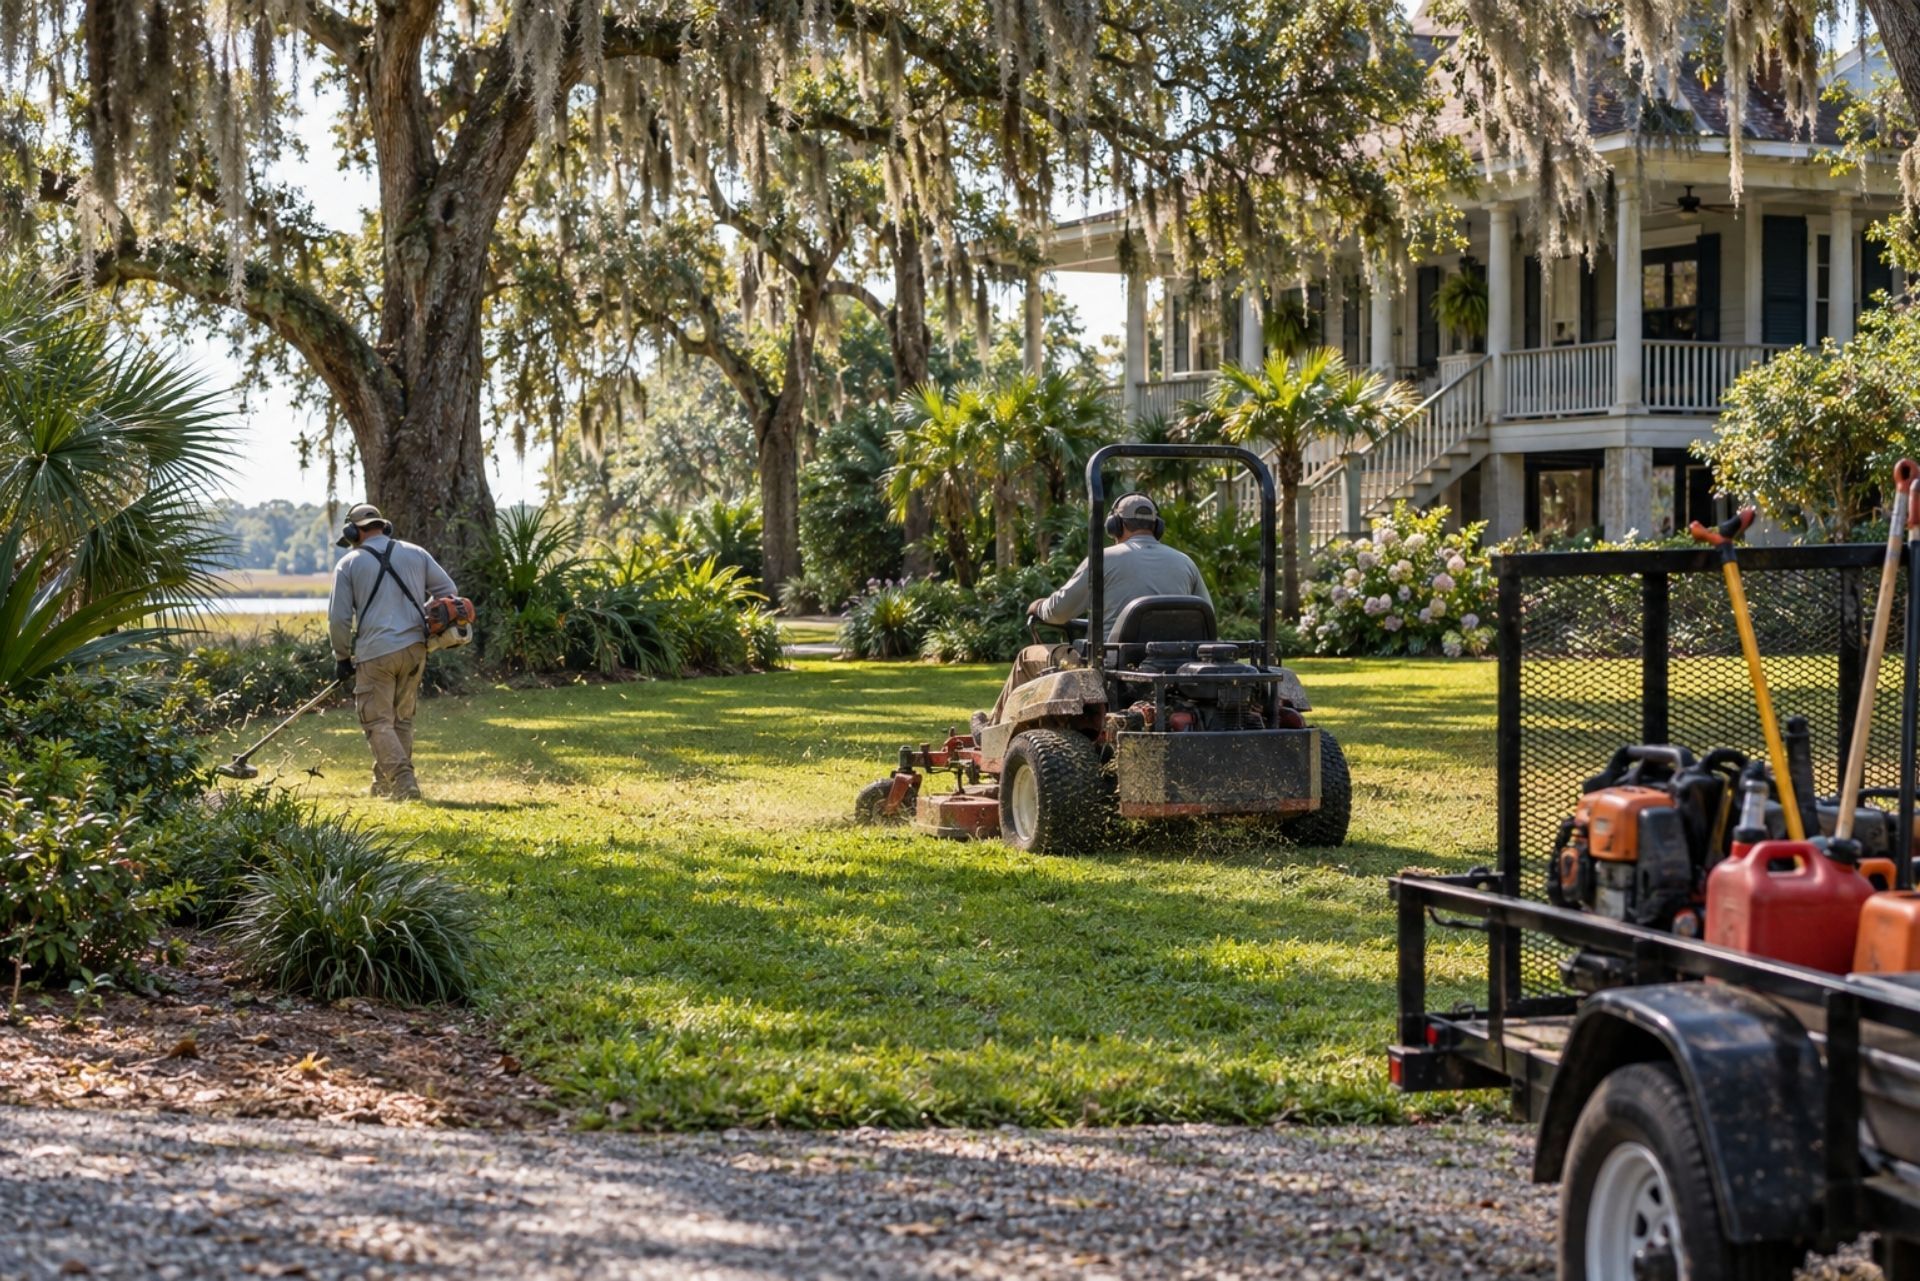
Louisiana landscaping insurance typically combines general liability, inland marine, and workers compensation to cover the risks local crews face daily, from a rock thrown through a client's window to a stolen zero-turn mower. Aubert Insurance Agency has helped businesses in Covington and Slidell protect what matters since 1910, shopping multiple carriers for fitting coverage.


A typical St. Tammany Parish landscaping job can go wrong in several ways at once. A string trimmer kicks up gravel near a parked SUV. A new hire tweaks his back loading pallets of sod. Someone cuts the lock on your trailer while you're at lunch on Highway 190. None of these are rare events, and each one hits a different part of your insurance program.


The trouble is that many lawn care owners buy a single general liability policy and assume they're covered for everything. They usually find out otherwise during a claim, which is the most expensive time to learn. What follows breaks down the four biggest exposures for Louisiana landscapers: flying debris, chemical application, equipment theft, and seasonal labor. You'll see where each policy type fits and where the gaps tend to hide.

Protecting Your Louisiana Landscaping Business

Think of your coverage as three separate tools, each built for a specific job. General liability handles damage you cause to other people and their property. Inland marine protects the equipment you own and haul around. Workers compensation covers your employees when they get hurt on the clock.


Cost matters, so here's a realistic reference point. As of September 2026, the median annual cost for landscaping insurance in Louisiana runs about $610 for General Liability, $2,029 for Workers' Comp, and $2,452 for Commercial Auto. Your own premium will depend on payroll, the services you offer, your claims history, and how much equipment you're insuring.


That commercial auto figure deserves attention. Your trucks pulling trailers through Slidell traffic often carry the largest premium on the books, and a personal auto policy typically won't respond to business use. If you're running a crew out of a personal pickup, that's a conversation worth having before the next renewal.


The goal is building a program where these policies work together without overlapping or leaving holes. An independent agency can compare how different carriers package these coverages, since forms and exclusions vary more than most owners expect.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Understanding the Named Storm Deductible

A named storm deductible works differently than the flat $500 or $1,000 deductible on your regular claims. In Louisiana, it's often calculated as 2% to 5% of the insured value of your personal property. On a policy with $40,000 in contents coverage, a 5% deductible means the first $2,000 of a hurricane loss is yours.


There's some good news in state law. Louisiana's one-deductible-per-year rule (La. R.S. 22:1337) means you generally pay the named storm deductible only once per calendar year, even if two storms hit your rental. Ask your agent to show you that deductible in dollars, not just a percentage, so you can set aside the right amount in an emergency fund.

Mower-Thrown Debris and Property Damage Risks

Flying debris is the claim landscapers file most often. A blade catches a pine cone, a chunk of oyster shell from a driveway edge, or a forgotten dog toy, and suddenly there's a spiderweb crack across a Tahoe's rear window.


Here's the good news: damage from a mower-flung object, like a rock shattering a car window, is generally treated as the operator's responsibility and falls under standard general liability as third-party property damage. That's exactly what the policy is built for.


The catch is timing and documentation. Louisiana property damage lawsuits, called delictual actions, must be filed within two years from the day the damage occurs. A homeowner who notices a cracked sliding door weeks later may still come after you, and without records you'll struggle to dispute it.


A few habits reduce both claims and arguments:


  • Walk the property first: Have crews do a 60-second scan for rocks, sticks, and debris before mowing.
  • Use discharge chutes and deflectors: Never remove them to speed up a job.
  • Photograph before and after: Time-stamped photos of windows and vehicles can settle disputes quickly.
  • Report incidents immediately: Small claims get messier when they're reported late.


Also check your deductible. Some owners pay small window claims out of pocket to protect their loss history, which can be a smart move.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Being named as a certificate holder just means someone receives proof. Being named as an additional insured means your policy may actually defend and pay for that party if they're sued because of your work. General contractors, developers, and property managers ask for this because they get pulled into lawsuits over subcontractor mistakes constantly.


Read the contract language closely. Some agreements require "primary and noncontributory" wording or completed operations coverage for the additional insured, which needs specific endorsements. Many contractors sign a subcontract agreeing to these terms without checking whether their policy includes them. If a claim comes in and the endorsement isn't there, you may be in breach of contract on top of facing the lawsuit.

Herbicide and Pesticide Applicator Rules in Louisiana

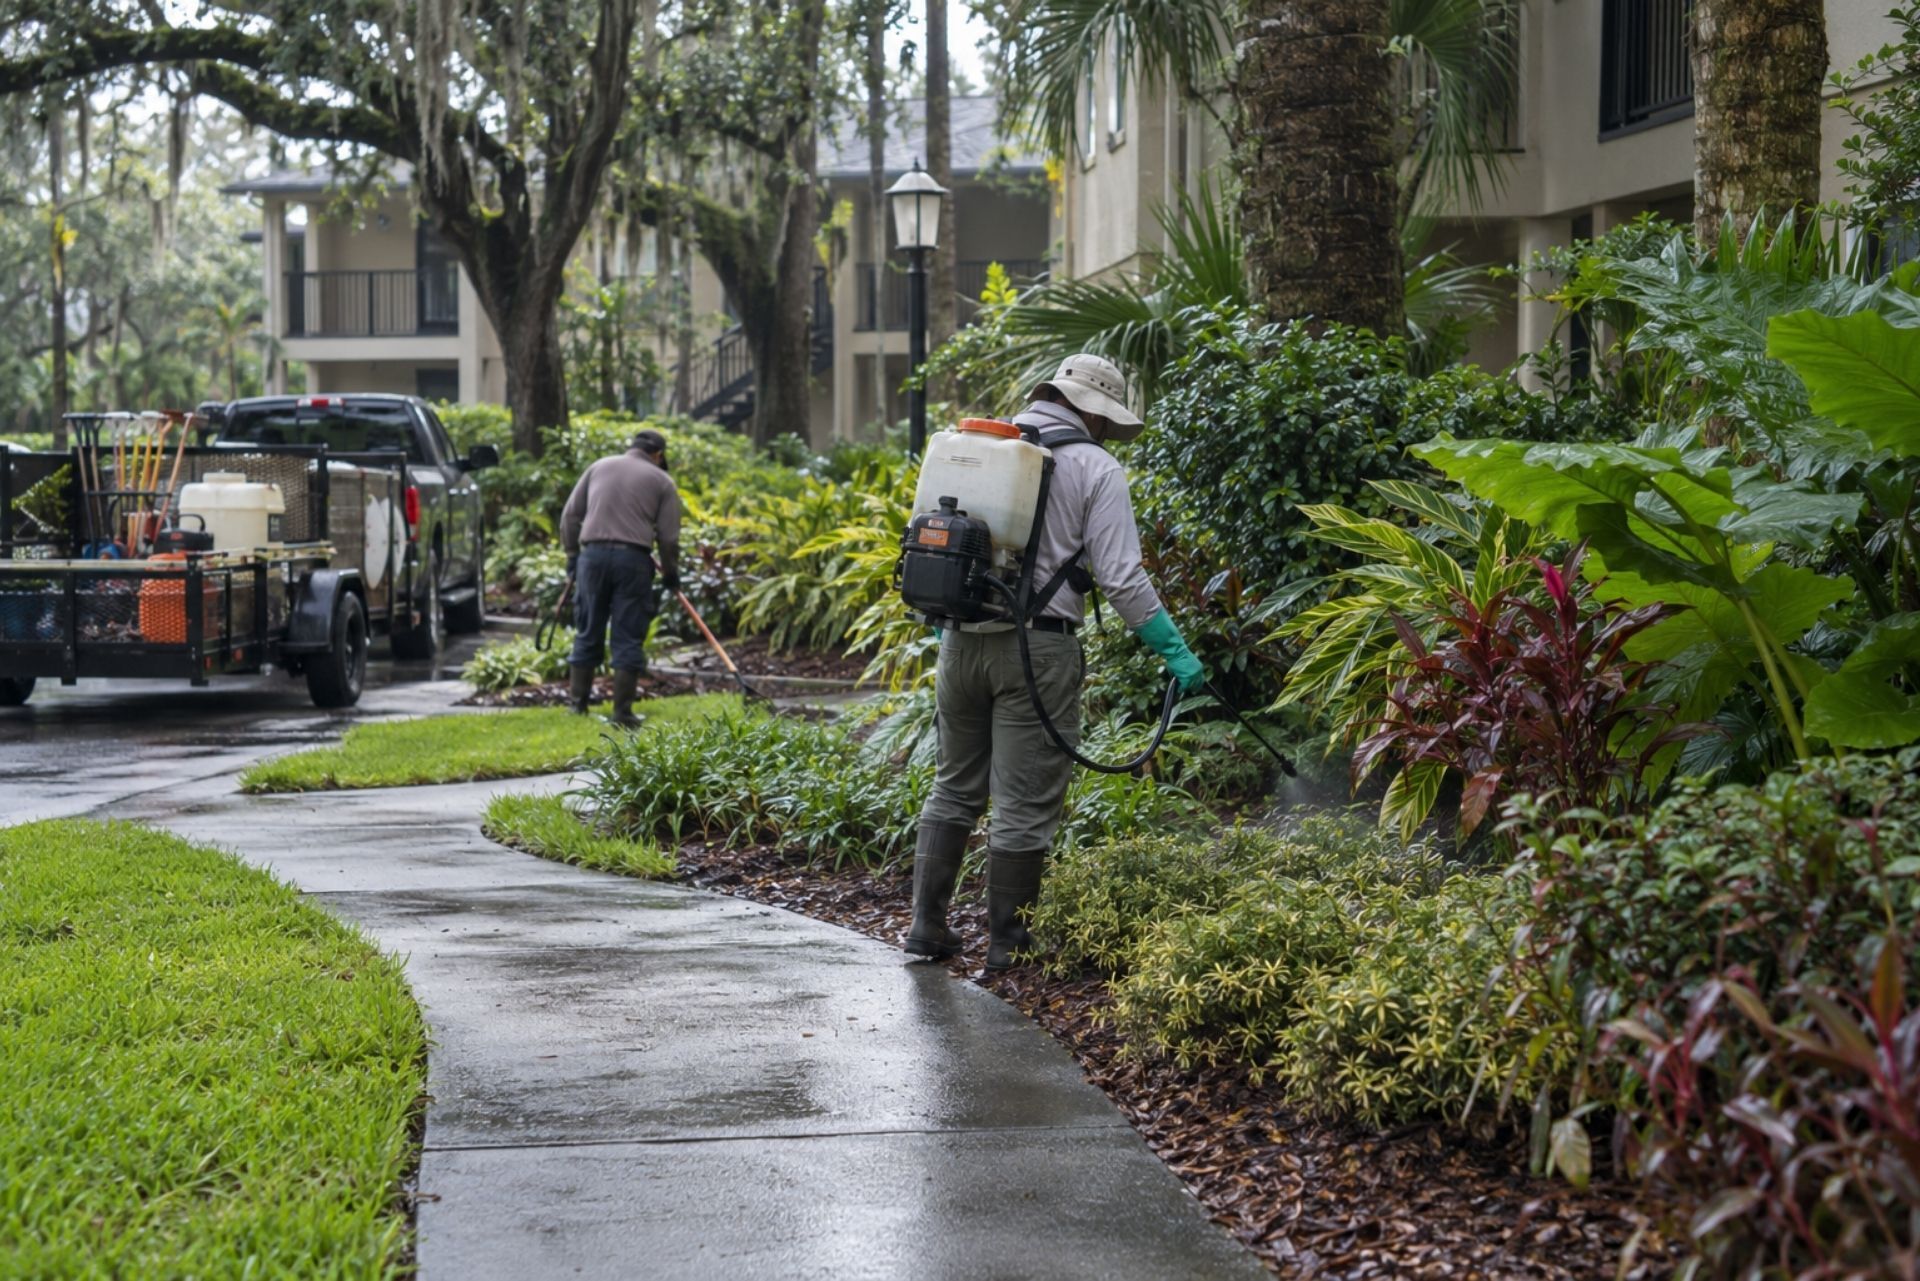
Spraying weed killer or insecticide changes your risk profile considerably. Louisiana regulates commercial pesticide application through the Louisiana Department of Agriculture and Forestry, and businesses applying chemicals for hire generally need proper licensing and certified applicators. Licensing requirements may include showing proof of liability insurance, so confirm current rules directly with the department before you start spraying.


The bigger issue is what your policy actually covers. Many standard general liability forms contain a pollution exclusion, and herbicide drift can fall right into it. If your crew sprays a fence line on a breezy afternoon in Covington and the neighbor's prized azaleas or vegetable garden die off, you could be facing a claim your base policy won't touch. People who suffer spray drift damage are increasingly told they need to know their options, because standard liability may not automatically respond to these environmental events without specific riders.


That's where a pollution liability endorsement or a dedicated applicator policy comes in. These may cover:


  • Drift damage to neighboring plants, lawns, or crops
  • Bodily injury claims from chemical exposure
  • Contamination of ponds, wells, or drainage areas
  • Cleanup costs following an accidental spill


One common mistake: a lawn care company adds spraying as a side service and never tells its agent. Your carrier needs to know every service you perform. Undisclosed operations are a fast way to a denied claim.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Securing Trailers and Equipment Against Theft

Landscaping equipment is a favorite target for thieves. It's valuable, portable, rarely marked with serial numbers people track, and easy to sell. A loaded open trailer parked outside a gas station holds tens of thousands of dollars in gear that can vanish in a few minutes.


Your general liability policy doesn't cover your own equipment, and commercial property coverage often protects items only at your listed business address. Inland marine coverage, sometimes called a contractor's equipment floater, fills that gap. It may protect mowers, blowers, trimmers, and trailers while they're in transit, parked at a job site, or stored overnight away from your shop.


When setting up inland marine coverage, pay attention to these details:


  1. Scheduled vs. unscheduled items: Big-ticket equipment like zero-turns usually gets listed individually with serial numbers. Hand tools often fall under a blanket limit.
  2. Valuation method: Replacement cost typically pays more than actual cash value, which subtracts depreciation.
  3. Theft conditions: Some policies may require that equipment be locked or secured for theft coverage to apply.
  4. Trailer coverage: The trailer itself may need separate scheduling or auto policy coverage.


Securing gear protects more than your property. An improperly strapped mower that falls off a trailer can lead to multi-million dollar lawsuits if it strikes another vehicle. Ratchet straps, tongue locks, and wheel locks are inexpensive compared to either outcome.

Feature Basic Coverage Extended Coverage
Property valuation Actual cash value (depreciated) Replacement cost (new item price)
Liability limit $100,000 $300,000 to $500,000
Valuables (jewelry, guns, art) Low sublimits, often $1,500 or less Scheduled items at appraised value
Water backup from drains Usually excluded May be added by endorsement
Loss of use Limited dollar cap Higher cap or longer timeframe
Flood Not covered Still not covered (needs NFIP or private flood)
Named storm deductible Percentage applies Percentage applies, sometimes lower options

How coverage choices change a Louisiana homeowners premium. Structure only — your rate depends on your property. [CONFIRM figures]

How coverage choices change a Louisiana homeowners premium. Structure only — your rate depends on your property. [CONFIRM figures]

Scenario Dwelling limit All-other-perils deductible Named-storm deductible
Newer build, inland St. Tammany $350,000 $1,000 2%
Newer build, higher wind zone $350,000 $1,000 5%
Older home, updated roof $275,000 $2,500 2%
Older home, original roof $275,000 $2,500 5%
Fortified roof designation $400,000 $1,000 2%
Rebuilt after a prior claim $400,000 $2,500 5%
Bundled with auto $350,000 $1,000 2%

Managing Risk with Seasonal Crews

Louisiana's long growing season means many landscapers staff up heavily from spring through fall, then cut back in winter. That swing in headcount directly affects your workers compensation premium, which is typically calculated based on estimated payroll and job classification codes.


Here's how it usually works. You estimate annual payroll at the start of the policy term, pay a premium based on that estimate, and then the carrier audits your actual payroll at year's end. Hire more seasonal workers than you projected, and you'll owe additional premium. Overestimate, and you may get money back. Many owners get surprised by audit bills because they forgot to account for summer crews.


Short-term employees still need coverage. Louisiana generally requires employers to carry workers compensation for their employees, and a seasonal hire who gets cut by a trimmer line in July is just as covered, and just as expensive to leave uninsured, as a ten-year foreman. Paying workers as independent contractors to avoid this can backfire, since the state may reclassify them as employees after an injury.


If you use a staffing agency, ask whether the agency's workers comp covers those laborers. Keep certificates of insurance on file for any subcontractors, too. Without them, an auditor may add uninsured subcontractor payroll to your premium.

Coverage Comparison: General Liability vs. Inland Marine

These two coverages get confused constantly, so here's a side-by-side look:

Situation General Liability Inland Marine
Rock breaks client's car window Typically covered Not covered
Your mower stolen from trailer Not covered Typically covered
Customer trips over your hose Typically covered Not covered
Trailer damaged in transit Not covered May be covered
Equipment damaged at job site Not covered Typically covered
Herbicide drift kills neighbor's plants Often excluded without endorsement Not covered

The short version: general liability protects other people's stuff, while inland marine protects yours.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Common Questions About Landscaping Insurance

Do I need insurance for a lawn mower trailer? Yes. Your commercial auto policy may cover liability while towing, but physical damage or theft of the trailer itself often requires scheduling it on auto or inland marine coverage.


Does my policy cover broken windows from rocks? General liability typically covers third-party property damage like a window broken by mower debris. Your deductible and specific policy terms will determine how the claim is paid.


Am I covered if my weed spray drifts onto a neighbor's yard? Not always. Many standard liability policies exclude pollution events, so you may need a pollution endorsement or applicator-specific coverage.


Do part-time summer workers need workers comp? In most cases, yes. Louisiana generally requires coverage for employees regardless of whether they work full time, part time, or seasonally.


Will my homeowners policy cover my landscaping equipment? Usually not once it's used for business. Homeowners policies typically limit or exclude business property, which is why landscapers carry inland marine coverage.


How long can a client wait to sue me for property damage? Louisiana generally allows two years from the date the damage was sustained to file a property damage lawsuit.

Making the Right Choice for Your Crew

Every Louisiana landscaping operation looks a little different. A two-person mowing outfit in Slidell has different needs than a full-service company running spray rigs and three trucks across St. Tammany Parish. The right program typically pairs general liability for flying debris and client property, a pollution endorsement if you apply chemicals, inland marine for your mowers and trailers, and workers compensation that keeps pace with seasonal hiring.


The owners who get hurt worst by claims are usually the ones who never reviewed their policies after adding a service or buying new equipment. A quick annual check-in with your agent can catch those gaps before they turn into denied claims.


Aubert Insurance Agency has served Covington and Slidell since 1910, and as an independent agency, we compare options from multiple carriers so you can see how coverages and exclusions differ. We'll also explain what your policy actually says, so nothing catches you off guard. Start a Quote today and make sure your crew, your gear, and your clients' property are covered before the next busy season starts.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
