













Slidell LA Flood Insurance

Covington & Slidell Independent Insurance Agents

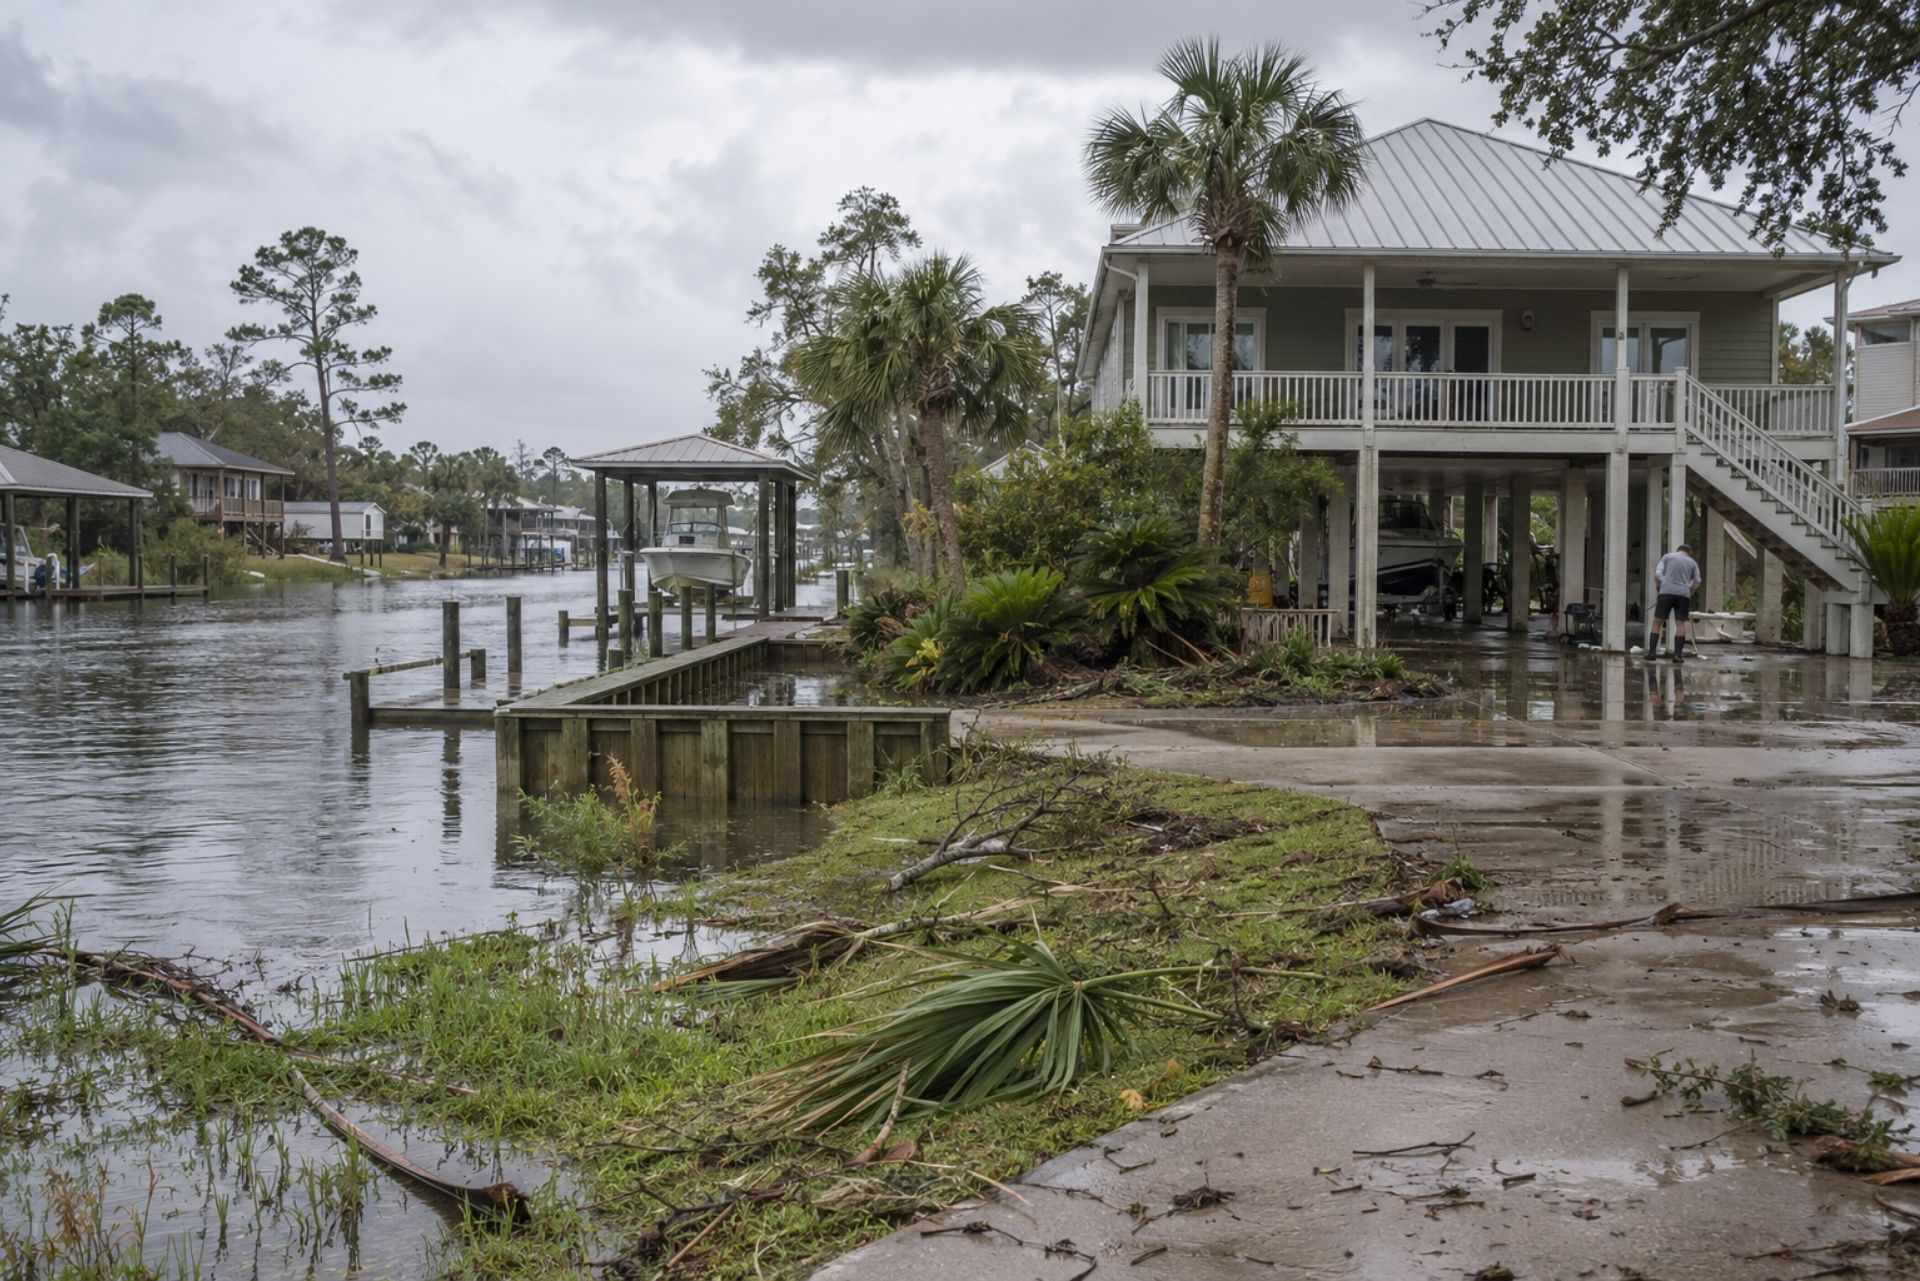
Slidell flood insurance helps pay for damage when storm surge pushes through the Rigolets into Lake Pontchartrain or when the Pearl River backs up into North Slidell neighborhoods. Your flood zone, your elevation, and how your raised home is built all shape what a policy may cover and what it typically costs.


Most homeowners here learn their flood zone at closing and never revisit it. That can be a mistake. The water that reaches a house in Eden Isles behaves differently from the water that creeps into a yard off Highway 41, and a standard policy treats a raised camp differently from a slab home on Gause Boulevard. This guide walks through the three main flood sources around Slidell, explains what Coastal A and V zone labels mean for your wallet and your building plans, and covers a gap that surprises many owners of elevated homes: what happens to the stuff stored underneath.

Understanding Flood Risks in Slidell Louisiana

Slidell flood insurance protects homeowners against two very different threats: saltwater storm surge funneling through the Rigolets from the Gulf, and freshwater flooding when the Pearl River and local bayous overflow. Aubert Insurance Agency has helped St. Tammany Parish families sort through both risks since 1910.


Slidell sits in an unusual spot. Lake Pontchartrain lies to the west and south, the Rigolets and Lake Borgne connect it to open Gulf water, and the Pearl River basin runs along the east side. A home can face one of these risks, two of them, or all three, depending on the street.


Standard homeowners policies typically exclude flood damage entirely. That means a separate flood policy, either through the National Flood Insurance Program or a private carrier, is usually the only way to cover rising water. Private flood options may offer higher limits or different contents terms, but features vary by carrier, so comparing them side by side matters.


Relief is slowly coming. St. Tammany Parish received $3.25 million in 2026 to advance the $5.9 billion Coastal Storm and Flood Risk Management Project, which includes new levees for the Slidell area and home elevations. Large projects like this take years, though, and your policy needs to fit the risk you face this hurricane season, not a decade from now.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Storm Surge Risks Through the Rigolets

The Rigolets is a narrow pass, and that is exactly what makes it dangerous. When a hurricane pushes Gulf water into Lake Borgne, the Rigolets and Chef Menteur Pass act like funnels, driving water into Lake Pontchartrain and against Slidell's southern shoreline. Neighborhoods such as Eden Isles, Oak Harbor, Lakeshore Estates, and the camps along Highway 90 feel this first.


Surge is not a slow rise. It arrives fast, carries debris, and often comes with wave action that can batter foundations and siding. Saltwater also does lasting damage to wiring, HVAC systems, and appliances, which is why surge claims in this area tend to involve more than drywall and flooring.


A few things to check if you live south of I-10:


With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Pearl River Backwater in North Slidell

Here is the flood risk that catches people off guard: the sky over Slidell can be clear and the Gulf completely calm while water rises in North Slidell. Backwater flooding starts upriver. When heavy rain soaks central Louisiana and the Pearl River basin for days, all that water has to drain south toward the Gulf, and it moves slowly.


As the Pearl swells, it pushes into the West Pearl, Bayou Liberty, Bayou Bonfouca, and the smaller drainage channels that feed them. Those channels can no longer empty, so water backs up into neighborhoods along Highway 41, Military Road, and the areas east of Old Spanish Trail. A local rainstorm on top of a high river makes things worse, because neighborhood drainage has nowhere to go.


That is why North Slidell owners sometimes skip flood coverage. They are outside a high-risk zone, no hurricane is coming, and the lender does not require it. Then a spring river crest arrives.


Flow control upstream matters here. Officials began permitting in July 2026 for the Walkiah Bluff Weir rehabilitation on the East Pearl, a project meant to restore water flow regulation that failed in 2022. Farther up the basin, the Pearl River Flood Control Project advanced in early 2026 with a plan for widening the river within the existing levee system and constructing a weir south of I-20. These efforts may help over time, but they do not replace a policy on your house today.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Coastal A and V Zones Explained

FEMA flood maps around Slidell use a handful of letter codes, and the ones that matter most near the water are AE, Coastal A, and VE. All of them sit inside the Special Flood Hazard Area, meaning lenders with federally backed mortgages will typically require flood insurance.


The difference between them comes down to waves. An AE zone floods, but the water mostly rises and falls. A VE zone sees floodwater plus breaking waves strong enough to knock a house off a weak foundation. Coastal A zones fall in between: closer to the shore than a typical AE, with moderate waves, often shown on maps with a line called the Limit of Moderate Wave Action, or LiMWA.


Your zone affects more than the premium. It controls how you can build, repair, or add onto your home, and those rules come up fast after a storm when owners want to rebuild.

Differences in Flood Zone Requirements

Properties in Zone VE face wave action of 3 feet or higher, and building codes there mandate open pile or column foundations with breakaway walls. In AE zones, the home must still be elevated above the Base Flood Elevation (BFE), but solid foundations are often permitted. Coastal A zones typically pick up some V zone construction standards because of the wave exposure.

Feature Zone AE / Coastal A Zone VE
Wave action Under 3 feet (Coastal A: 1.5 to 3 feet) 3 feet or higher
Foundation type Solid foundations often allowed in AE; Coastal A may require open foundations locally Open pilings or columns required
Enclosures below Flood vents typically required Breakaway walls only
Elevation reference Lowest floor at or above BFE Bottom of lowest horizontal structural member at or above BFE
Typical premium impact Moderate to high Highest

One common mistake: buying a VE home with a fully finished, enclosed ground floor added after original construction. That enclosure may not comply, and it can raise the premium significantly or complicate a claim.

Covington & Slidell Independent Insurance Agents

Comparison of Standard vs. Waterfront Coverage Limits

Contents Coverage for Raised Homes

Raised homes are everywhere in Slidell, from fishing camps on the Rigolets to newer builds on pilings in Eden Isles. Owners often assume that because the living space sits high, everything is protected. The catch is that flood policies treat the area below the lowest elevated floor very differently from the rooms above it.


For homes elevated on pilings, piers, or crawlspaces, NFIP building coverage below the lowest elevated floor is typically restricted to structural elements and essential utilities. Contents coverage is even narrower down there. In practice, that means:


  • Usually covered below: pilings and foundation elements, stairways, electrical panels, HVAC units, water heaters, fuel tanks, and well pumps. Washers, dryers, and food freezers may be covered under contents if you carry contents coverage.
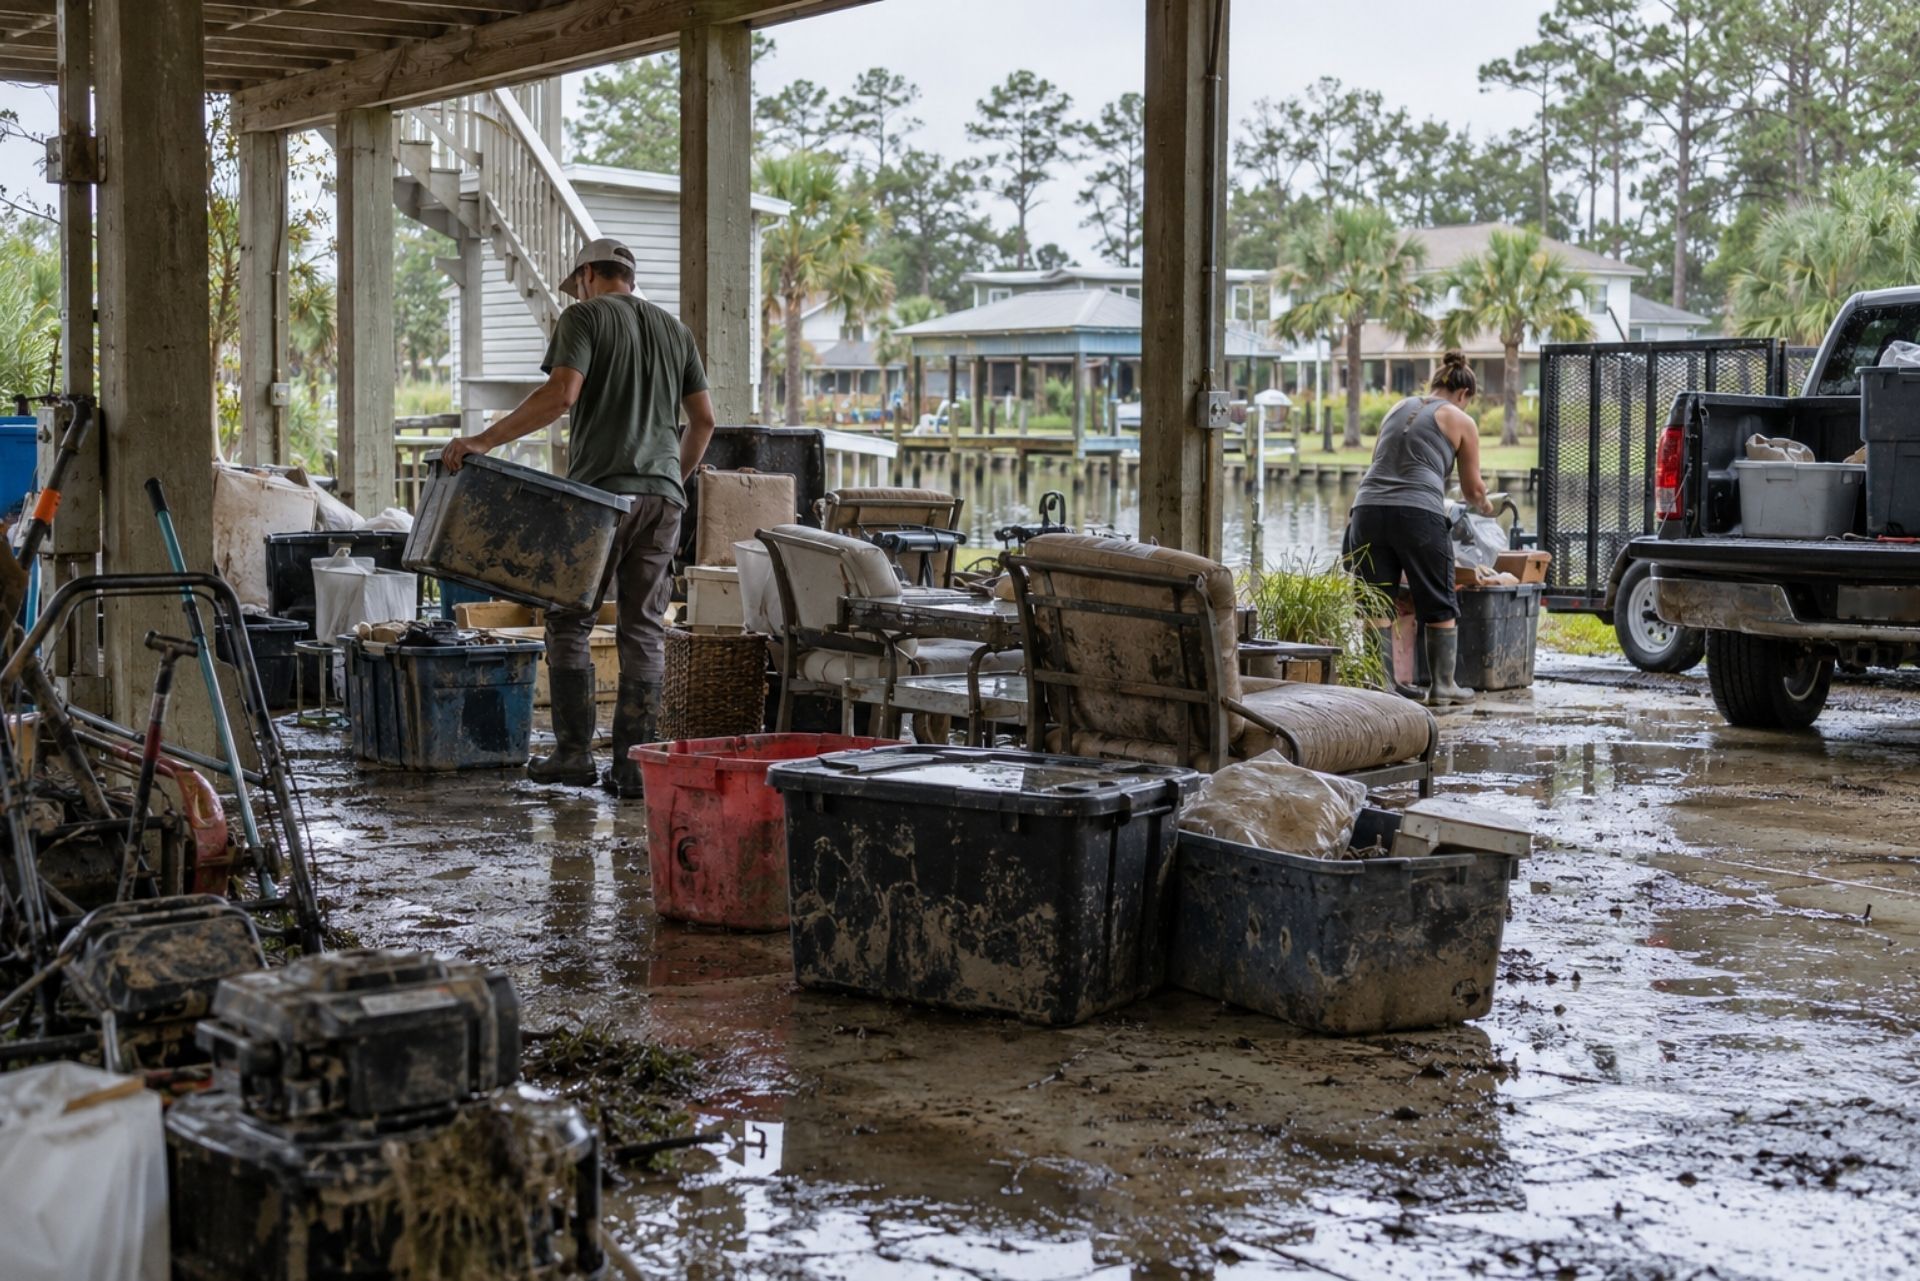
  • Usually not covered below: golf carts, tools, lawn equipment, patio furniture, stored boxes, finished walls, flooring, and storage closets built under the house.
  • Covered above: furniture, clothing, electronics, and household items in the elevated living area, up to your contents limit and subject to the deductible.


The real-world problem shows up after a surge. An owner parks a golf cart, stores holiday decorations, and keeps a second refrigerator full of fishing gear under the house. The water takes it all, and the policy pays for little of it.


Some private flood carriers may offer broader coverage for property below the elevated floor, so this is worth comparing if you store valuables underneath. Otherwise, the practical fix is simple: keep anything you cannot afford to lose up in the living space, and photograph what you store below.

not, unless you're both named on the policy. Each roommate typically needs their own coverage, and shared policies can get messy when one person files a claim.


Will my renters insurance cover my dog biting someone? Many policies include pet liability under personal liability, but some carriers exclude certain breeds or cap dog bite claims. Tell your agent about your pet upfront so there's no surprise later.


Does my landlord's insurance cover my belongings? No. Your landlord's policy typically covers the building only, so your furniture, clothes and electronics need your own policy.


When should I buy flood insurance before hurricane season? Aim for spring. NFIP contents coverage generally has a 30-day waiting period, so buying in late May means protection by the heart of the season.


What should I do to prepare my rental for a hurricane? Take a video walkthrough of every room, save receipts for big items in the cloud and keep a copy of your policy on your phone. Good documentation is the single biggest factor in how fast a storm claim gets paid.


Will renters insurance pay for a hotel if we evacuate? It depends. Loss of use typically kicks in when your rental is uninhabitable from a covered loss or when a civil authority orders evacuation, but check your policy wording.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Coverage What It Covers Example Claim Required for License?
General Liability Injury to others, damage to client property Dust ruins a homeowner's sofa Yes, $500,000 minimum (residential)
Workers' Compensation Your employees' injuries and lost wages Taper falls from stilts Required if you have employees; proof needed for labor-only subs
Professional Liability Errors in advice or design Rarely relevant unless you design or consult No
Mold Buy-Back Limited mold claims, if offered Mold blamed on board you installed No, but often worth considering
Feature General Liability Garagekeepers Legal Liability Garagekeepers Direct Primary
What it protects Third-party injury and property damage from your operations Customer vehicles in your care Customer vehicles in your care
Fault required? Yes, you must be liable Yes, you must be negligent No, pays regardless of fault
Covers customer cars on your lot? Usually excluded Yes, if you're at fault Yes
Hail or flood to customer cars No Usually not (act of nature) Typically yes, if peril is covered
Customer relations N/A Customer may need to file with own insurer Shop handles claim directly
Relative cost Base cost Lower Higher

Common Questions About Slidell Flood Insurance

Do I need flood insurance in North Slidell if I'm not in a high-risk zone? Your lender may not require it, but Pearl River backwater can reach homes outside mapped high-risk areas. Coverage in lower-risk zones is often priced more reasonably, which makes it worth a quote.


How long does it take for a flood policy to start? NFIP policies typically have a 30-day waiting period, with limited exceptions such as a policy tied to a home purchase. Private flood policies may have shorter waiting periods depending on the carrier.


Does my homeowners policy cover storm surge? Generally, no. Surge is treated as flood, which standard homeowners policies typically exclude, though wind damage from the same storm may fall under your homeowners or windstorm coverage.


What is an elevation certificate and why does it matter? It is a document from a licensed surveyor showing your home's elevation compared to the Base Flood Elevation. It can have a real effect on your rating and helps an agent compare carriers accurately.


Is my stuff under my raised house covered? Mostly not. Utilities and structural parts below the lowest elevated floor are typically covered, but stored belongings, vehicles, and tools usually are not.


Can I get flood coverage above the NFIP limits? Yes, excess flood policies may add building and contents limits above the NFIP caps, which helps owners of larger lakefront homes.

Making the Right Choice for Your Property

Every flood policy in Slidell comes back to the same three questions: where the water comes from, how your home is built, and what you keep in it. A home in Eden Isles facing surge through the Rigolets needs a different conversation than a house off Highway 41 watching the Pearl River crest. Both deserve more than a renewal notice you sign without reading.


Start with your elevation certificate. Pull it out, or order one if you never received it, and review it with an agent who can explain what your lowest floor elevation, foundation type, and zone mean for your coverage options. Small details, like a ground-level enclosure or a missing flood vent, can change how carriers rate your home.


As an independent agency, Aubert Insurance Agency compares NFIP and private flood options from multiple carriers in one place and walks you through the exclusions before you commit. The process is simple: start online, let us shop for you, and pick the plan that fits.


Ready to see where your home stands on Slidell flood coverage? Start a Quote today, and get your policy squared away well before the next storm enters the Gulf.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
