













Covington & Slidell Independent Insurance Agents
Most Louisiana restaurants need five core protections: general liability, liquor liability, property coverage with food spoilage and equipment breakdown, and workers compensation. Louisiana's anti-dram shop law limits some alcohol claims but leaves real gaps. Hurricane-season outages, grease fires, and kitchen injuries make the other four coverages just as essential for a local dining room.
A single August storm can knock out power along Highway 190 for three days, and a walk-in cooler full of Gulf shrimp and prime rib won't wait for the lines to come back. That's one reason restaurant insurance in Louisiana looks different from a policy written anywhere else. Below, we cover how state law treats liquor claims, what spoilage coverage actually pays for, how fryer fires get handled, and why so many local operators carry workers comp through their trade association.
Essential Insurance Protections for Louisiana Restaurants
A restaurant policy is rarely one policy. Most operators in St. Tammany Parish end up with a package, usually a business owner's policy (BOP), plus separate pieces for alcohol and employees. Here's what a typical stack looks like:
- General liability: Slip-and-fall claims, customer injuries, and some foodborne illness allegations.
- Commercial property: Building (if owned), kitchen equipment, furniture, and inventory.
- Business income: Lost revenue when a covered loss forces you to close.
- Liquor liability: Claims tied to serving alcohol, which general liability often excludes.
- Workers compensation: Required for most Louisiana employers with staff.
- Commercial auto or hired/non-owned auto: Important if you run catering or delivery.
The most common mistake we see is assuming the BOP covers everything. Many BOPs exclude liquor liability outright and may limit spoilage to a small sublimit. Read the declarations page line by line, or have someone walk you through it.

On this page
Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.
We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.
Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820
Liquor Liability Under Louisiana's Server Immunity Statute
Louisiana takes an unusual position on alcohol claims. Many states let injured third parties sue the bar that served a drunk driver. Louisiana mostly doesn't, and that changes how restaurant owners should think about liquor coverage.
Understanding the Louisiana Anti-Dram Shop Act
Louisiana Revised Statute 9:2800.1 declares that the consumption of alcohol, rather than the serving of it, is the proximate cause of injury or damage caused by an intoxicated person. In practical terms, the law shields permit holders and their employees from liability for off-premises injuries caused by a patron of legal drinking age.
The immunity has limits. Serving someone under 21 falls outside the protection, and the statute also excludes situations where a server forces or coerces someone to drink, or falsely tells them a drink has no alcohol. Injuries that happen on your premises, like a fight in the parking lot, can also lead to claims under ordinary negligence theories.
Here's why you still want liquor liability coverage. Even a claim that eventually gets dismissed costs money to defend, and plaintiffs' attorneys often argue the facts fit an exception. A liquor liability policy typically pays defense costs from the first letter, which matters far more than most owners expect. Pair it with consistent ID checks and documented server training to strengthen your position.
Managing Spoilage Coverage After Power Outages
Spoilage claims are where restaurant owners get surprised most often after a storm. The coolers fail, the inventory goes in the dumpster, and then the adjuster points to a utility service exclusion.
Many property policies only cover spoilage if the power loss starts with direct physical damage at your location. If a transformer three miles away goes down, that "off-premises" outage may not trigger coverage unless you've added utility service interruption coverage. Some carriers also apply a waiting period, often measured in hours, before the coverage kicks in.
When reviewing your policy, look for:
- Spoilage sublimit: Is it enough to replace a full stock of proteins and seafood during peak season?
- Off-premises power trigger: Does it cover outages caused by damage away from your building?
- Mechanical breakdown: Is a failed compressor covered, or only power loss?
- Waiting period: How long must the outage last before coverage applies?
Keep a dated inventory log and photograph cooler contents before discarding anything. Adjusters may ask for invoices, so store them digitally, not on paper in the back office that floods.

Fryer Fires and Kitchen Property Damage
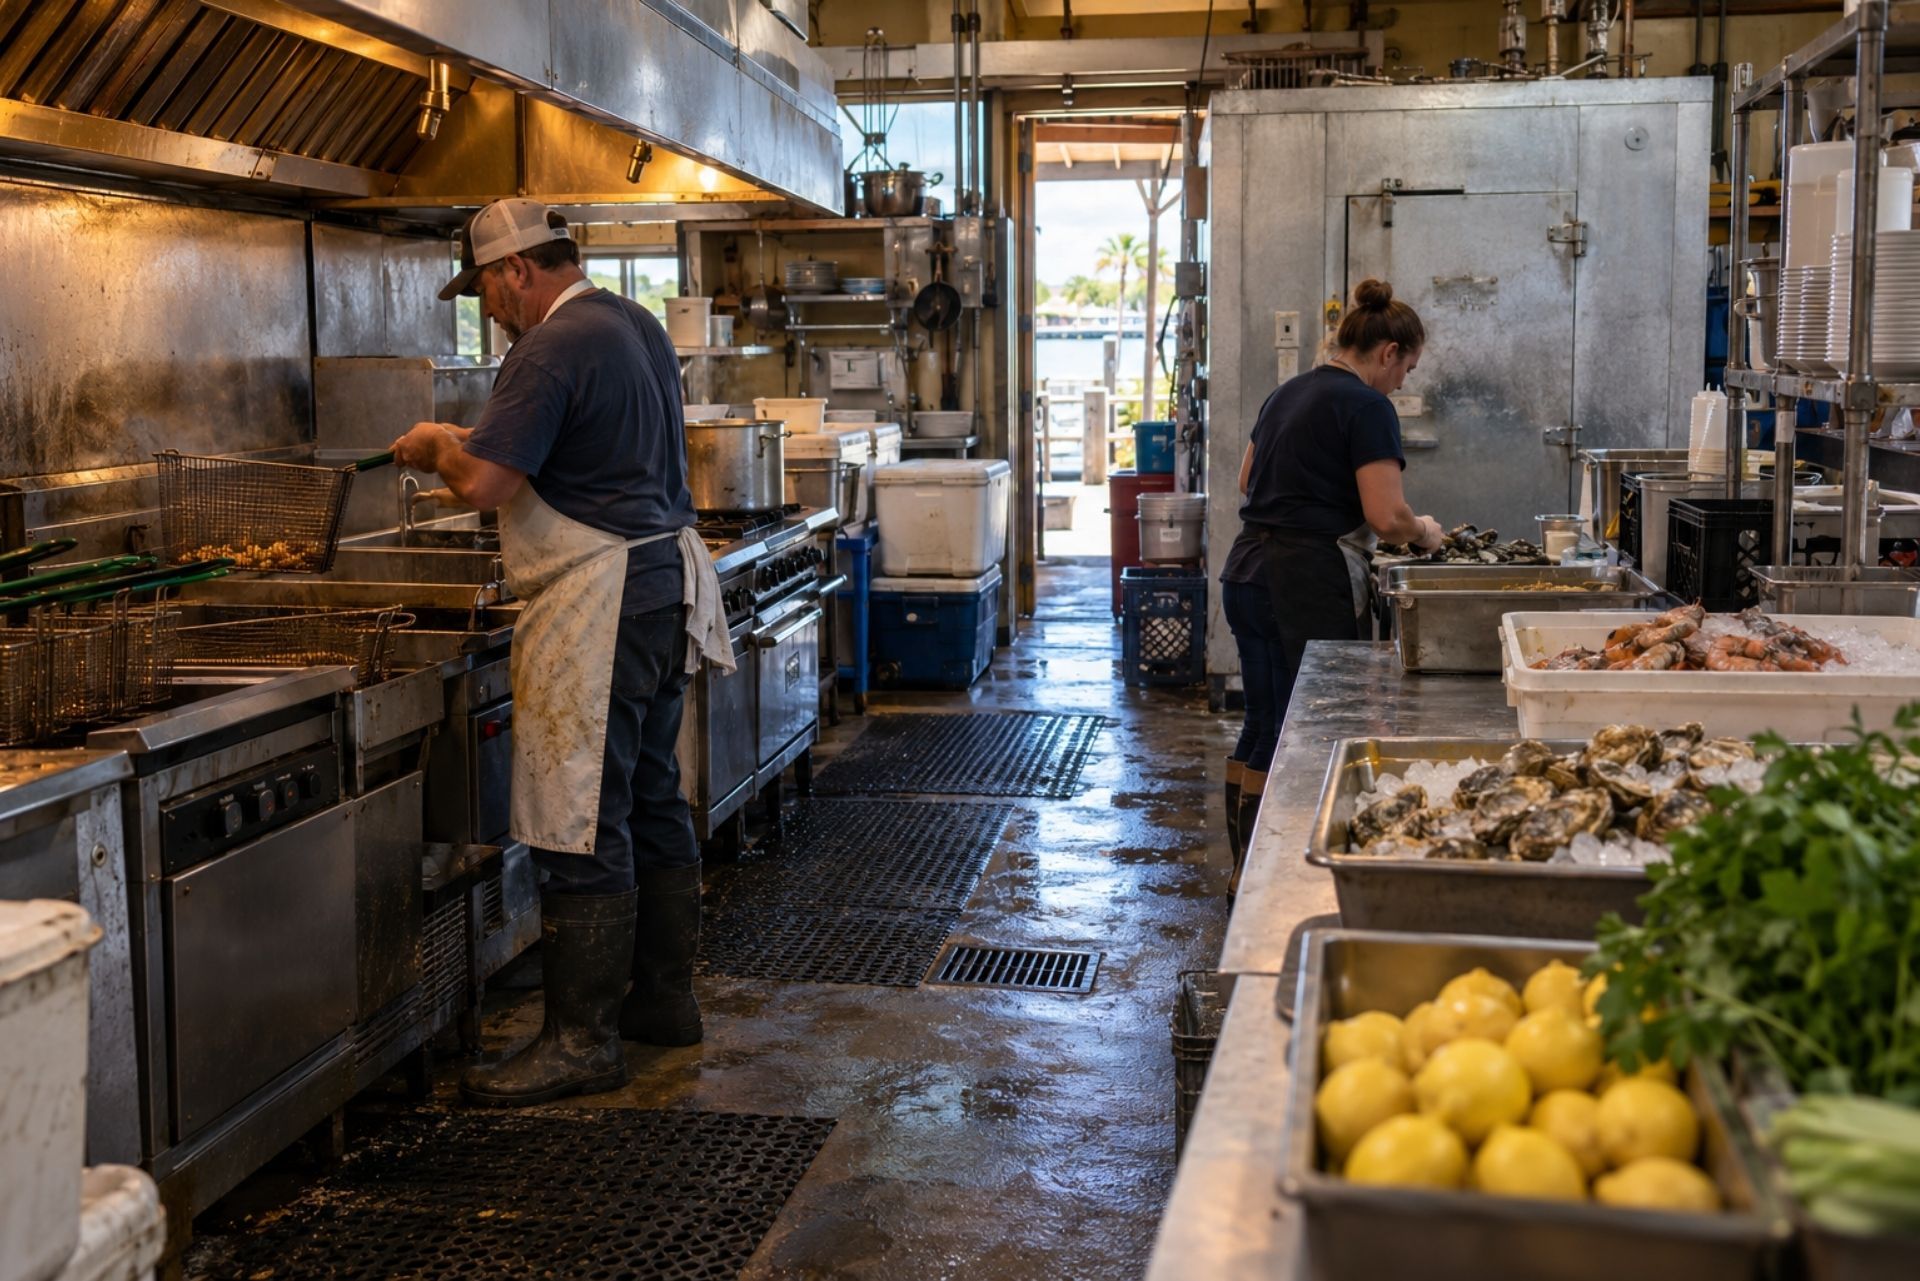
Grease fires are the classic restaurant loss, and Louisiana kitchens run fryers hard. A single fryer fire can damage hood systems, ductwork, walls, and the roof, then shut you down for weeks while repairs and inspections catch up.
Standard commercial property coverage typically handles fire damage to the building and contents. The less obvious costs are where gaps show up. When your hood suppression system discharges, it coats the line in chemical residue, and cleanup plus recharging the system can run up a sizable bill even if the fire was small. Some policies may treat accidental discharge differently from an actual fire, so ask how yours handles it.
Equipment breakdown coverage fills a different hole. It may pay for sudden mechanical or electrical failure, like a fryer's thermostat shorting out or a compressor burning up, which standard property forms often exclude.
Carriers look closely at fire safety practices during underwriting and claims. NFPA 96 standards call for quarterly hood cleaning in high-volume frying operations, and NFPA 10 and 96 require a Class K extinguisher within 30 feet of deep-frying equipment. Keep cleaning receipts on file. Also note that as of June 22, 2026, the Office of State Fire Marshal handles inspection requests and plan reviews through a centralized online portal, so build that into renovation timelines after a fire.
Workers Comp Through the Restaurant Association Fund
Kitchens produce a steady stream of comp claims: burns from fryer oil, knife cuts, back strains from hauling produce cases, and slips on wet tile. For Louisiana hospitality businesses, one option stands apart from conventional carriers.
The Louisiana Restaurant Association Self-Insurers Fund is a not-for-profit, member-owned pool and the only provider in the state focused exclusively on hospitality. That focus means the people underwriting and managing claims understand restaurant work, from late-night closing shifts to the realities of turnover in front-of-house staff.
Because the fund is member-owned, good collective results can flow back to participants. The fund has historically returned more than $112 million in dividends to its members, though dividends are never guaranteed in a given year.
The fund also launched a structured Return-to-Work program effective September 15, 2026, designed to help employers move injured staff into light-duty tasks. For a restaurant, that might mean a line cook with a wrist injury handles prep labeling or host duties while healing. Getting people back sooner typically lowers claim costs and keeps experienced workers on your team.
Key Differences in Restaurant Coverage Options
Owners often ask whether they should bundle everything or buy pieces separately. The answer depends on your size, your bar sales, and how much risk you're comfortable holding.
| Coverage Area | Basic Package | Expanded Protection |
|---|---|---|
| Liquor liability | Often excluded or minimal | Standalone policy with defense costs |
| Food spoilage | Small sublimit, on-premises only | Higher limit, off-premises power included |
| Equipment breakdown | Usually excluded | Covers sudden mechanical failure |
| Suppression discharge | May be unclear | Cleanup and recharge addressed |
| Business income | Limited days | Longer restoration period |
| Workers comp | Standard carrier | Hospitality-focused fund option |
The expanded column costs more, but it's built around the losses Louisiana restaurants actually file. A coffee shop with no alcohol and one fryer has very different needs than a seafood house pouring cocktails until midnight.
Frequently Asked Questions About Louisiana Restaurant Insurance
Do I need liquor liability if Louisiana has server immunity? Yes, in most cases. The immunity has exceptions, like serving minors, and a policy typically covers your defense costs even when a claim lacks merit.
Will my policy pay for food lost during a hurricane outage? It depends on your spoilage limit and whether off-premises power loss is included. Many basic policies only cover outages caused by damage at your own building.
Is workers comp required for my restaurant? Most Louisiana employers with employees must carry it. Even a small staff of part-time servers usually triggers the requirement.
What happens if my fire suppression system goes off by accident? Coverage for cleanup and recharging varies by carrier. Ask your agent to confirm in writing how your policy treats accidental discharge.
Can I join the Louisiana Restaurant Association fund? The fund serves hospitality businesses, and an agent can help you compare it against conventional workers comp carriers.
Does general liability cover food poisoning claims? General liability typically responds to bodily injury claims from customers, including some foodborne illness allegations, but review exclusions carefully.
Making the Right Choice for Your Establishment
Louisiana gives restaurant owners some real advantages, like a strong anti-dram shop statute and a hospitality-focused workers comp fund. It also hands them real headaches: hurricane outages, humid kitchens that run fryers all day, and a policy market where exclusions hide in the fine print. The right protection comes from matching each coverage to the losses your specific operation is likely to face.
That's where a local conversation helps. Aubert Insurance Agency has been insuring St. Tammany businesses since 1910, and as an independent agency, we compare options from multiple carriers instead of steering you toward one. We'll also explain what your policy excludes, so a spoilage or suppression claim never catches you off guard.
Stop by our Covington or Slidell office, or reach out to talk through your menu, your bar sales, and your staff. When you're ready, Start a Quote and let us build a policy that fits the way your restaurant really runs.

About the Author
Kyle Beerbohm
President
We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.
Louisiana Insurance Questions, Answered
Questions clients ask us
Short, plain answers to what people ask before they call. Anything else, phone the office and ask.
What does an independent insurance agency do?
We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.
Which types of insurance does Aubert offer?
We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.
Do I need flood insurance in St. Tammany Parish?
Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.
Which states are you licensed in?
We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.
How do you find me a competitive rate?
We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.
How do I file a claim or request a certificate?
Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana
Coverage for your home, your vehicles, and your family
Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.
Home Insurance
Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.
Car Insurance
Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.
Flood Insurance
Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.
Umbrella Insurance
Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.
Boat Insurance
Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.
Life Insurance
Replace your income for the people who depend on it, with term and permanent options we quote across carriers.
Business Insurance in Louisiana
Coverage for the business you built
Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.
Contractors Insurance
General contractors, trade contractors and specialty crews. We cover the liability, tools, vehicles and workers your jobs depend on.
Business Owners (BOP)
One policy bundling property and liability for a small business. Straightforward cover for the building, the contents and the risk.
Professional Liability
Protection when your advice or professional work is challenged. A staple of any commercial package for a service business.
Commercial Property
Landlords and commercial real estate investors. We insure the building, the habitation risk and the income it produces.
Workers Compensation
Protecting your employees protects your business. Medical costs and lost wages covered when someone is hurt on the job.
Commercial Auto
Trucks, vans and fleets. We shop a wide range of commercial auto markets to match your vehicles and your drivers.
Business Insurance by Industry
We protect hundreds of businesses of all shapes and sizes
We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors
Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance
Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants
Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.
5-Star Rated by St. Tammany Clients
What Our Clients Say
Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.


Insurance Tips & Local News
Insurance tips for Louisiana homes and businesses
Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.
Request Your Free Insurance Quote
Tell us what you need covered
Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.
614 E. Boston St., Covington, LA 70433. (985) 892-3101
58418 Tyler Drive, Slidell, LA 70461 · (985) 641-0520
Call
614 E. Boston St., Covington, LA 70433
58418 Tyler Drive, Slidell, LA 70461













