













Louisiana Collector Car Insurance

Covington & Slidell Independent Insurance Agents

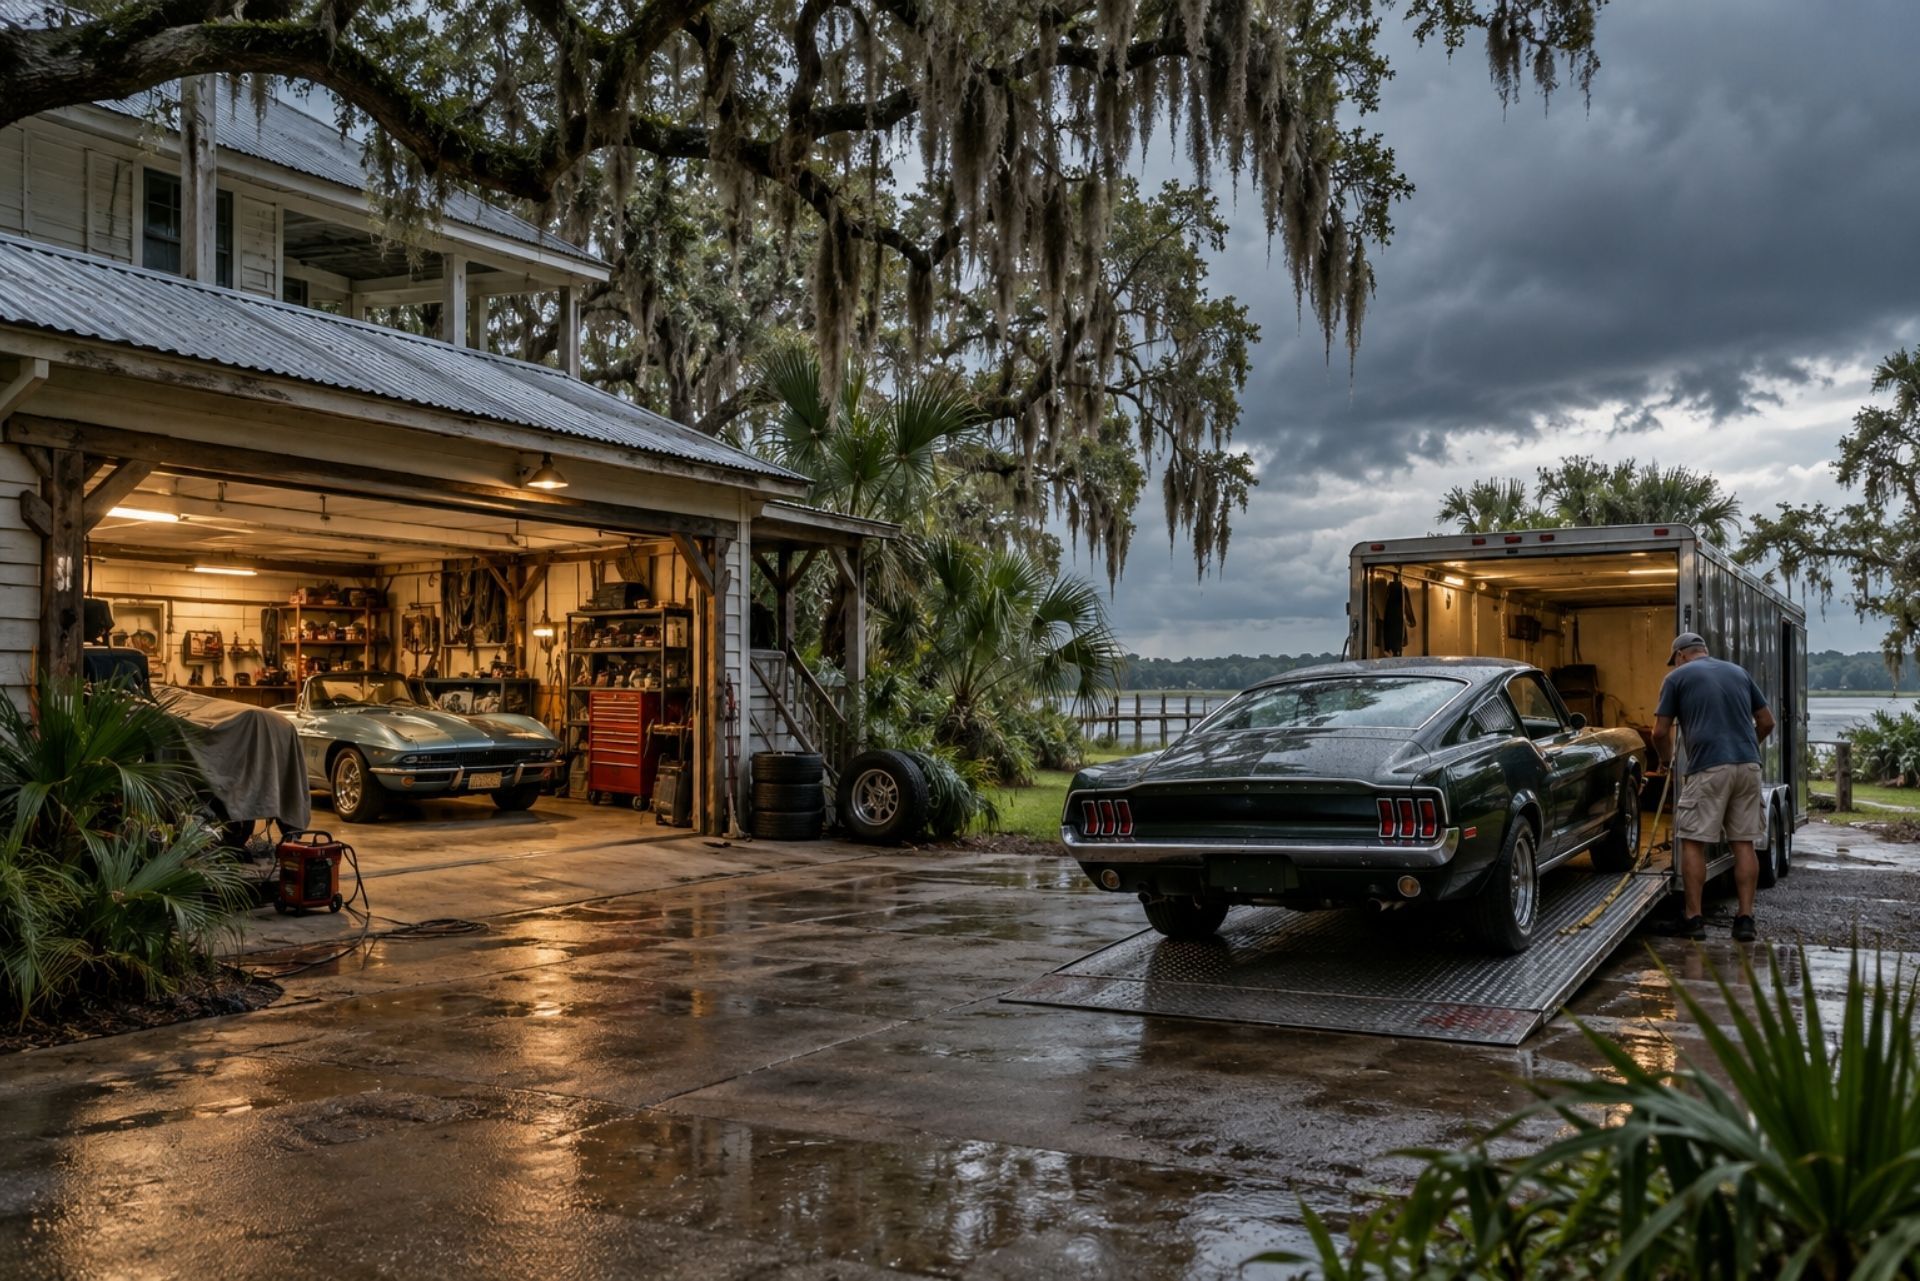
A 1967 Camaro sitting in a Slidell garage is a different risk than the minivan parked next to it. It has a different value, gets driven differently, and faces a different threat when the Gulf starts churning in late summer. Classic car owners in St. Tammany Parish need coverage built around those realities, not a policy designed for a daily commuter.

Understanding Louisiana Collector Car Insurance and Guaranteed Value

Collector car insurance in Louisiana is specialized coverage for classic, antique and special interest vehicles. Carriers like Hagerty may offer Guaranteed Value protection, which pays the true agreed worth of your car rather than a depreciated figure. Aubert Insurance Agency has helped Covington and Slidell owners protect what they value since 1910.


The state already treats these vehicles as their own category. Louisiana law defines a "Collector" as an owner of historic or special interest vehicles used for "hobby purposes" and "leisure pursuit." That definition reflects how collector policies are typically written: the car is a hobby asset, not transportation.


Registration follows the same logic. To qualify for the antique motor vehicle tax exemption, owners pay a one-time fee of $1,000 for a permanent antique license plate. That plate is a registration decision, not an insurance decision. Still, the two tend to travel together, because both rest on the car being used for leisure.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Guaranteed Value Coverage Through Hagerty

A standard auto policy usually pays actual cash value after a total loss. For a 15-year-old sedan, that math works fine. For a restored Mustang Fastback, it can be a disaster. An adjuster may run the VIN through a valuation tool, see "1966," and land on a number that has nothing to do with the auction results you've been tracking.


Guaranteed Value coverage approaches it differently. You and the insurer agree on the car's market value upfront. In a covered total loss, that full amount is typically paid without depreciation. Hagerty is one of the carriers that may offer this type of protection, though the exact terms depend on the policy and the vehicle.


The most common mistake we see is a valuation set once and then forgotten. Owners finish a $30,000 engine rebuild or watch their model climb in value, and the policy still reflects the 2019 number. Review the agreed figure every year, and keep receipts and photos of any restoration work to support an increase.

How Guaranteed Value Differs from Stated Value

These two terms sound nearly identical, and that causes real confusion at claim time. Stated value usually lets you name a figure, but the policy may pay the lesser of that figure or the actual cash value. You can pay premium on a $75,000 car and still receive a lower depreciated amount after a loss.


Guaranteed Value is generally designed to close that gap. The amount agreed at the start is the amount paid in a covered total loss. Before you sign anything, ask one plain question: "If this car is totaled tomorrow, what number shows up on the check?" A good agent should answer it without hedging.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Accounting firms hold Social Security numbers, bank details, and tax records, which makes them prime targets. One industry observer put it bluntly: for most CPA firms, cyber insurance is no longer optional, and failing to meet MFA and EDR requirements can result in denied claims or total exclusion from the market. Translation: carriers now want multi-factor authentication and endpoint detection software in place before they will write you, and they may check after a claim. A cyber policy may cover breach notification, forensic investigation, ransomware response, and lawsuits from affected clients.

Cyber Liability

Storage and Evacuation Planning Before a Storm

Hurricane season makes this section different for Louisiana collectors than for owners in most of the country. A classic car flooded with brackish water from Lake Pontchartrain is often a total loss, and wiring, upholstery and wood trim may never fully recover. Your plan needs to exist in June, not when a storm cone is already pointed at the Northshore.


Storage comes first. A locked, enclosed garage is usually what collector policies expect, and many carriers ask about it during underwriting. If your garage sits low, consider a raised lift, an elevated slab, or a climate-controlled facility on higher ground. Know the storage requirements written into your policy, because parking the car somewhere unapproved could complicate a claim.


Then build a transit plan you can actually carry out:


  • Decide early whether the car leaves. Driving a carbureted classic on I-12 in evacuation traffic carries its own risk. Enclosed transport booked in advance is often safer.
  • Line up a destination. A relative's garage inland or a storage facility outside the surge zone works, if it's secure and enclosed.
  • Confirm coverage in transit and at the new location. Ask whether your policy follows the car on a trailer and while it's stored temporarily elsewhere.
  • Document everything. Take date-stamped photos of the car, odometer and storage spot before you leave.
  • Watch binding restrictions. Insurers typically stop writing new policies or changes once a named storm is close, so set up coverage well before peak season.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Standard Policy vs. Collector Car Insurance Comparison

Here's how the two types of coverage typically compare on the points that matter most to classic owners.

Feature Standard Auto Policy Collector Car Coverage
Valuation at total loss Actual cash value, with depreciation Often Guaranteed Value, no depreciation
Effect of age Value usually drops each year Value can be agreed upward as market rises
Repair shop choice Insurer may steer to network shops Owner may choose a specialist restoration shop
Usage limits Daily driving, commuting allowed Pleasure, shows, club events; no commuting
Storage requirements Rarely specified Enclosed, secure storage typically required
Premium structure Priced for regular use Often lower because of limited use

The repair shop row deserves a second look. A body shop that does great work on late-model trucks may not know how to match lacquer paint or source an original trim piece. Collector policies frequently let you pick a shop that specializes in vintage work, which may protect both the repair and the car's value.

How Jones Act Exposure Differs From State Workers Comp

Mileage and Usage Rules for Classic Vehicles

Collector coverage comes with a trade. You accept limits on how the car is used, and the policy reflects that lower exposure. Occasional pleasure use is generally defined as club functions, exhibitions, tours and occasional pleasure driving. Think Sunday cruises along the Tammany Trace area roads, a car show in downtown Covington, or a club run to Abita Springs.


What's typically excluded matters just as much. Standard collector insurance explicitly rules out using the vehicle for routine shopping or daily commuting to work or school. Running to the grocery store in your Chevelle may feel harmless, but if an accident happens on an errand, that's exactly the kind of use a claims adjuster will question.


Mileage rules vary widely by carrier. Some policies set annual mileage caps in tiers, while others skip a fixed number and rely on usage definitions. Be honest about how much you drive when you apply. Underestimating to save a little on premium can create a coverage problem later.


Most carriers also expect you to own a separate everyday vehicle for each licensed driver in the household. That requirement is how insurers confirm the classic isn't quietly becoming a commuter.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Feature General Liability Professional Liability (E&O)
What it covers Physical injuries and property damage Mistakes, oversights, bad advice
Example claim Client slips in your lobby Missed tax deadline costs a client penalties
Included in a BOP? Usually yes Usually no
Who needs it Nearly every office with visitors Accountants, consultants, agencies giving advice
Policy trigger Usually occurrence-based Usually claims-made

Insuring a Collection of Multiple Vehicles

Once you own three, five or fifteen cars, insuring each one separately gets messy. You end up with mismatched renewal dates, different deductibles and valuations scattered across documents. Many carriers allow a collection to be written under one policy, which simplifies paperwork and may lower the overall cost compared with stand-alone policies.


Some carriers also offer flexible features for multi-vehicle owners, such as coverage that adjusts as you buy and sell cars or limits that apply across the whole collection. On the higher end, some carriers now treat these collections much like fine art. AIG's 2026 Collector Auto Class Endorsement, for example, can pay up to 150% of the scheduled limit if a vehicle's market value exceeds the agreed amount at the time of loss. That kind of protection may be worth a look for owners whose cars are appreciating quickly.


Bundling does raise the stakes on storage. If eight cars share one garage in Slidell, a single flood event can hit the whole collection at once. Ask how your policy handles a loss involving several vehicles, and whether your storage location affects that limit.


Keep an updated inventory with photos, VINs, appraisals and restoration records for every vehicle. It speeds up underwriting now and claims later.

How Jones Act Exposure Differs From State Workers Comp

Common Questions About Louisiana Classic Car Coverage

Can I drive my classic car to work occasionally? Most policies typically require that the vehicle not be your primary driver, and commuting is usually excluded. Some carriers may offer flexible usage tiers, so ask before assuming.


Does my car have to be a certain age to qualify? Not always. Many carriers consider age, condition and rarity, so a well-kept modern exotic or limited-production model may qualify too.


Do I need antique plates to get collector insurance? Usually not. The permanent antique plate, which requires a one-time $1,000 payment to the Office of Motor Vehicles, is tied to registration and tax exemption, not to buying a policy.


What happens if my car is still being restored? Some carriers may offer coverage for vehicles under restoration, with values that can increase as work progresses. Tell your agent the car's current condition.


Will flood damage from a hurricane be covered? Flood is typically covered under comprehensive on collector policies, but confirm it, along with any storm-related deductibles.


Can my teenager drive the classic? Many carriers restrict younger or less experienced drivers. Check the driver requirements before handing over the keys.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Feature General Liability Professional Liability (E&O)
What it covers Physical injuries and property damage Mistakes, oversights, bad advice
Example claim Client slips in your lobby Missed tax deadline costs a client penalties
Included in a BOP? Usually yes Usually no
Who needs it Nearly every office with visitors Accountants, consultants, agencies giving advice
Policy trigger Usually occurrence-based Usually claims-made

Making the Right Choice for Your Investment

Picking classic car coverage in Louisiana comes down to a few honest questions. Do you know exactly what you'll be paid after a total loss? Does your usage match the policy's rules? And do you have a real plan for getting the car out of harm's way when a storm turns toward St. Tammany Parish?


Getting those answers right takes more than one carrier's quote. As an independent agency, Aubert Insurance Agency compares options from multiple carriers, including those that may offer Guaranteed Value, so you can see the differences side by side. We'll also walk you through the fine print, from storage requirements to commuting exclusions, so nothing surprises you at claim time.


Your car took years to find, restore or keep in original condition. The coverage protecting it deserves the same care. Start a Quote with Kyle Beerbohm at Aubert Insurance Agency, and let's make sure your car's agreed value is ready before the next hurricane season arrives.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.

Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Visit

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
