













Louisiana Glass and Glazing Contractor Insurance

Covington & Slidell Independent Insurance Agents

Most Louisiana glazing contractors need three core policies: General Liability for third-party injury and property damage, Inland Marine (often an installation floater) for glass in transit and during install, and Workers Compensation for crew injuries. Coastal wind exposure and storefront work typically call for higher limits and Completed Operations protection.


A crate of tempered panels can crack because a forklift driver misjudged a curb. A 9-foot storefront lite can shatter because a suction cup lost seal. A residential job in Mandeville may be finished on Tuesday and tested by a tropical storm by Friday. Glass work carries a specific mix of risk: fragile, expensive materials, sharp edges, heavy loads, and a hurricane coast that tests every seal and anchor you install.


The gaps in coverage are just as specific. Plenty of glaziers carry a general liability policy and assume it covers everything. Then a $14,000 curtain wall unit breaks on the truck and they learn otherwise. The sections below cover breakage in transit and during install, impact-rated window work in wind zones, cuts and lifting injuries, and storefront completed operations, along with what each means for a Louisiana shop's insurance program.

Louisiana Glass and Glazing Contractor Insurance Requirements

Louisiana rules changed meaningfully in 2026, and glazing contractors should check where they stand. Effective August 1, 2026, Act 757 requires residential and home improvement contractors to carry at least $500,000 in general liability insurance, up from the previous $100,000. If you replace windows in homes around Covington, Slidell, or anywhere else in St. Tammany Parish, that change likely applies to you.


Commercial clients add their own demands. General contractors on storefront and office projects routinely require additional insured endorsements, waivers of subrogation, and higher per-project limits written into the subcontract. Read those insurance clauses before you sign, not after the certificate request arrives.


Cancellation rules shifted too. Under Advisory Letter 2026-01, surplus lines insurers must give at least 30 days' advance written notice before cancelling or non-renewing commercial property and casualty policies. Many coastal contractors are placed in that surplus lines market, so this gives you a little more time to find replacement coverage.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

Risk Comparison: Standard vs. Specialized Glazing Coverage

A basic contractor's liability policy and a program built for glazing look similar on a quote sheet. They behave very differently when glass breaks. The table shows where the gaps usually appear.

Coverage Area Basic Liability Only Specialized Glazing Program
Glass breaking on your truck Usually not covered Typically covered under Inland Marine
Glass breaking during install Often excluded as your own work May be covered by an installation floater
Glass stored at the jobsite Rarely covered Often included, with theft protection
Breakage limits None for your materials Set to match your largest job value
Injury to a passerby Covered Covered
Failure after job is done Depends on Completed Operations limit Completed Operations sized for storefront work
Crew injuries Not covered Workers Comp added to the program

The biggest misunderstanding is the second row. General liability exists to cover damage you cause to other people's property. The glass you bought and are installing is still your property until the job is accepted, so it usually sits outside that coverage.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Breakage in Transit and During Install

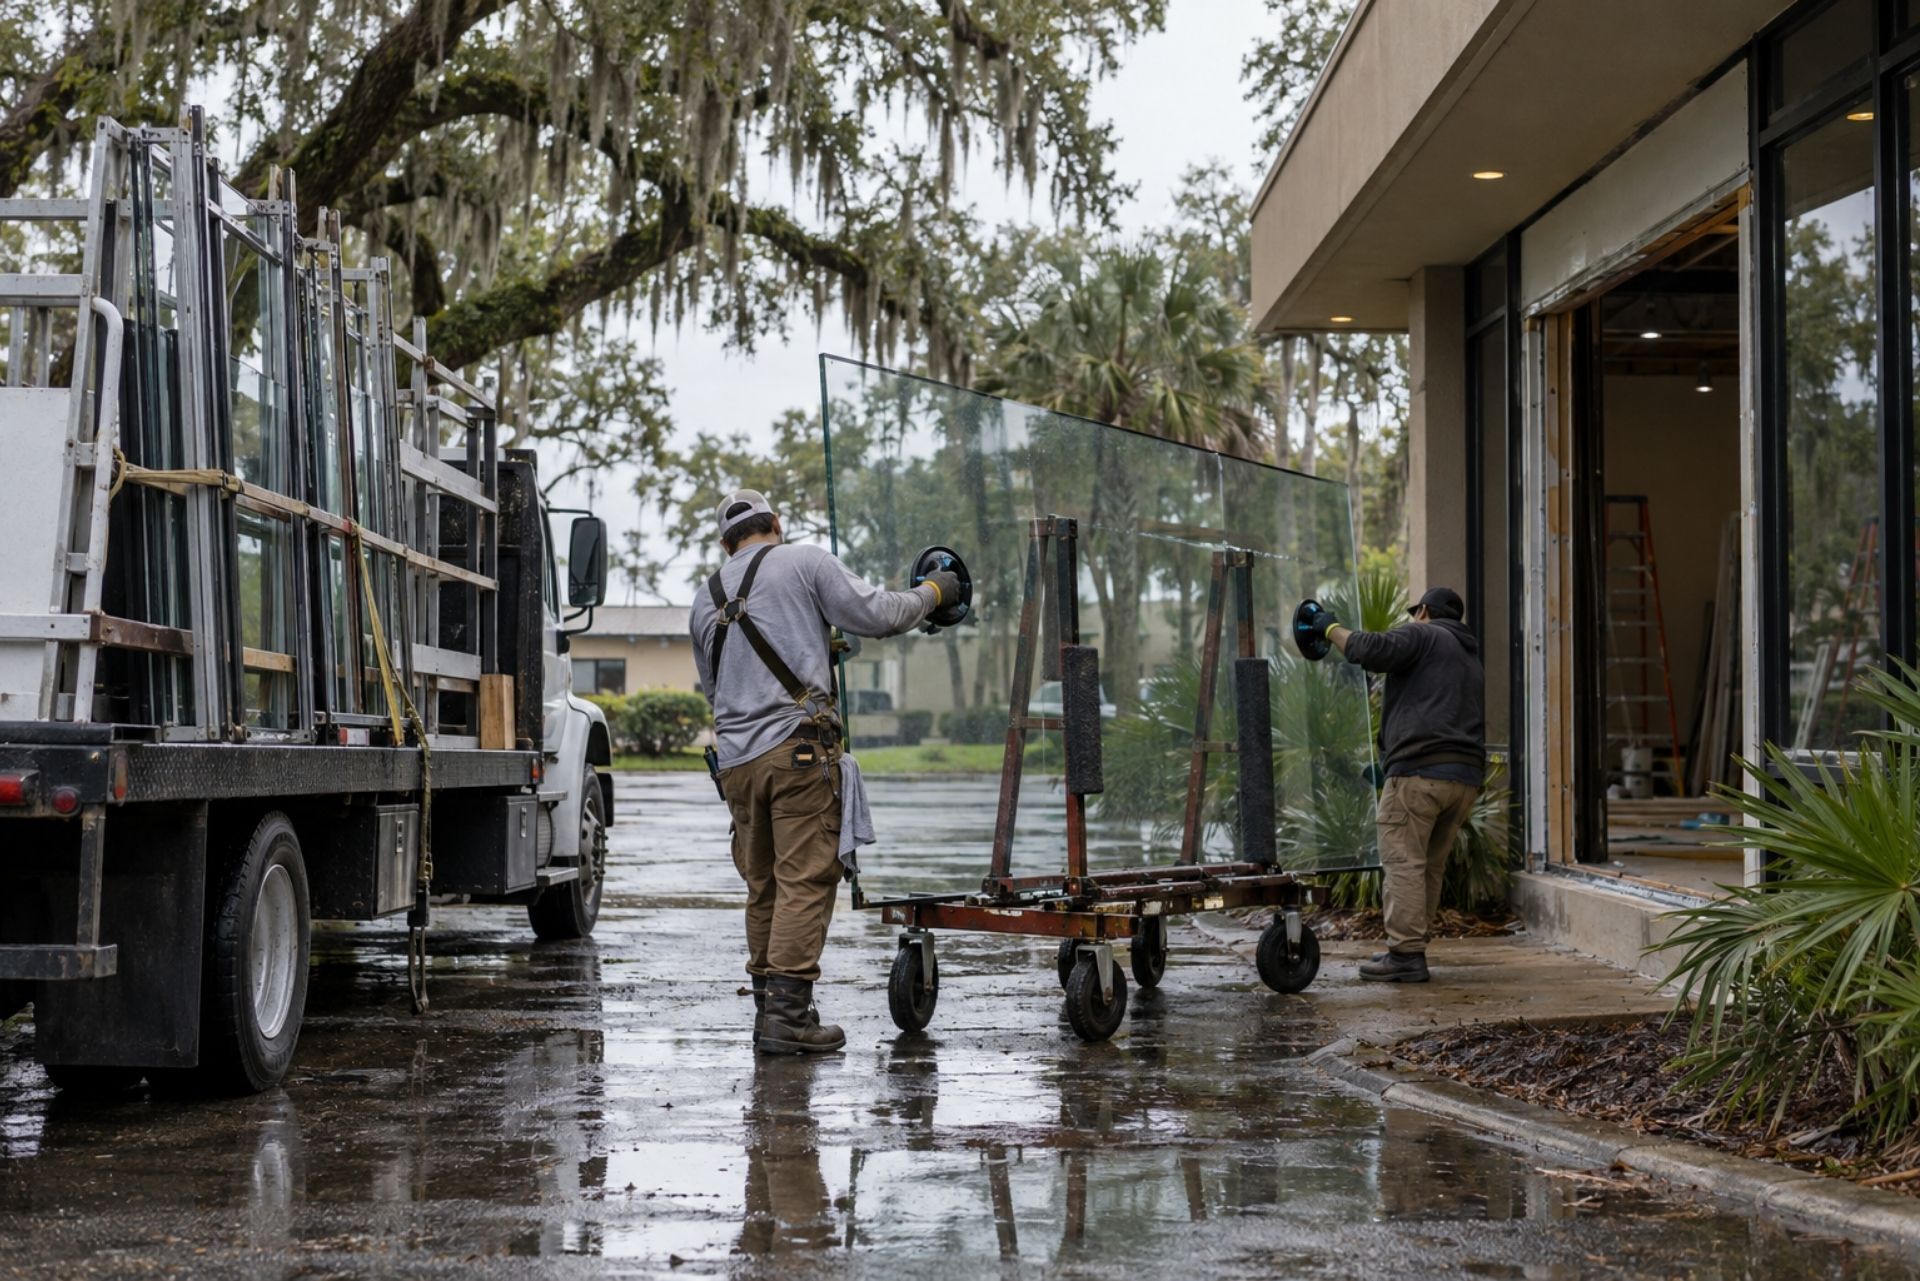
Here's a claim pattern that shows up over and over. A crew picks up insulated glass units from a distributor, drives across the Causeway, and hits a pothole hard enough to crack three units on the A-frame. The owner files a claim under general liability and gets a denial. Standard GL may not cover glass while it is being moved or installed, because nobody else's property was damaged.


The fix is Inland Marine coverage, typically written as an installation floater or contractor's equipment and materials form. These policies follow your materials from the supplier's dock, onto your truck, into temporary storage at the site, and up to the point of installation. Depending on the carrier, coverage may apply to:


  • Transit breakage from road impact, collisions, or shifting loads
  • Handling breakage when a lite slips during setting or glazing
  • Jobsite storage losses, including theft and vandalism
  • Equipment such as vacuum lifters, glass dollies, and suction rigs


Limits matter here. Set the per-location limit high enough to cover the full value of glass on site for your largest current project, not your average one. Custom and laminated units can carry long lead times, so ask whether the policy may also pick up expediting costs.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Impact-Rated Window Work in Wind Zones

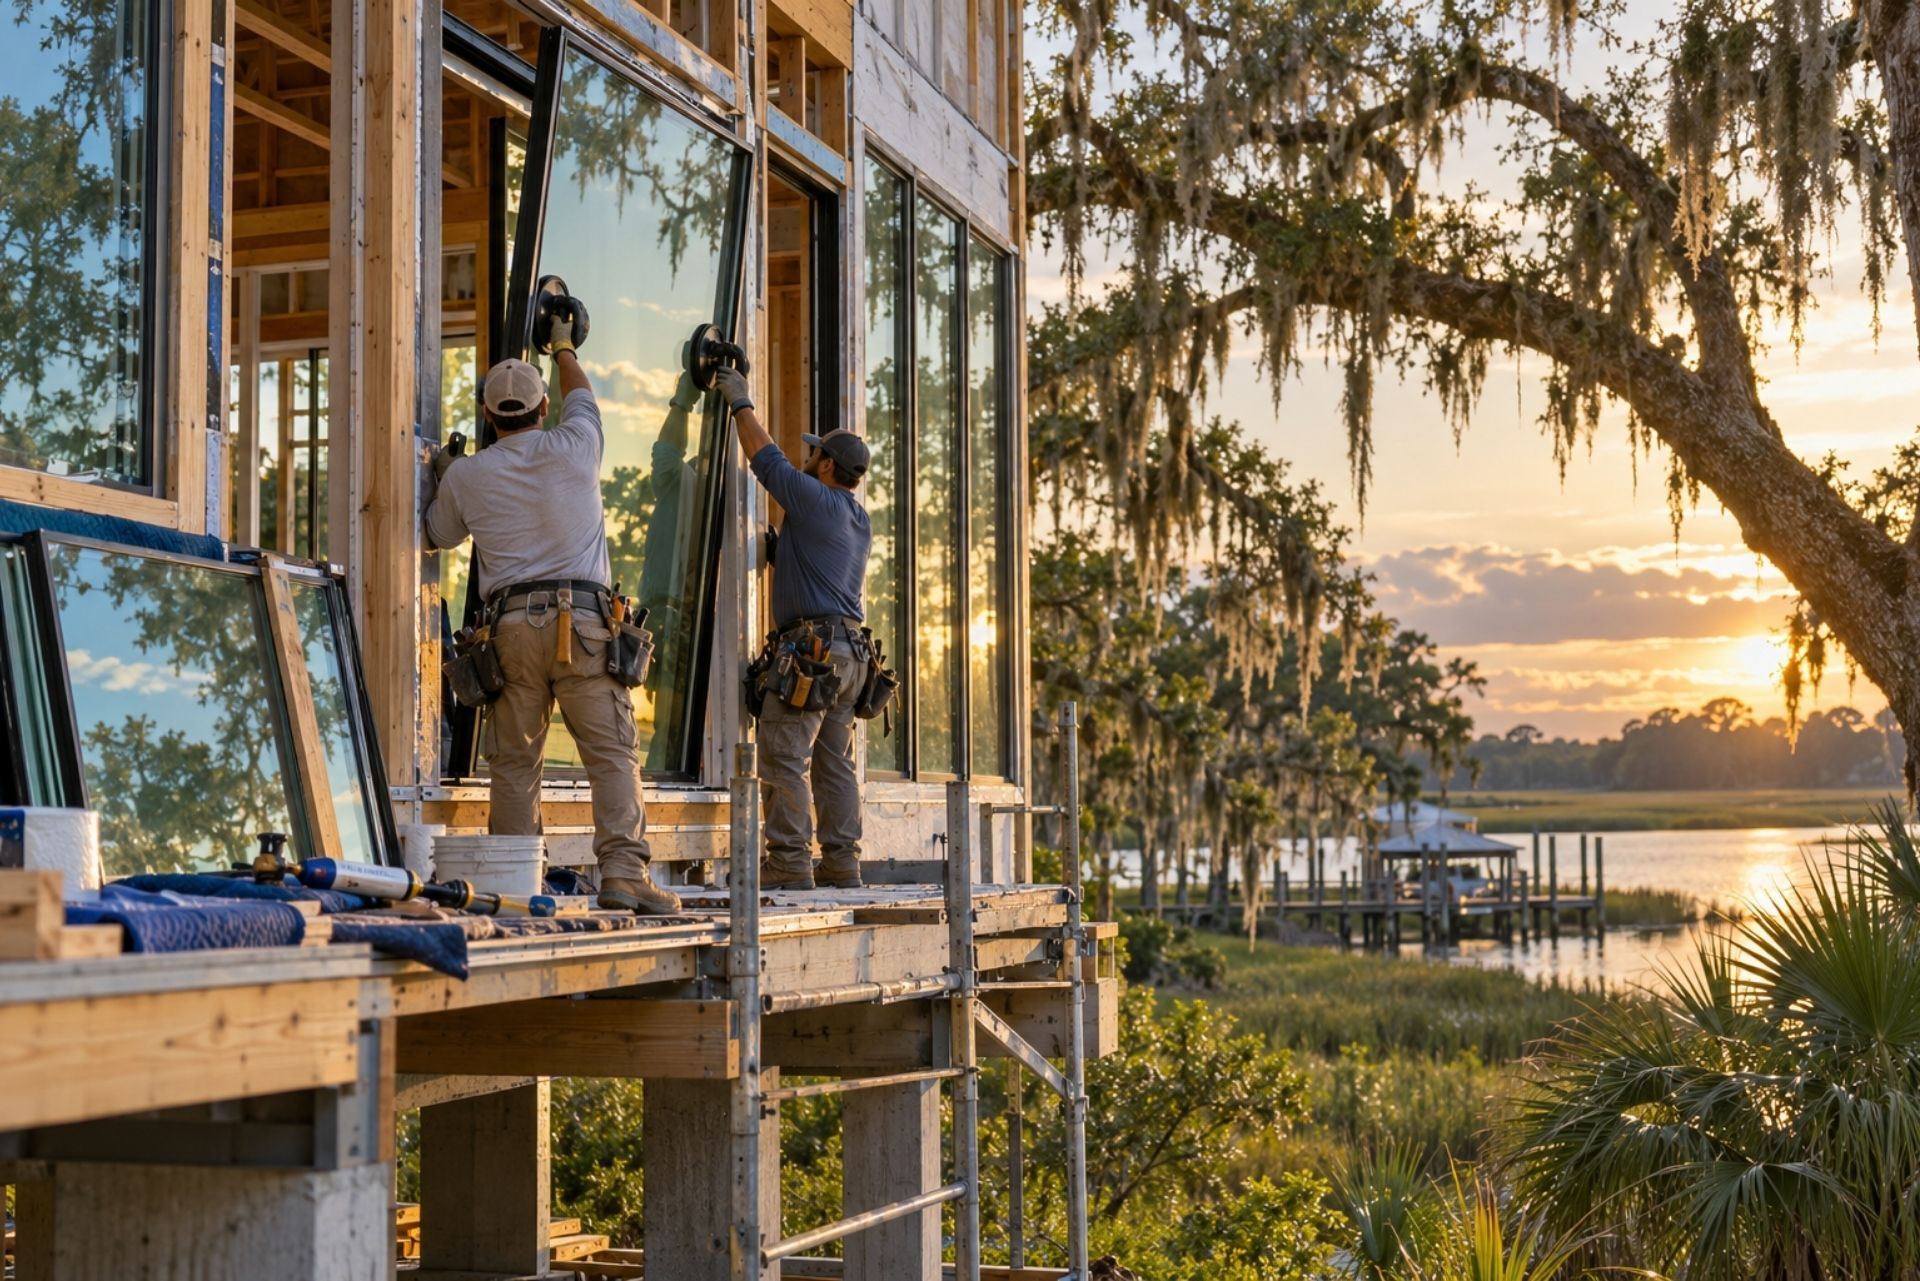
South Louisiana sits inside some of the most demanding wind design zones in the country. Parishes along the coast and around Lake Pontchartrain often require impact-rated glazing or approved opening protection, and the installation has to match the product's tested assembly. That means correct anchor type, spacing, embedment, and sealant, exactly as the product approval specifies.


The risk for contractors is that impact-rated glass is judged under the worst possible conditions. When a hurricane pushes through Slidell and a window fails, the homeowner's property insurer pays the claim and then often looks for someone to recover from. If an adjuster finds missing fasteners or a substituted frame, your company becomes the target of a subrogation claim.


Proper coverage may protect you in a few ways. Your general liability policy, with adequate Completed Operations limits, can respond to property damage from water intrusion after a failure. Some carriers also offer contractor's professional or faulty workmanship endorsements, though wording varies widely and many exclude the cost to redo your own work.


The best protection on paper starts with records. Photograph anchor patterns, keep product approval documents in the job file, and log inspections. When a claim comes in two years later, those photos may be the difference between a quick defense and an expensive settlement.

Covington & Slidell Independent Insurance Agents

Managing Cuts and Lifting Injuries

Glass work produces some of the most frequent and costly Workers Compensation claims in construction. Lacerations happen when panels break during handling or when edges are carried without gloves and sleeves. Back, shoulder, and hernia injuries come from lifting heavy units by hand, especially on residential jobs where there's no room for equipment. National workplace injury and illness rates by industry consistently place specialty trade contractors among the higher-risk groups.


Workers Comp pays medical bills and lost wages, and in Louisiana it's generally required once you have employees. Your premium is driven by payroll, job classification, and your experience modifier. One bad year of lacerations and back strains can push your mod up and raise costs for three years.


Safety programs are where you actually control that number. The ones that seem to work in glazing shops are simple and enforced:


  1. Cut-resistant gloves and sleeves required for every glass touch, no exceptions
  2. A two-person or mechanical lift rule above a set weight
  3. Vacuum lifters and glass carts on every job where they fit
  4. A short tailgate meeting before any large-lite set
  5. Prompt reporting of every cut, even minor ones, so small injuries get treated before they become infections and bigger claims


Many carriers may offer loss control visits and training materials at no extra charge. Use them.

not, unless you're both named on the policy. Each roommate typically needs their own coverage, and shared policies can get messy when one person files a claim.


Will my renters insurance cover my dog biting someone? Many policies include pet liability under personal liability, but some carriers exclude certain breeds or cap dog bite claims. Tell your agent about your pet upfront so there's no surprise later.


Does my landlord's insurance cover my belongings? No. Your landlord's policy typically covers the building only, so your furniture, clothes and electronics need your own policy.


When should I buy flood insurance before hurricane season? Aim for spring. NFIP contents coverage generally has a 30-day waiting period, so buying in late May means protection by the heart of the season.


What should I do to prepare my rental for a hurricane? Take a video walkthrough of every room, save receipts for big items in the cloud and keep a copy of your policy on your phone. Good documentation is the single biggest factor in how fast a storm claim gets paid.


Will renters insurance pay for a hotel if we evacuate? It depends. Loss of use typically kicks in when your rental is uninhabitable from a covered loss or when a civil authority orders evacuation, but check your policy wording.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Coverage What It Covers Example Claim Required for License?
General Liability Injury to others, damage to client property Dust ruins a homeowner's sofa Yes, $500,000 minimum (residential)
Workers' Compensation Your employees' injuries and lost wages Taper falls from stilts Required if you have employees; proof needed for labor-only subs
Professional Liability Errors in advice or design Rarely relevant unless you design or consult No
Mold Buy-Back Limited mold claims, if offered Mold blamed on board you installed No, but often worth considering

Storefront Completed Operations

Your liability does not end when you collect the final payment. Storefront work in particular carries long-tail risk, because thousands of people walk past or through your installation every year.


Picture a retail entrance you installed on Northshore Boulevard. Eight months later, a door closer fails, a tempered panel shatters, and a customer is cut. Or a large display lite that was set without proper setting blocks slowly shifts and falls out of the frame. Neither event happens during your work, yet both may trace back to it.


Completed Operations coverage, part of your general liability policy, is designed for exactly this. It may apply to bodily injury and property damage that occurs after your work is finished and the project is turned over. In the glass and sign trades, the completed operations aggregate is often set at $2,000,000, and many commercial general contractors will require that level or higher.


Two things to watch. First, make sure the Completed Operations aggregate isn't shared so tightly with your general aggregate that one claim exhausts both. Second, if a GC requires that you name them as additional insured for completed work, confirm the endorsement actually extends to completed operations and not just ongoing work. That single form number trips up a lot of contractors.

Frequently Asked Questions About Glazing Insurance

Does my insurance cover glass I break while carrying it? Usually not under general liability, since the glass is your own property. An Inland Marine policy or installation floater typically covers breakage during handling and setting.


Do I need special coverage for hurricane windows? You don't need a separate policy, but you should have strong Completed Operations limits and clear documentation of each install. Failures after a storm can lead to subrogation claims years later.


Does the new $500,000 requirement apply to commercial glazing? Act 757 applies to residential and home improvement contractors. Commercial work is usually governed by contract terms, which often require higher limits anyway.


Is the glass stored at a jobsite covered if it gets stolen? Many Inland Marine forms may include jobsite storage and theft, though some limit coverage or require secured storage. Check the policy wording.


Will a few cut claims really raise my premium? They can. Frequent small Workers Comp claims affect your experience modifier, which may raise your rates for several years.


What happens if my carrier decides not to renew? If you're insured in the surplus lines market, Louisiana now requires at least 30 days' written notice, giving you time to shop replacement coverage.

The roof

Age, material and shape drive the wind rate more than any other factor. A fortified roof designation opens markets that would otherwise decline the house.

Making the Right Choice for Your Louisiana Business

Glass contractors face a specific stack of risks: materials that break before they're installed, wind-zone work that gets tested by storms, crews exposed to cuts and heavy lifts, and storefront installations that carry liability long after the job closes. A single general liability policy doesn't cover all of that. A coordinated program of GL with solid Completed Operations limits, Inland Marine, and Workers Comp typically does.


Aubert Insurance Agency has been insuring what matters most to Louisiana families and businesses since 1910. As an independent agency serving Covington, Slidell, and St. Tammany Parish, we compare coverage from multiple carriers and walk you through what your policy covers and what it excludes, so the surprises stay out of your claims.


Kyle Beerbohm and the team can review your current coverage, flag the gaps around transit breakage and completed operations, and shop options that fit the way your crews actually work. Start a Quote today and get your glazing business covered before the next truckload or the next storm season.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
