













Louisiana Auto Dealer Insurance

Covington & Slidell Independent Insurance Agents

Louisiana auto dealer insurance typically combines two state-required pieces, a motor vehicle dealer surety bond and a garage liability filing, with optional physical damage coverage for the cars on your lot. For dealers in Covington, Slidell, and across St. Tammany Parish, Dealers Open Lot coverage may be the piece that protects inventory from hail, flood, and theft.


Most dealers get their bond and liability certificate because the licensing paperwork demands it. The coverage that actually saves a dealership after a bad storm or a bounced cashier's check is often the part nobody explained.

Louisiana Auto Dealer Insurance Requirements and Coverage Options

Louisiana splits dealer oversight between two agencies. The Louisiana Motor Vehicle Commission (LMVC) regulates new and franchise dealers, while the Louisiana Used Motor Vehicle Commission (LUMVC) handles used dealers, so your license type determines which commission you answer to. That split affects your bond amount, your filing requirements, and who you call when something lapses.


A typical dealer insurance program in this state includes:


  • Surety bond: Required for licensing. The amount depends on whether you sell new or used vehicles.
  • Garage liability: Covers bodily injury and property damage from your operations, including customers on your lot and employees driving inventory.
  • Dealers Open Lot (DOL): Physical damage coverage for the vehicles you own and hold for sale.
  • Endorsements: Add-ons like False Pretense coverage that close gaps the standard forms leave open.


The first two keep your license active. The last two keep your business solvent when inventory takes a hit.

By: Kyle Beerbohm
President

Aubert Insurance Agency is a local, independent agency, licensed to serve individuals and businesses across Louisiana, Mississippi, Florida and Texas.

We serve clients from our offices in Covington and Slidell and throughout St. Tammany Parish — working with dozens of carriers and wholesale markets to help homeowners, drivers, contractors, restaurant owners, property investors, auto shops, professional practices and many other personal and commercial clients find coverage that fits.

Licensed in Louisiana #3661 · Mississippi #15039075 · Florida #W0772236 · Texas #2381820

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

Here's a common scenario: you misjudge a curve and clip a late-model pickup, injuring the driver. A single ambulance ride, ER visit, and follow-up imaging can eat through $15,000 quickly. Anything above your limit can become your personal responsibility, which may put your savings, wages, or home at risk.

Scenario Dwelling limit All-other-perils deductible Named-storm deductible
Newer build, inland St. Tammany $350,000 $1,000 2%
Newer build, higher wind zone $350,000 $1,000 5%
Older home, updated roof $275,000 $2,500 2%
Older home, original roof $275,000 $2,500 5%
Fortified roof designation $400,000 $1,000 2%
Rebuilt after a prior claim $400,000 $2,500 5%
Bundled with auto $350,000 $1,000 2%

Dealers Open Lot: Protecting Inventory from Hail and Flood

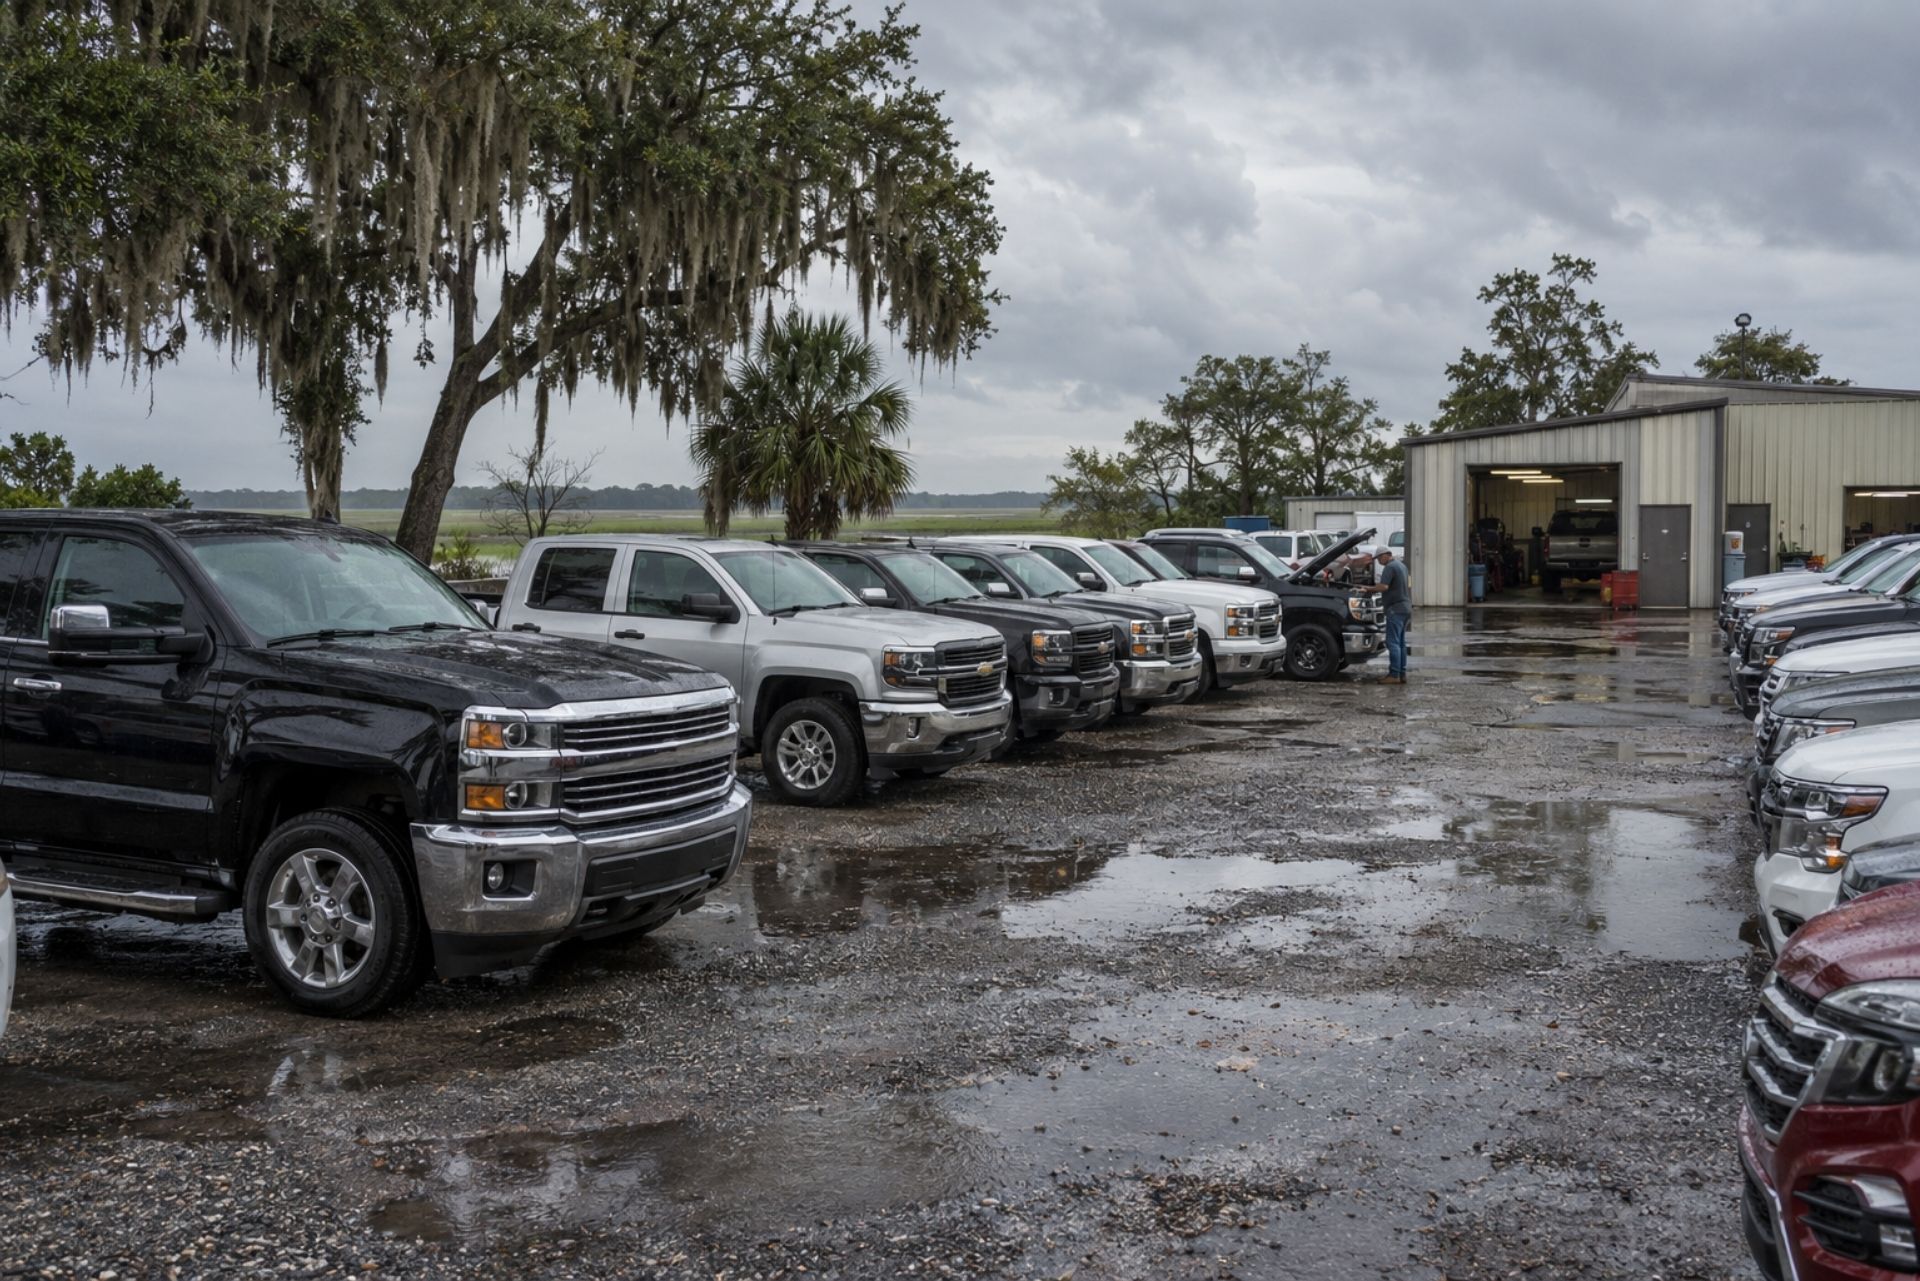
Picture a used lot on Highway 190 in Covington with 60 units parked under open sky. A spring storm drops golf-ball hail for twelve minutes, and every hood, roof, and trunk lid now needs paintless dent repair or replacement panels. Your garage liability policy won't pay a dime for that, because liability covers damage you cause to others, not damage to your own stock.


Dealers Open Lot coverage is built for exactly this. Policies typically cover vehicles you own while on your premises, in transit, or temporarily off-site, against perils like hail, wind, fire, theft, and vandalism. Some carriers may write coverage on a reporting basis, where you report inventory values monthly and the premium adjusts.


Slidell dealers face a different worry. Low-lying areas near Bayou Bonfouca and the lake can take on water fast during a tropical system, and a flooded car is often a total loss. Read the flood provisions carefully, because some DOL forms may exclude flood, limit it by location, or carry a separate higher deductible. Your building and contents are a separate issue: non-residential NFIP flood limits are typically capped at $500,000 for the building and $500,000 for contents, and that contents coverage generally isn't designed to protect vehicle inventory. A practical habit: have a written plan for moving units to higher ground when a storm watch goes up, and confirm whether your policy covers cars while relocated.

With no lender to satisfy, the decision is yours, and so is the entire loss. A total rebuild in this parish runs well into six figures.

Homeowners who own outright

Your lender requires coverage at least equal to the loan, and will buy a policy on your behalf at your expense if yours lapses.

Homeowners with a mortgage

Coverage Area State Minimum Common Higher Option Stronger Option
Injury, one person $15,000 $50,000 $100,000
Injury, per accident $30,000 $100,000 $300,000
Property damage $25,000 $50,000 $100,000
Who it fits Legal compliance only Riders with modest assets Homeowners, families, higher earners

Here's a common scenario: you misjudge a curve and clip a late-model pickup, injuring the driver. A single ambulance ride, ER visit, and follow-up imaging can eat through $15,000 quickly. Anything above your limit can become your personal responsibility, which may put your savings, wages, or home at risk.

Minimum Coverage vs. Actual Protection Needs

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

The State Motor Vehicle Dealer Bond and Garage Liability Filing

Used motor vehicle dealers in Louisiana must post a $50,000 surety bond with the LUMVC. New and franchise dealers face a lower amount, since the LMVC requires a $20,000 surety bond for those applicants. The bond protects consumers, not you. If a customer wins a claim because a title wasn't delivered or a sale was misrepresented, the surety pays and then comes to you for reimbursement.


Garage liability is the other half of licensing. Used dealers submit an Acord Certificate of Liability Insurance to the LUMVC that lists every insured salesperson and names the commission as certificate holder. A common mistake here: hiring a new salesperson and forgetting to update the certificate, which can create a paperwork gap right when you need clean records.


Keep your policy active without interruption. Under Louisiana law, failing to maintain required insurance triggers immediate license suspension, with revocation following if proof isn't provided within 30 days. Set your renewals on autopay or calendar reminders, and ask your agent to confirm the commission received the updated certificate after any change.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.

Feature Commercial Property Inland Marine (Tool Floater)
Where it applies Your fixed shop location Jobsites, truck, in transit
Typical items Stationary machines, inventory, building Portable saws, nailers, hand tools
Theft from vehicle Usually not covered Often covered, with conditions
Fire or storm at shop Typically covered May be covered if tools are there
Who needs it Carpenters with a shop Nearly every working carpenter

Managing Risks During Test Drives and Loaner Vehicle Use

Every time a key leaves your hand, your exposure changes. Test drives and loaners are where dealers most often discover what their policy actually says.

Liability Exposure for Customer Test Drives

Louisiana's omnibus clause makes this personal for dealers. An owner's policy must cover any person using the vehicle with express or implied permission, and the vehicle owner during a test drive is you. That means when a customer rear-ends someone on Gause Boulevard during a test drive, your garage liability policy is likely first in line.


Some dealer policies may treat the customer's own auto policy as primary in certain situations, but don't count on that. Simple controls help: photocopy every license, verify it's valid, have a salesperson ride along when possible, and keep a signed test drive log with times and routes.

Handling Loaner Car Incidents

Loaners are trickier than test drives because the customer may keep the car for days. The omnibus clause in La. R.S. 32:900 still reaches permissive users, so a loaner accident can land on your policy. Damage to the loaner itself typically falls under your DOL or physical damage coverage, often with a deductible you absorb.


Use a written loaner agreement that states the return date, prohibits other drivers, and requires the customer to show proof of their own insurance. Ask your agent whether loaner and service vehicles are scheduled correctly, since some policies may treat them differently from retail inventory.

General liability covers physical harm: fires, shocks, and property damage from your work. Professional liability, sometimes called errors and omissions, may cover financial loss from design mistakes or bad advice, such as an undersized service you specified on a load calculation. Electricians who do design-build work, panel sizing for solar, or consulting often need both, because a general liability policy typically will not respond to a pure financial loss.

False Pretense Theft: When Scams Impact Your Inventory

Here's a claim that surprises dealers every year. A buyer shows up with a cashier's check that looks perfect, drives off with a truck, and three days later your bank tells you the check was forged. You call your carrier expecting a theft claim, and the adjuster explains that you voluntarily handed over the keys.


Standard physical damage forms typically exclude this kind of loss. Because the dealer was tricked into parting with the vehicle rather than having it stolen outright, coverage generally requires adding the CA 25 03 False Pretense endorsement. Without it, that theft is entirely your loss.


Scams that commonly lead to these claims include:


  • Fraudulent payment: Forged cashier's checks, fake wire confirmations, or reversed electronic payments.
  • Identity fraud: A buyer finances or purchases under a stolen identity.
  • Transport cons: Someone posing as a hauler or another dealer picks up a vehicle that never arrives.


The endorsement may carry its own sublimit, so check whether it matches the value of your higher-priced units. Pair it with process discipline: never release a vehicle until funds clear, and call issuing banks directly using a number you look up yourself.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.

Feature Commercial Property Inland Marine (Tool Floater)
Where it applies Your fixed shop location Jobsites, truck, in transit
Typical items Stationary machines, inventory, building Portable saws, nailers, hand tools
Theft from vehicle Usually not covered Often covered, with conditions
Fire or storm at shop Typically covered May be covered if tools are there
Who needs it Carpenters with a shop Nearly every working carpenter

Comparing Louisiana Dealer Insurance Coverages

These three coverages get confused constantly, especially by dealers who assume "full coverage" means everything. Here's how they differ in plain terms.

Coverage What It Protects Common Example Required?
Garage Liability Injuries and damage you cause to other people or their property Customer slips on your showroom floor; test driver hits another car Yes, for licensing
Dealers Open Lot Physical damage to vehicles you own for sale Hail dents 40 cars; flood or theft from the lot No, but strongly advisable
False Pretense Vehicles you were tricked into handing over Buyer pays with a forged check and disappears No, added as an endorsement

Notice the pattern. Liability looks outward at other people, DOL looks inward at your inventory, and False Pretense covers the specific fraud gap DOL usually leaves behind. A dealer with only the licensing minimums has protected the commission and the public, but not the cars that make up most of the business's value.

Frequently Asked Questions About Dealer Insurance

How much is the dealer bond in Louisiana? Used dealers post a $50,000 bond with the LUMVC, and new or franchise dealers post a $20,000 bond with the LMVC. Your premium is a small percentage of that amount, typically based on credit and experience.


Does garage liability cover hail damage to my cars? No. Garage liability covers damage you cause to others, so hail on your inventory needs Dealers Open Lot or similar physical damage coverage.


Who pays if a customer crashes during a test drive? Your dealer policy is usually involved because Louisiana's omnibus clause extends coverage to permissive drivers. The customer's own policy may also respond, depending on policy terms.


Is flood included in Dealers Open Lot coverage? It depends on the carrier and form. Some policies may include flood with a higher deductible, while others restrict or exclude it, so confirm before storm season.


What happens if my insurance lapses? Your license can be suspended immediately, and revocation may follow if you don't provide proof of coverage within 30 days.


Do I really need False Pretense coverage? If you ever accept checks, wires, or deal with unfamiliar buyers or haulers, it's worth serious consideration. Without it, a fraud loss on one vehicle typically falls entirely on you.

The jump from minimum limits to 100/300/100 often costs less than riders expect, because liability is typically priced per added layer rather than doubling with the limits. Ask for quotes at two or three levels side by side before you decide.

One tip: keep a dated list of serial numbers and photos of your tools. Claims with documentation move much faster than claims built on memory.

Feature Commercial Property Inland Marine (Tool Floater)
Where it applies Your fixed shop location Jobsites, truck, in transit
Typical items Stationary machines, inventory, building Portable saws, nailers, hand tools
Theft from vehicle Usually not covered Often covered, with conditions
Fire or storm at shop Typically covered May be covered if tools are there
Who needs it Carpenters with a shop Nearly every working carpenter

Making the Right Choice for Your Dealership

The dealers who come through a hurricane season or a check-fraud scheme in good shape usually share one trait: they knew what their policy covered before the loss. Your bond and garage liability filing keep the doors open. Dealers Open Lot, solid test drive and loaner procedures, and the False Pretense endorsement keep a single bad day from wiping out a year of profit.


Coverage forms vary widely between carriers, which is why comparing options matters. Aubert Insurance Agency is an independent agency, so it can shop multiple carriers for your dealer program and walk you through the exclusions line by line instead of handing you a policy and hoping. That educational approach matters when a single word in a flood provision decides whether 30 cars get paid.


Aubert has been insuring Covington, Slidell, and St. Tammany Parish businesses since 1910, and the process is simple: start online, let the agency shop for you, and pick the plan that fits your lot. Whether you run a ten-car used lot or a franchise store, Start a Quote today and find out where your gaps are before the next storm finds them for you.

About the Author

Kyle Beerbohm

President


We've been independent since 1910, and four generations of local ownership have kept us that way. We're one of the oldest agencies in St. Tammany Parish and the fourth oldest business in the City of Covington. I treat that history as a responsibility rather than a plaque on the wall. My job is to keep us answering to the families and business owners who walk through our doors, and to keep serving this parish for another hundred years.

Louisiana Insurance Questions, Answered

Questions clients ask us

Short, plain answers to what people ask before they call. Anything else, phone the office and ask.

  • What does an independent insurance agency do?

    We represent you, not one insurance company. We gather your information once, then compare coverage and price across the carriers we hold contracts with. You get choices, and one agent handles the paperwork.

  • Which types of insurance does Aubert offer?

    We write 13 personal lines, including home, auto, flood, boat, and life. We write 15 commercial lines, including business owners policies, general liability, workers compensation, and commercial property.

  • Do I need flood insurance in St. Tammany Parish?

    Your homeowners policy excludes flood, and much of the Northshore has flooded outside mapped high-risk zones. Lenders require it inside those zones. We check your flood zone and quote NFIP and private options.

  • Which states are you licensed in?

    We hold licenses in Louisiana, Mississippi, Florida, and Texas. License numbers appear in the footer of every page on this site.

  • How do you find me a competitive rate?

    We take your details once and market them to the carriers and wholesale brokers that fit your risk. We compare the offers, explain the differences in coverage, and recommend the strongest fit.

  • How do I file a claim or request a certificate?

    Call the office or use the Client Center on this site. We report the claim, follow the adjuster, and send certificates of insurance to whoever needs them.

Personal Insurance in Louisiana

Coverage for your home, your vehicles, and your family

Thirteen personal lines sit under one roof. Start with the coverage you need most, and we price it across our markets.

Home Insurance

Protect your house, its contents, and your liability with a policy priced across many Louisiana homeowners carriers.

Car Insurance

Cover every driver and vehicle in your household, and compare limits and deductibles side by side before you buy.

Flood Insurance

Standard home policies exclude flood. We write NFIP and private flood coverage for St. Tammany Parish properties.

Umbrella Insurance

Add a layer of liability above your home and auto limits, so one serious claim never reaches your savings.


Boat Insurance

Cover your hull, motor, trailer, and liability on the lake, the river, and the Gulf, wherever you launch.


Life Insurance

Replace your income for the people who depend on it, with term and permanent options we quote across carriers.

Business Insurance in Louisiana

Coverage for the business you built

Fifteen commercial lines, written for the payrolls, fleets, and buildings that Louisiana carriers ask hard questions about.

Business Insurance by Industry

We protect hundreds of businesses of all shapes and sizes

We know the exposures, the contract language, and the markets that write these trades on the Northshore.

General Contractors

Builders risk, general liability, and comp for homebuilders and remodelers working across St. Tammany Parish.

Plumber Insurance

Plumbers, electricians, roofers, and painters get liability, tools, and auto coverage that satisfies job requirements.

Restaurants

Property, liquor liability, spoilage, and comp for kitchens, bars, and cafés, including Louisiana association programs.

5-Star Rated by St. Tammany Clients

What Our Clients Say

Neighbours, business owners, and families across Covington and Slidell tell the story better than we can.

Insurance Tips & Local News

Insurance tips for Louisiana homes and businesses

Practical reading on flood zones, hurricane deductibles, and the coverage questions local business owners raise.

louisiana citizens homeowners insurance what you need to know
15 October 2026
Learn about Louisiana Citizens homeowners insurance costs, coverage, eligibility, and switching to private insurers with Aubert Insurance Agency.

certificate of insurance requirements for louisiana subcontractors
15 October 2026
Learn Louisiana subcontractor COI requirements, liability limits, additional insured endorsements, and waivers of subrogation with Aubert Insurance Agency.

general liability cost for louisiana contractors
15 October 2026
Learn Louisiana contractor general liability insurance costs by trade, payroll, sales, and minimum premiums. Compare quotes with Aubert Insurance Agency.

louisiana fortify homes program insurance discount
15 October 2026
Explore Louisiana Fortify Homes Program grants up to $10,000, FORTIFIED roof standards, and insurance premium credits with Aubert Insurance Agency.

how does builders risk insurance work in louisiana
15 October 2026
Learn how Louisiana builders risk insurance protects spec and custom homes, who buys coverage, when it ends, and storm risks with Aubert Insurance Agency.

what is the lhba general liability trust
15 October 2026
Explore the LHBA General Liability Trust in Louisiana, how pooled coverage works, builder eligibility, dividends, and risks with Aubert Insurance Agency.

what is the homebuilders self insurers fund
15 October 2026
Explore Louisiana's Homebuilders Self Insurers Fund, how workers comp coverage works, membership eligibility, dividends, and risks with Aubert Insurance Agency.

workers comp cost for louisiana contractors
15 October 2026
Learn Louisiana contractor workers comp costs, class codes, payroll rates, experience mods, and audit risks. Compare quotes with Aubert Insurance Agency.

who needs workers comp in louisiana
15 October 2026
Learn who needs workers comp in Louisiana, including employer rules, owner exemptions, subcontractor risks, and penalties with Aubert Insurance Agency.

louisiana contractor license insurance requirements
15 October 2026
Learn Louisiana contractor insurance requirements for residential, home improvement, and commercial licenses. Compare coverage with Aubert Insurance Agency.


Request Your Free Insurance Quote

Tell us what you need covered

Send the form or call the office. A licensed agent in Covington or Slidell answers you directly.

614 E. Boston St., Covington, LA 70433.  (985) 892-3101

58418 Tyler Drive, Slidell, LA 70461 ·   (985) 641-0520

Call

Covington office, Monday through Friday

Email

Policy questions, certificates, and claims

Call

614 E. Boston St., Covington, LA 70433

58418 Tyler Drive, Slidell, LA 70461
